
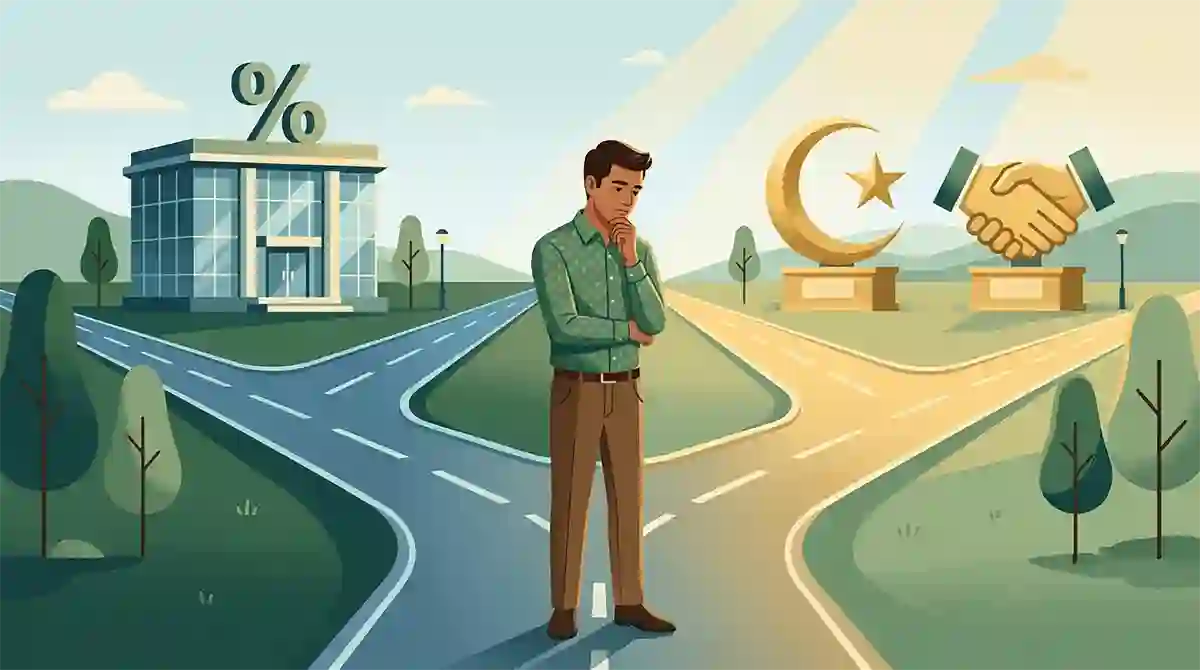
A few years ago, a relative of mine was setting up a new bank account and the officer asked him whether he wanted a conventional or Islamic account. He paused for a few seconds, then said “Islamic” mostly because it felt like the safer answer in front of other people at the branch. He had no idea what the actual difference was. Here in this article, you’ll learn the difference between Islamic Banking vs Conventional Banking.
When he got home, I asked him what he thought the difference was. He said, “I think Islamic banking doesn’t charge interest?” He was partially right, but he had no real understanding of how it actually worked, whether the returns were different, or whether it genuinely operated differently from the conventional account he had held for the previous decade.
Honestly, most people I know are in the same position. They have a vague sense that Islamic banking is Shariah-compliant and does not involve interest, but beyond that, the details are fuzzy. And those details actually matter, both for religious reasons and for practical financial decision-making.
Table of Contents
The Core Difference: Interest vs Profit Sharing
The single biggest difference between Islamic and conventional banking comes down to one word: riba.
Riba, broadly translated as interest or usury, is prohibited in Islam. Conventional banking is built entirely around interest. When you take a loan from a conventional bank, you pay back the principal plus a fixed percentage of interest. When you deposit money in a conventional savings account, the bank pays you a fixed interest rate on your balance. The bank makes its money by borrowing at a lower rate and lending at a higher one. That spread is its profit.
Islamic banking rejects this model entirely, at least in principle. Instead of charging or paying interest, Islamic banks use profit-and-loss sharing arrangements and asset-backed transactions. Money cannot generate more money on its own simply by sitting somewhere. Any return must come from a real economic activity, a trade, a service, a physical asset.
That is the philosophical foundation. Now let’s look at what this actually means in practice.
Learn more: What is a Bank Account? Types of Bank Accounts in Pakistan Explained
How Islamic Banking Actually Works
Islamic banking uses a set of Shariah-compliant financial contracts to replicate the functions of conventional banking without involving interest. Here are the main ones you will come across.
Murabaha
This is one of the most commonly used Islamic financing structures, especially for consumer loans and vehicle financing. Instead of lending you money to buy something and charging you interest, the bank buys the asset itself and then sells it to you at a higher agreed price, payable in installments.
For example, if you want to buy a car worth PKR 2,000,000, the bank purchases the car and sells it to you for PKR 2,400,000 payable over three years. The PKR 400,000 difference is the bank’s profit, not interest. The distinction matters legally and theologically, because the transaction involves a real asset and a genuine sale, not a loan with interest attached.
Musharakah and Diminishing Musharakah
Musharakah means partnership. Both you and the bank contribute capital to a venture or asset, and profits are shared according to a pre-agreed ratio while losses are shared in proportion to each party’s investment.
Diminishing Musharakah is commonly used in home financing. The bank and the customer jointly purchase a property. The customer pays rent for using the bank’s share, and gradually buys out the bank’s portion over time until they own the property fully. It functions similarly to a mortgage but without the fixed interest element.
Mudarabah
This is a profit-sharing arrangement where one party provides the capital and the other provides the expertise and management. In a savings context, you provide the money, the bank manages and invests it, and profits are shared according to a pre-agreed ratio. Losses, in theory, are borne by the capital provider unless caused by negligence.
Your Islamic savings account operates on a Mudarabah basis. The bank pools your deposits with others, invests them in Shariah-compliant activities, and distributes a share of the profit back to you. This is why Islamic savings accounts technically pay a profit share rather than a fixed interest rate.
Ijarah
Ijarah simply means leasing. The bank purchases an asset and leases it to you for an agreed period and rental amount. At the end of the lease, ownership may transfer to you. This is commonly used for equipment financing and vehicle leasing.
Islamic Banking in Pakistan: The Landscape
Pakistan has one of the most developed Islamic banking sectors in the world, which makes sense given the country’s demographics and the increasing demand for Shariah-compliant financial products.
Meezan Bank is Pakistan’s first and largest dedicated Islamic bank, operating entirely on Islamic principles across all its products. It is also consistently one of the highest-rated banks in the country for customer satisfaction.
Beyond Meezan, most conventional banks in Pakistan operate dedicated Islamic banking windows or subsidiaries. HBL Islamic, UBL Ameen, MCB Islamic, Bank Alfalah Islamic, and Allied Bank Islamic are among the well-known options. These windows operate under separate Shariah boards and maintain separate pools of funds from their conventional banking operations, at least according to their stated structures.
The State Bank of Pakistan actively supports and regulates Islamic banking, and the sector has grown consistently over the past two decades. As of recent years, Islamic banking accounts for a significant and growing share of Pakistan’s overall banking assets.
Conventional Banking: How It Operates
In a conventional bank, everything is interest-based. When you deposit money in a savings account, the bank pays you a predetermined interest rate. When you take a loan, you pay a predetermined interest rate on the outstanding balance. The bank profits from the difference between what it pays depositors and what it charges borrowers.
Conventional banking is straightforward in its mechanics and is the dominant model globally. It is efficient, widely understood, and deeply embedded in international financial systems.
For people who do not have religious objections to interest-based finance, conventional banking offers a familiar, predictable set of products. Fixed deposit rates are exactly what they say, loan repayments are calculated on clear amortization schedules, and there is no ambiguity about what you are getting.
Practical Comparison: What Actually Differs Day to Day?
This is the question most people really want answered. If you open an Islamic savings account versus a conventional savings account at the same bank, how different is your day-to-day experience?
Honestly, for most routine banking activities, the experience is very similar. You deposit money, you receive a return on your balance, you get a debit card, you use mobile banking, you pay bills. The interface and the banking relationship feel almost identical.
The differences show up in specific areas.
Returns on savings accounts
Conventional savings accounts pay a fixed interest rate declared upfront, aligned to the SBP policy rate floor. Islamic savings accounts pay a profit share that is declared periodically based on the bank’s actual earnings from its Shariah-compliant pool. In practice, the rates are often very close to each other and Islamic accounts have at times offered slightly higher returns, though this varies and is not guaranteed.
Financing products
This is where the differences are most meaningful. A conventional car loan and an Islamic Murabaha car financing product look similar on paper in terms of monthly installments, but their legal and religious structures are fundamentally different. If you take a conventional loan, you are paying interest. If you take a Murabaha arrangement, you are paying a deferred sale price. For many people, the practical outcome in terms of total payment is comparable, but the theological distinction is significant.
Shariah oversight
Every Islamic banking product in Pakistan must be approved by the bank’s Shariah supervisory board, which is a committee of qualified Islamic scholars. This board reviews products, transactions, and operations to ensure compliance. Conventional banks have no such oversight requirement.
Profit distribution timing
Conventional savings account interest is typically calculated daily and credited monthly. Islamic savings account profit is usually calculated and distributed monthly or quarterly based on the bank’s actual profit performance, which means there can occasionally be slight variations in timing and amount.
Read more: Risk and Return in Investing: What Every Beginner Must Know
Common Misconceptions Worth Clearing Up
“Islamic banking is just conventional banking with different names.”
This is the most common criticism, and it has some basis when applied to poorly structured Islamic products. There are genuine cases where the economic outcome of an Islamic product and its conventional equivalent are nearly identical, leading critics to question whether the distinction is meaningful.
However, structurally and legally, the contracts are different. A Murabaha sale is not the same legal instrument as an interest-bearing loan, even if the total payments end up similar. Whether that structural difference satisfies one’s personal religious standard is ultimately an individual judgment.
“Islamic banking returns are always lower.”
Not true. Profit rates on Islamic savings accounts in Pakistan have historically been competitive with conventional savings rates, and in some periods have exceeded them.
“Islamic banks never lose money.”
Islamic banking is based on profit and loss sharing, which theoretically means depositors can share in losses too. In practice, fully Islamic retail banks like Meezan have maintained strong performance, but the theoretical loss-sharing element is real and is part of what distinguishes the model philosophically.
“Only religious people should use Islamic banking.”
Many non-Muslims globally use Islamic banking products, not for religious reasons but because the asset-backed, equity-linked nature of Islamic finance can offer different risk characteristics. In Pakistan, some customers choose Islamic banking purely on financial grounds.
How to Decide Which One is Right for You
If you have religious concerns about riba and want to avoid interest-based finance, Islamic banking is clearly the appropriate choice. Pakistan has enough well-established Islamic banks and windows that you do not have to compromise on product range or accessibility to bank Islamically.
If you do not have religious objections and are choosing purely on financial and practical grounds, both systems offer comparable products in the Pakistani market. The difference in day-to-day experience is minimal. Your decision might come down to which bank has the better branch network in your area, the better mobile app, or the more competitive returns.
If you are somewhere in between, still figuring out your own position on the question, it is worth doing a bit more reading and perhaps consulting a scholar you trust. This article can explain the mechanics but the religious dimension is a personal matter.
Key Takeaways
Islamic banking and conventional banking serve the same fundamental purpose: keeping your money safe, helping it grow, and giving you access to financing when you need it. The difference lies in the principles and contracts underlying every transaction.
In Pakistan, you are fortunate to have a genuinely developed Islamic banking sector with competitive products and strong regulatory oversight. The choice between Islamic and conventional banking is not a compromise either way. Both systems are capable of meeting your financial needs. The question is which set of principles aligns better with your values and circumstances.
Understanding the difference, as you now do, puts you in a much better position to make that choice deliberately rather than just picking whatever the bank officer suggests.

Islamic banking is really looting Pakistan. A wolf in sheep’s clothing.