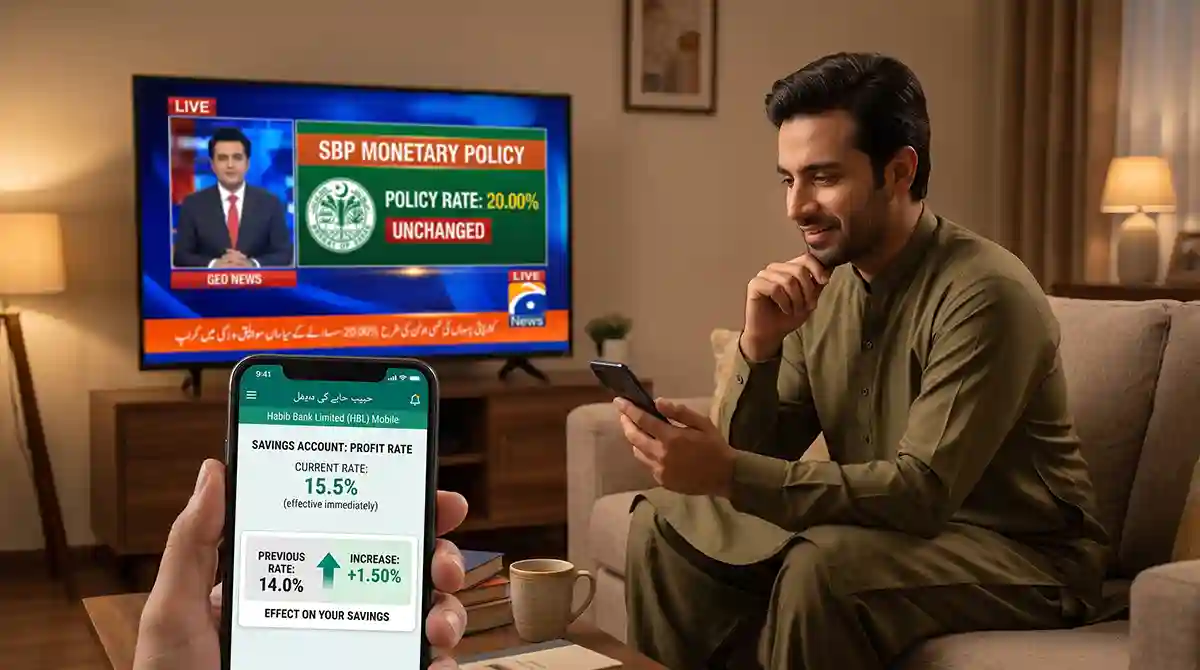
Every few weeks, Pakistani news channels run a segment announcing that the State Bank of Pakistan has “kept the policy rate unchanged at 11.5 percent” or “cut the rate by 100 basis points,” delivered in the same flat tone as a cricket score update, and most viewers change the channel without absorbing what it actually means for them. Yet this single number, set roughly eight times a year by SBP’s Monetary Policy Committee, is arguably the most consequential figure in Pakistani personal finance: it is the anchor from which your savings account profit rate, your car loan markup, your home financing installment, and your fixed deposit return are all, directly or indirectly, calculated. Here you will analyze how SBP’s monetary policy actually affects your bank account.
This article traces that connection step by step, using Pakistan’s actual rate path through 2026 as a live worked example, so the next time you hear an MPC announcement on the news, you understand exactly what it means for your own account.
Table of Contents
What the Policy Rate Actually Is
Before I explain about How SBP’s monetary policy actually affects your bank account in 2026, you need to know what the policy rate actually is. The State Bank of Pakistan is legally mandated, under Section 4B of the SBP Act 1956, to achieve and maintain domestic price stability, which SBP has defined as keeping inflation low and stable within a medium-term target range of 5 to 7 percent. The policy rate is SBP’s primary tool for pursuing that mandate. It is the rate at which SBP itself is willing to lend to and borrow from commercial banks through its standing facilities, and SBP’s own interest rate corridor sets the ceiling (the rate at which banks can borrow from SBP, called the repo rate) 100 basis points above the policy rate, and the floor (the rate at which banks can park excess funds with SBP, called the reverse repo rate) 100 basis points below it.
This corridor structure means the policy rate is not a suggestion; it is the literal price of money between banks and the central bank, and every commercial bank in Pakistan prices its own lending and deposit products with direct reference to it.
The Transmission Chain: How One Number Becomes Your Savings Rate and Your Loan Payment
Step 1: SBP sets the policy rate. Pakistan’s Monetary Policy Committee meets roughly eight times per fiscal year on a pre-published calendar, reviewing inflation data, exchange rate pressure, global commodity prices, and economic growth before announcing its decision.
Step 2: KIBOR follows. The Karachi Interbank Offered Rate, calculated and published daily by the Financial Markets Association of Pakistan for tenors ranging from overnight to one year, is the rate at which banks lend to each other in the interbank market. KIBOR moves in close alignment with the policy rate and its expected future trajectory, since banks are constantly repricing their own interbank borrowing costs against SBP’s stated stance.
Step 3: Your bank products are priced off KIBOR. As covered in the car financing, home financing, and personal loan articles in this series, most variable-rate consumer lending in Pakistan is structured as KIBOR plus a bank spread, typically 2 to 4 percentage points depending on the product and your risk profile. Your savings account profit rate and fixed deposit rates similarly track this same underlying benchmark, adjusted by each bank’s own margin.
A worked example of the full chain: if SBP’s policy rate is 11.5 percent and 1-year KIBOR is trading at 12.08 percent (its actual level in June 2026 following an SBP pause), a car loan priced at KIBOR plus a 2.5 percent spread would carry a markup of roughly 14.6 percent. A savings account paying, say, KIBOR minus 2 percent would yield depositors around 10 percent. When SBP moves the policy rate, this entire chain shifts within days to weeks, not months, which is why a single MPC announcement genuinely does reach your own bank statement.
Pakistan’s Actual 2026 Rate Path: A Live Case Study
Rather than a hypothetical, here is what genuinely happened in 2026, and it is a useful illustration of how quickly the transmission chain can move in both directions.
| Period | Policy Rate | What Was Happening |
|---|---|---|
| June 2023 (peak) | 22.00% | Record high amid severe inflation, part of an aggressive 2021–2023 tightening cycle |
| End 2024 | 13.00% | Aggressive easing cycle as inflation fell sharply |
| End 2025 | 11.00% | Continued gradual cuts |
| March 9, 2026 | 10.50% | Cutting cycle paused; cumulative cuts of 1,150 basis points in under two years |
| By July 27, 2026 | 11.50% | Rate had risen again; MPC cited an escalating Middle East conflict disrupting global fuel supplies, raising freight and insurance costs, and closing the Strait of Hormuz |
The July 2026 pause at 11.50 percent was described by policymakers as reflecting an “improving macroeconomic outlook” even as the rate sat above its March level, with headline inflation easing to 11.1 percent in June from 11.7 percent in May, driven by lower global energy prices and favorable electricity tariff adjustments.
What this meant practically for an ordinary depositor and borrower during this exact window: anyone who had booked a fixed-rate car or home loan in early 2025, near the bottom of the cutting cycle, was insulated from the subsequent rise. Anyone on a floating-rate facility, as covered in the car financing article in this series where installments reset annually based on prevailing KIBOR, saw their next reset land at a meaningfully higher rate than they might have expected based on the cutting trend of the prior two years. Savers, meanwhile, actually benefited from this same reversal: fixed deposit and National Savings rates, which had been drifting down through 2024 and 2025, stabilized and in some cases ticked back up as the underlying benchmark rose.
The Real Interest Rate: The Number That Actually Tells You Whether You’re Winning or Losing
This is the concept most Pakistani savers never apply, and it is more important than the nominal rate on its own. Your real interest rate is your nominal rate minus the prevailing inflation rate, and it tells you whether your savings are genuinely growing in purchasing power or merely appearing to grow in rupee terms while quietly losing ground, exactly as covered in the inflation-beating strategies article in this series.
Worked example using 2026’s actual numbers: with the SBP policy rate at 11.5 percent and CPI inflation at 11.1 percent in June 2026, the real interest rate on a typical bank product tracking close to the policy rate was only marginally positive, around 0.4 percentage points. Compare this to 2022, when inflation reached 27 percent while the policy rate stood at 16 percent, producing a real interest rate of roughly negative 11 percent, meaning cash sitting in a savings account that year was losing real purchasing power rapidly despite showing a positive nominal return every month.
This is precisely why the same nominal savings rate can be a genuinely good outcome in one year and a genuinely bad one in another, depending entirely on where inflation sits alongside it.
What Rising vs Falling Rates Actually Mean for You, Practically
| Environment | Good News For | Bad News For | Practical Move to Consider |
|---|---|---|---|
| Rates rising (like early-mid 2026) | Savers with new fixed deposits/National Savings; anyone about to lock in a term deposit | Anyone with a floating-rate loan approaching its annual reset (as covered in the car and home financing articles) | Lock in longer-tenor fixed deposits or National Savings certificates while rates are elevated, as covered in the fixed deposits article in this series |
| Rates falling (like 2024–2025) | Borrowers with floating-rate loans; new borrowers entering the market | Savers whose fixed deposits are maturing into a lower-rate environment | Consider fixed-rate loan options if available, as covered in the car financing article; ladder fixed deposit maturities rather than locking everything into one date |
| Rates paused/uncertain (like SBP’s July 2026 stance) | No clear directional advantage either way | No clear directional disadvantage either way | Maintain a diversified mix across the time horizons covered in the passive income portfolio article, rather than betting heavily on a single rate direction |
Common Mistakes Pakistanis Make With This Information
Only paying attention to whether their own specific loan or deposit rate changed, without understanding why. As shown above, your bank’s specific product rate is a direct, mechanical downstream consequence of the SBP decision and KIBOR movement; understanding the chain lets you anticipate changes rather than being surprised by them at your next installment or maturity date.
Comparing nominal rates across years without adjusting for inflation. A savings account paying 11 percent in a year when inflation is 7 percent is a meaningfully better real outcome than the same 11 percent in a year when inflation is 15 percent, exactly the distinction the real interest rate calculation above makes clear.
Assuming a rate cutting cycle will continue indefinitely, or a hiking cycle will reverse quickly. Pakistan’s actual 2026 path, a pause, followed by a rise driven by an unrelated geopolitical shock, shows how quickly the trajectory itself can change based on events with no connection to Pakistan’s domestic economy.
Not checking whether a specific loan or deposit product is fixed-rate or floating-rate before assuming how a policy change affects it. As covered in the car and home financing articles in this series, a fixed-rate facility is genuinely insulated from subsequent policy moves for its full tenor, while a floating-rate facility resets, typically annually, to reflect the prevailing benchmark at that time.
Conclusion
SBP’s policy rate announcements are not background noise on the evening news; they are the mechanical origin point for the specific numbers on your own bank statement, your own loan installment, and your own savings account profit credit. Understanding the transmission chain, from the policy rate to KIBOR to your bank’s own priced products, and applying the real interest rate lens rather than the nominal rate alone, turns an abstract macroeconomic headline into a genuinely useful piece of personal financial planning information.
The next time an MPC announcement runs across the bottom of the screen, you now know exactly what to check: where KIBOR is likely to move as a result, whether your own loans and deposits are fixed or floating, and what the resulting real interest rate on your savings actually works out to once current inflation is subtracted.
Further reading and official sources:
- State Bank of Pakistan: Monetary Policy Statements and MPC meeting calendar: sbp.org.pk
- Financial Markets Association of Pakistan: daily KIBOR rates: fmap.com.pk
- Pakistan Bureau of Statistics: monthly CPI inflation data: pbs.gov.pk