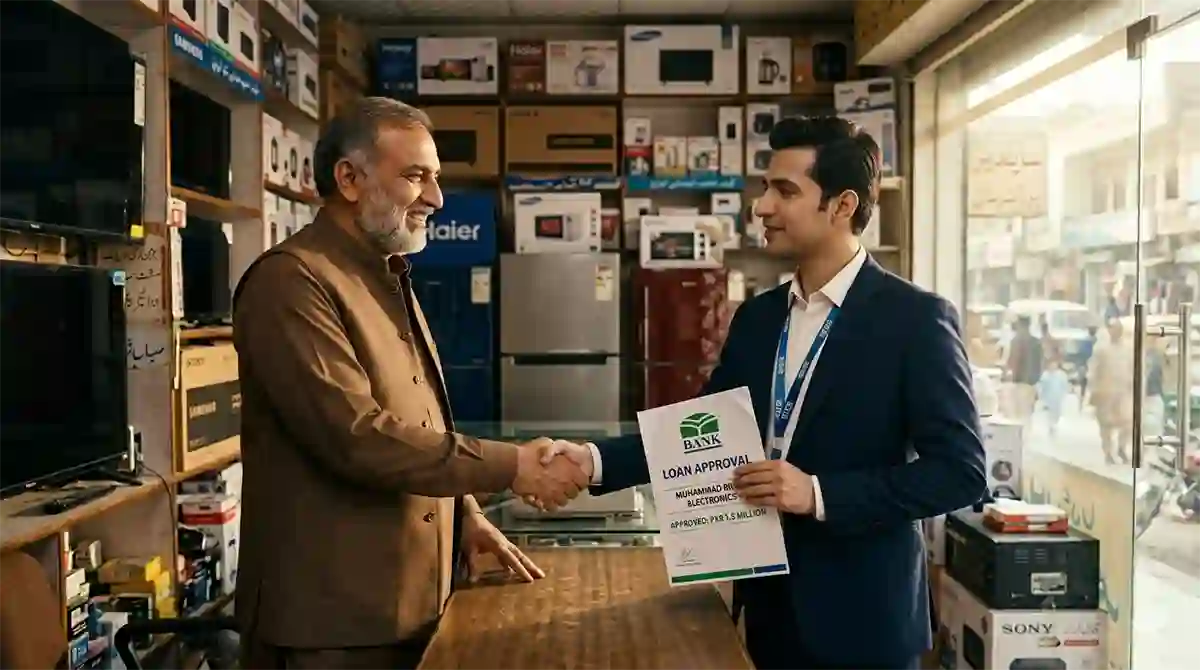
A shopkeeper I know in Lahore wanted to expand his small electronics shop into the empty unit next door. He had been running the business successfully for six years, had loyal customers, and the opportunity made complete sense. What he did not have was the PKR 800,000 needed to renovate the space and stock additional inventory.
He assumed getting a business loan in Pakistan would be nearly impossible without connections or collateral worth millions. He had heard stories from other shopkeepers about endless paperwork, rejected applications, and banks that only wanted to lend to large companies. So he gave up on the idea before even trying.
Two years later, almost by accident, he learned about a government-backed SME financing scheme through a conversation at a trade association meeting. He applied, was approved within a few weeks, and expanded his shop. The opportunity had been sitting there the entire time. He simply did not know it existed or how to access it.
This story repeats itself across Pakistan constantly. Getting a business loan in Pakistan is genuinely more accessible than most small business owners assume, but the information about how to actually do it is scattered, inconsistent, and rarely explained in a way that a first-time applicant can follow.
This guide brings it together.
Table of Contents
Understanding Your Financing Options
To get a business loan in Pakistan, you first you need to understand a few things. Before applying for anything, it helps to understand the landscape of business financing available in Pakistan. Not all loans are created equal, and the right option depends heavily on your business size, your stage of growth, and what you need the money for.
Conventional Bank SME Loans
Commercial banks in Pakistan including HBL, UBL, MCB, Bank Alfalah, and others offer dedicated SME financing products. These are typically the largest source of formal business financing and cover everything from working capital loans to term loans for equipment and expansion.
Government-Backed SME Schemes
The State Bank of Pakistan, in coordination with the federal government, runs several refinance and credit guarantee schemes that make financing more affordable and accessible for small businesses. These schemes work by having SBP provide funds to commercial banks at very low or zero rates, with the banks then lending to qualifying SMEs at significantly reduced markup rates compared to standard commercial lending. The government also often provides credit guarantees that cover a portion of the loan if the borrower defaults, which makes banks more willing to lend to smaller and newer businesses than they otherwise would be.
Microfinance Institutions
For very small businesses and entrepreneurs who may not meet the documentation or collateral requirements of commercial banks, microfinance banks and institutions such as Akhuwat, FINCA Microfinance Bank, and Khushhali Microfinance Bank offer smaller loan amounts with simplified processes, often without requiring traditional collateral.
Islamic Financing
For business owners who want Shariah-compliant financing, Islamic banks and Islamic banking windows of conventional banks offer equivalent products structured through Murabaha, Ijarah, or Diminishing Musharakah arrangements rather than conventional interest-based loans.
The Prime Minister’s Youth Business and Agriculture Loan Scheme
This is one of the most significant government-backed financing programs available to small business owners and young entrepreneurs in Pakistan, and it deserves detailed attention because it has gone through some changes worth understanding.
The scheme was originally launched as the Prime Minister’s Kamyab Jawan Youth Entrepreneurship Scheme. It has since been restructured and is now operating as the Prime Minister’s Youth Business and Agriculture Loan Scheme, often referred to as PMYB&ALS, with the program currently in its Phase III as part of an ongoing government collaboration with the State Bank of Pakistan.
Who Is Eligible
The scheme is available to Pakistani citizens holding a valid CNIC, generally aged between 21 and 45 years, with entrepreneurial potential. For businesses in the IT and e-commerce space, the lower age limit drops to 18 years, with a minimum educational requirement of matriculation or equivalent. For businesses structured as partnerships or companies rather than sole proprietorships, at least one of the owners, partners, or directors must fall within the prescribed age bracket.
How the Loan Tiers Work
The scheme is structured into tiers based on loan size, each with its own requirements.
The first tier covers smaller loans, generally up to around PKR 1 million, and is designed for very small businesses and startups. These loans often require only a personal guarantee from the borrower rather than significant collateral, making them accessible to entrepreneurs without substantial assets.
The second and third tiers cover larger financing amounts, up to several million rupees, and are intended for more established small and medium enterprises looking to expand. These tiers typically require collateral and follow the bank’s standard credit policy more closely, though still benefit from the government’s subsidized markup rates and credit guarantees.
What the Loans Can Be Used For
Financing under this scheme covers both term loans for fixed asset purchases, such as machinery and locally manufactured vehicles for commercial use, and working capital loans to support day-to-day business operations. Vehicle financing typically allows only one vehicle per borrower, with some exceptions for specific business types like food franchise and distribution businesses.
Loan Tenor and Terms
Loans under this scheme generally have a tenor of up to eight years, including a grace period of up to one year before repayment begins. Working capital loans often have an initial one-year tenor with the possibility of annual rollover for several additional years, subject to satisfactory repayment behavior.
How to Apply
Applications can be made through the official PMYP portal, or directly through any of the participating banks, which include the National Bank of Pakistan, Bank of Punjab, Bank of Khyber, and numerous other commercial and Islamic banks across the country. The application forms are designed to be simple, available in both English and Urdu, and processing time is generally targeted to be completed within a reasonable timeframe as specified by each bank.
SBP Refinance and Credit Guarantee Scheme for Women Entrepreneurs
If you are a woman entrepreneur in Pakistan, there is a specific and genuinely favorable financing scheme worth knowing about.
The State Bank of Pakistan, as part of its Banking on Equality initiative, launched a refinance and credit guarantee scheme specifically for women entrepreneurs and women-owned small and medium enterprises. Under this scheme, SBP provides refinancing to participating banks at 0%, with up to 60% risk coverage, allowing the banks to extend financing to women entrepreneurs at a significantly subsidized markup rate of up to 5% per annum.
The maximum financing amount available under this scheme is PKR 5 million, with a maximum tenor of up to 5 years including any grace period. Financing is generally available against the personal guarantee of the borrower, which removes a major barrier that many women entrepreneurs face when they lack property or assets to offer as traditional collateral.
This scheme is available through numerous participating banks including Allied Bank, Bank Alfalah, HabibMetro, and others, with Shariah-compliant versions also available for those seeking Islamic financing.
If you are a woman running or planning to start a business in Pakistan, this scheme represents one of the most accessible and affordable financing options currently available, and it is significantly underutilized relative to how beneficial its terms actually are.
What Banks Actually Look For
Regardless of which scheme or loan product you apply for, banks evaluate applications based on a consistent set of factors. Understanding these helps you prepare a stronger application and anticipate what documentation you will need.
Business Registration and Documentation
Having your business properly registered, whether as a sole proprietorship with an NTN or as a formally registered company with SECP, is typically a baseline requirement. Banks want to see that your business has a formal legal identity and tax registration.
Financial Records
This is where many small businesses struggle, and it is also where the financial management practices discussed in an earlier article in this series become directly relevant. Banks will ask for bank statements covering recent months, often six to twelve months, to assess your business’s cash flow patterns. They may also ask for basic financial statements if your business maintains them.
A business with a dedicated bank account, clean transaction history, and some basic financial records is in a dramatically stronger position than a business that cannot demonstrate any formal financial activity, even if both businesses are equally profitable in reality.
Credit History
As covered in detail in the Banking section of this site, your personal and business credit history through the Electronic Credit Information Bureau plays a significant role in loan approval. A clean repayment history on any previous credit facilities, including credit cards and past loans, strengthens your application considerably. A history of defaults or missed payments can lead to rejection regardless of how strong your business case is.
Collateral
For larger loan amounts, banks typically require collateral, which could be property, vehicles, or other assets that the bank can claim if the loan is not repaid. Smaller loans, particularly under government-backed schemes for startups and women entrepreneurs, often require only a personal guarantee rather than physical collateral, which is a significant advantage for entrepreneurs who are asset-light.
Business Viability
Banks want to understand what your business does, who your customers are, and whether the business model makes sense. This is where having a written business plan, as covered in a previous article, becomes genuinely useful. A clear, realistic explanation of your business, your revenue, your costs, and how the loan will be used demonstrates to the bank that you have thought through your plans seriously.
Equity Contribution
For many financing schemes, particularly under the youth loan program, the borrower is required to contribute a portion of the project cost themselves, either in cash or through immovable property, after the loan is approved. This requirement, sometimes called the debt to equity ratio, varies by tier and scheme but generally demonstrates that the borrower has some personal stake in the success of the business beyond the borrowed funds.
Step-by-Step: How to Apply for a Business Loan in Pakistan
Step 1: Get your documentation in order first
Before approaching any bank, make sure you have your NTN registration, business registration documents if applicable, CNIC, bank statements for the past six to twelve months, and any existing financial records. If your finances have been disorganized, take the time to put together at least a basic summary of your revenue and expenses before applying. This preparation alone significantly improves your chances.
Step 2: Identify the right scheme or product for your situation
Based on your business size, your gender, your industry, and your financing needs, identify whether a government-backed scheme like PMYB&ALS or the women entrepreneurs refinance scheme applies to you, or whether a standard conventional SME loan is more appropriate. Visit the websites of two or three banks that are active in SME lending and compare their specific SME product offerings.
Step 3: Visit the bank and discuss your requirements
Visit the SME or business banking desk of your chosen bank and explain your business and your financing needs. Bank relationship officers can guide you toward the specific product that fits your situation and tell you exactly what documentation they require. Do not hesitate to visit more than one bank to compare terms, processing times, and the responsiveness of the staff.
Step 4: Complete the application
Fill out the application form completely and accurately. Attach all required documents. If you are applying under a government scheme, make sure you meet the specific eligibility criteria for that scheme, including age requirements where applicable.
Step 5: Respond promptly to any follow-up requests
Banks often request additional documentation or clarification during the review process. Responding quickly and completely to these requests keeps your application moving and demonstrates that you are organized and serious.
Step 6: Understand the terms before signing
Once approved, carefully review the loan agreement, including the markup rate, repayment schedule, any fees, and the consequences of late or missed payments. If anything is unclear, ask the bank to explain it before signing. This is not the moment to skip reading the fine print.
Common Reasons Business Loan Applications Get Rejected
Lack of formal documentation. A business with no NTN, no business bank account, and no financial records is very difficult for any bank to assess, regardless of how well the business is actually performing.
Poor personal credit history. Past defaults, missed credit card payments, or unresolved loan issues on your ECIB report can lead to rejection even when your current business is doing well.
Unclear use of funds. Applications that cannot clearly explain what the loan will be used for and how it will generate the cash flow needed to repay it raise red flags for lenders.
Insufficient equity contribution or collateral. For schemes and loan amounts that require a borrower contribution or collateral, not having this ready can stall or sink an application.
Mismatched business stage and loan size. Requesting a large loan for a business with minimal operating history or revenue can be seen as disproportionate risk by the lender. Matching your loan request to your business’s actual current stage improves credibility.
Learn more: How to Manage Business Finances: A Guide for Small Business Owners in Pakistan
A Few Honest Tips From Watching This Process Play Out
Apply when your business is doing reasonably well, not when you are desperate. Banks are more willing to lend to businesses that demonstrate stability and growth potential, not to businesses in crisis looking for a rescue.
Build a relationship with your bank before you need a loan. A business that has maintained an active account with consistent activity for a year or two is in a much stronger position than one that walks in cold asking for financing.
Do not assume government schemes are only for new businesses or only for very specific sectors. Many existing businesses qualify for expansion financing under these programs, and the eligibility criteria are often broader than business owners assume.
Ask about all available schemes explicitly. Bank staff handle many products and may not always proactively mention every scheme you could qualify for. If you fall into a category like women entrepreneurs, youth, or a specific sector, ask directly whether there is a subsidized scheme that applies to you.
Summing up
Getting a business loan in Pakistan is not the closed door that many small business owners assume it to be. Between conventional SME financing, government-backed schemes with subsidized rates and credit guarantees, and specific programs for women entrepreneurs and youth, there are genuine pathways to financing for businesses at almost every stage.
What makes the difference between an approved application and a rejected one is rarely the underlying quality of the business. It is almost always preparation: having your documentation organized, your finances in order, a clear understanding of what you are asking for and why, and knowledge of which specific scheme actually fits your situation.
The shopkeeper in Lahore did not need connections or hidden influence to expand his business. He needed information that was sitting in plain sight the whole time. If you have been hesitant to explore business financing because it feels complicated or out of reach, take the first step. Walk into a bank, ask about SME financing options, and see what happens. The opportunity might be more accessible than you think.