Calculate your Compound Interest
Project your wealth growth with regular contributions and compounding
| Year | Total Deposits | Total Interest | Ending Balance |
|---|
Building long-term wealth does not require complicated math. This compound interest calculator shows you exactly how your money grows when you combine an initial deposit with regular monthly contributions and compound returns.
Follow these simple steps to map out your investment plan:
- Select Your Currency: Toggle between USD ($) and PKR (Rs) at the top right of the calculator.
- Enter Your Initial Investment: Type in the starting amount you plan to invest today. If you are starting from zero, set this field to 0.
- Add Your Monthly Contribution: Enter the fixed amount you plan to add to your portfolio every month.
- Set Your Annual Interest Rate: Input your expected annual rate of return. For example, global stock index funds historically average 8% to 10% per year, while Pakistani money market funds or savings certificates often yield between 12% and 16%.
- Choose Your Time Horizon and Frequency: Enter the number of years you plan to stay invested and select how often your returns are compounded (monthly is the standard for most savings and investment accounts).
Once entered, the calculator updates immediately. You can also click View Year-by-Year Breakdown Table at the bottom of the tool to inspect your exact balance at the end of every single year.
What is Compound Interest and How Does It Work?
Simple interest only pays you returns on your original deposit. Compound interest, on the other hand, pays you returns on your original deposit plus all the interest you have accumulated in previous periods. In short, your money starts earning money of its own.
During the first few years of an investment, compound growth looks slow and steady. However, once your accumulated profit becomes larger than your initial deposit, the growth curve bends upward sharply. Financial analysts call this the snowball effect: the longer your money rolls down the hill, the faster it picks up size and momentum.
The Compound Interest Formula
When you include regular monthly deposits, our calculator processes your balance month by month using the standard compound growth equation:
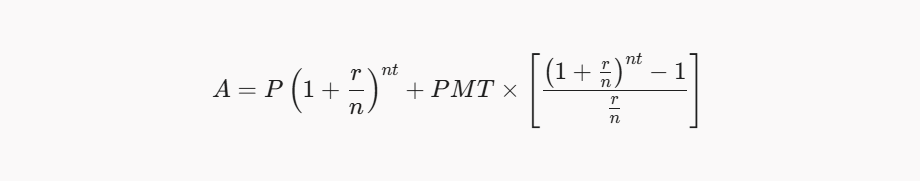
Where:
- A is the future value of your investment, including interest.
- P is your initial principal balance.
- PMT is your regular monthly contribution.
- r is the annual interest rate (in decimal form).
- n is the number of compounding periods per year.
- t is the total time your money is invested in years.
Real-World Examples: USD vs. PKR Scenarios
Seeing the numbers side by side highlights why starting early matters far more than starting with a huge sum of money.
| Scenario | Starting Principal | Monthly Addition | Annual Return | Time Horizon | Total Invested | Total Profit Earned | Final Balance |
| USD Growth Portfolio | $5,000 | $250 | 10% | 15 Years | $50,000 | $74,316 | $124,316 |
| PKR Wealth Plan | Rs 500,000 | Rs 25,000 | 14% | 15 Years | Rs 5,000,000 | Rs 14,297,118 | Rs 19,297,118 |
Notice how in both scenarios, the Total Profit Earned overtakes the Total Invested capital. By year 15, your accumulated returns are doing more work than your monthly out-of-pocket contributions.
3 Practical Levers to Maximize Your Compound Returns
1. Give Your Money More Time Time is the single heaviest variable in the compounding formula because it sits in the exponent. Investing for 20 years instead of 10 years does not just double your profit; at a 10% annual return, it nearly triples or quadruples your final balance.
2. Automate Monthly Contributions Waiting until you have a large lump sum delays your compounding clock. Contributing a smaller, consistent amount every single month buys you time in the market and steadily expands the base on which future interest is calculated.
3. Reinvest All Dividends and Profits Compounding only works if the profits stay inside the account. If you withdraw your annual dividends or profit payouts to spend them, you reset your growth back to simple interest. Always choose the automatic dividend reinvestment option in your brokerage or mutual fund account.
FAQs
What is the Rule of 72 in compound interest?
The Rule of 72 is a quick mental shortcut to estimate how long it takes to double your money without additional contributions. Divide 72 by your annual rate of return. For example, at a 9% annual return, your initial investment will double in roughly 8 years (72 / 9 = 8). At 12%, it doubles in 6 years.
Does compounding frequency really make a big difference?
Moving from annual compounding to monthly compounding gives your final balance a noticeable boost because your earned interest starts generating its own returns eleven months earlier each year. Moving from monthly to daily compounding, however, produces only a very small difference.
Which investments actually pay compound interest?
High-yield savings accounts, money market funds, Islamic cash funds, and fixed term deposits compound directly through periodic profit payouts. Stock market investments and ETFs compound through capital appreciation and reinvested dividends.