
Pakistan’s recent inflation history is one of the most dramatic in the world. Consumer price inflation peaked at 38 percent year on year in May 2023, dropped to a 60-year low of 0.7 percent in March 2025, then rebounded to approximately 12 percent in mid-2026 as energy and food prices climbed again. These swings have been genuinely extraordinary, and they have had a real and lasting impact on Pakistani households whose savings sat in bank accounts, prize bonds, or cash throughout this period. So learning the inflation-beating investment strategies for Pakistani investors is very important.
The quiet destruction of purchasing power during high inflation periods is not theoretical. If you held PKR 1,000,000 in a savings account earning 8 percent annually during the 38 percent inflation of 2023, you lost 30 percent of your purchasing power in a single year. The balance looked unchanged on paper, but what it could buy had shrunk dramatically. This is the core problem that inflation-beating investment is designed to solve.
Beating inflation in Pakistan requires a fundamentally different approach from simply finding the highest-yielding deposit product. It requires understanding which asset classes have historically generated real returns above Pakistan’s inflation rate, across different phases of the inflation cycle, and building a portfolio that maintains its purchasing power over time rather than just its nominal balance.
This guide covers the strategies that have actually worked.
Table of Contents
The Real Return Framework: The Only Number That Matters
Before I explain the Inflation-Beating Investment Strategies for Pakistani Investors in 2026, you need to know the real return framework. Before covering specific strategies, understanding the concept of real returns is essential because it is the only framework that genuinely tells you whether your money is growing or shrinking.
Your real return is your nominal return minus the inflation rate. A savings account earning 12 percent annually when inflation is 12 percent delivers a real return of exactly zero. Your nominal balance has grown but you cannot buy anything more with it than you could at the start of the year.
A portfolio earning 15 percent annually when inflation is 12 percent delivers a positive real return of approximately 3 percent. Your purchasing power is genuinely growing.
An investment earning 8 percent annually when inflation is 12 percent, regardless of how safe or government-backed it appears, is delivering a negative real return of approximately 4 percent annually. You are losing purchasing power in real terms even as your account balance grows.
This framework immediately reframes how you should evaluate every investment option in Pakistan. The question is never just “what is the return?” It is always “what is the real return after accounting for current inflation?”
At Pakistan’s current mid-2026 inflation rate of approximately 12 percent, any investment delivering less than 12 percent nominal returns is negative in real terms. National Savings Short Term Savings Certificates at 10.84 percent are underwater in real terms at current inflation. Fixed deposits at 12 to 14 percent are just barely positive in real terms. Government securities at 10 to 13 percent are negative to flat in real terms. Understanding which investments are genuinely growing your purchasing power versus just maintaining the illusion of growth is the most important analytical move a Pakistani investor can make.
Strategy 1: Equities for Long-Run Inflation Beating
The Pakistan Stock Exchange has been the strongest inflation-beating asset class over long periods, and the recent performance data is striking. The PSX delivered nearly 50 percent returns in calendar year 2025, following returns of 84 percent in 2024 and 55 percent in 2023. Even adjusting these extraordinary recent numbers for their extraordinary context, the KSE-100’s long-run compounded returns of 15 to 20 percent annually in PKR terms have consistently beaten Pakistan’s long-run inflation rate.
Why do stocks beat inflation over time? The mechanism is straightforward. Companies with pricing power can raise their prices alongside inflation, protecting the real value of their revenues. A bank that charges higher interest rates when rates are high earns more. A fertilizer company that sells a product farmers must buy regardless of price can pass through input cost increases. A cement company that benefits from infrastructure spending maintains earnings even as material costs rise. These businesses are not passive holders of fixed rupee claims. They are active economic participants who adapt to inflationary environments in ways that preserve and often grow their real earnings.
The critical caveat is that equities only beat inflation reliably over long time horizons of five to ten years or more. In the short run, stocks can fall dramatically even in inflationary environments. The KSE-100 correction of 15 to 19 percent in Q1 2026 is a clear recent example. Equities are the right answer to long-run inflation beating but are the wrong answer to preserving purchasing power over twelve months.
For Pakistani investors building an inflation-beating equity position, the specific companies that have demonstrated pricing power and consistent earnings growth through multiple inflation cycles deserve priority consideration. Banks that benefit from higher interest rate environments during inflation peaks, fertilizer companies with locked-in gas feedstock pricing, energy companies with dollar-linked revenues, and consumer staples businesses with strong brand loyalty are the categories most proven at maintaining real value through Pakistan’s inflation history.
Dividend growth as a specific inflation strategy. A 12 percent dividend yield that grows 15 percent annually is not merely a 12 percent nominal return. After five years at 15 percent annual dividend growth, the yield on your original cost has compounded to approximately 24 percent annually, significantly outpacing any reasonable Pakistan inflation rate. Focusing specifically on companies with a history of consistently growing their dividend payments alongside their business is one of the most powerful long-run inflation-beating strategies available on PSX. Equities with strong dividend growth potential in Pakistan include HBL, MCB Bank, Engro Fertilizers, and Hub Power Company.
Strategy 2: Gold as Inflation and Currency Hedge
Gold has served Pakistani investors as an inflation and currency depreciation hedge for generations, and the data supports this cultural conviction. Gold in PKR terms reached approximately PKR 492,000 per tola in mid-2026, having risen approximately fivefold over five years as both international gold prices surged and the PKR weakened significantly against the dollar.
The dual hedge mechanism is what makes gold particularly valuable in Pakistan specifically. When international gold prices rise in dollar terms, PKR-denominated gold prices rise correspondingly. When the rupee weakens against the dollar, even flat dollar-priced gold becomes more expensive in PKR terms. Since Pakistan has experienced both phenomena simultaneously and persistently over the past decade, gold holders have been doubly protected against the two most significant wealth threats to Pakistani savers: global commodity inflation and domestic currency depreciation.
For investors, the most cost-efficient route to gold exposure in 2026 is the Meezan Gold Fund rather than physical jewelry. Physical jewelry carries making charges of 10 to 25 percent over the raw gold price that are immediately lost when you sell. The Meezan Gold Fund provides gold price exposure through a regulated mutual fund structure without storage risk, security concerns, or making charge losses, with a one-year return of approximately 26.71 percent and year-to-date return of approximately 32.66 percent as of mid-2026.
The recommended allocation framework for gold in a Pakistani inflation-beating portfolio is 10 to 20 percent of total investable assets, held as a portfolio anchor and hedge rather than as a primary return driver. Going significantly above 20 percent concentrates too much in an asset that generates no income and is subject to its own price cycles.
Strategy 3: Foreign Currency Exposure
Pakistan’s long-run rupee depreciation is not a new phenomenon. The PKR has weakened dramatically against the US dollar over every extended period in Pakistan’s recent history. Holding a portion of your savings in a strong foreign currency provides an automatic hedge against this structural risk.
The most accessible route to foreign currency exposure for domestic Pakistani investors in 2026 is a foreign currency savings account at a major Pakistani bank. Banks including Meezan Bank, Bank AL Habib, HBL, and others offer USD, GBP, and EUR denominated savings accounts to eligible domestic account holders with competitive profit rates.
For overseas Pakistanis, the Roshan Digital Account provides multi-currency holdings including the USD-denominated Naya Pakistan Certificate at approximately 8.25 percent annual return, which combines government credit quality with dollar denomination for a genuinely compelling risk-adjusted profile.
The Investor Portfolio Securities (IPS) account is a powerful but less widely known option for sophisticated investors. Available through SBP’s regulations, an IPS account allows investors to hold government securities directly in electronic form without going through a broker for every transaction. It provides direct access to Pakistan Investment Bonds and T-Bills at better rates than retail channels, and foreign currency denominated securities provide the same dual protection of government credit quality and currency stability.
However, foreign currency exposure in Pakistani bank accounts has limitations. The profit rates on foreign currency deposits are generally lower than on PKR deposits. There have been historical instances of restrictions on foreign currency withdrawals during economic crises. And large foreign currency holdings in domestic accounts require regulatory compliance awareness.
Strategy 4: Real Estate for Inflation Protection with Caveats
Real estate is the traditional inflation hedge for Pakistani families, and the mechanism is real: construction costs rise with inflation, meaning replacement value for existing properties increases. Rental income can be revised upward with living costs over time. And well-located urban property has historically appreciated in nominal terms across Pakistan’s various inflationary episodes.
Real estate earns both rental income and capital appreciation simultaneously. Your asset grows in value even as it pays you monthly. No savings account or government bond gives you that dual return structure.
However, the inflation-protection claim for real estate requires important caveats that the simplistic “property always goes up” narrative ignores.
Not every property automatically protects against inflation. A speculative file in an unproven housing society, a plot in a remote location with no infrastructure, or an overpriced apartment in a weak rental market can remain stuck in nominal terms even when general inflation is running at double digits. The hedge works best when the asset is genuinely well-located, legally clear, and backed by real demand.
Property in Pakistan is extremely illiquid. If you need to access capital quickly during an economic shock, selling property in weeks is often impossible. An inflation hedge you cannot access when you need it is less useful than it appears on paper.
The real returns from real estate need honest accounting. The commonly cited 10 to 20 percent long-term appreciation for Pakistani property looks strong in nominal terms, but after accounting for transaction costs of 5 to 10 percent on entry and exit, annual maintenance, property taxes, management costs, and periods of vacancy for rental properties, the net real return after inflation is often lower than a well-managed equity portfolio.
Real estate belongs in an inflation-beating portfolio but as a component rather than the entirety. REITs, as discussed in the real estate investment article in this series, provide a more accessible and liquid route to real estate-linked inflation protection for investors who do not have the capital or management capacity for direct property ownership.
Strategy 5: Inflation-Linked Fixed Income Positioning
Fixed income instruments in Pakistan are complex in the context of inflation because the right strategy depends heavily on where you are in the inflation cycle.
During periods of high inflation and high interest rates, such as Pakistan’s 2023 to 2024 peak period, locking in long-duration fixed income at high rates made sense because rates were expected to fall. An investor who purchased a 3-year National Savings Special Savings Certificate in mid-2023 at 17 percent was locking in exceptional real returns for three years at a time when the rate was expected to decline.
During periods of falling inflation and falling rates, like Pakistan’s trajectory through 2024 and early 2025, switching from long-duration fixed income to shorter-duration instruments made more sense because locking in at rates that were about to fall would be costly.
In 2026 with inflation at approximately 12 percent and policy rates declining from their peaks, the relevant question for fixed income is whether real returns from available instruments are positive or negative.
At mid-2026 rates, government securities yield approximately 10 to 13 percent, National Savings products yield 11 to 12.48 percent at the highest tiers, and bank term deposits run broadly 12 to 14 percent for one-year tenors. Against 12 percent inflation, most fixed income instruments are delivering flat to slightly positive real returns. This is meaningfully better than 2022 to 2023 when inflation was dramatically outrunning fixed income rates, but still not the strongly positive real returns that make fixed income a primary inflation-beating instrument.
The right role for fixed income in an inflation-beating portfolio is capital preservation and income stability, not real growth. It anchors the portfolio against equity volatility and provides predictable income, but equity is what actually beats inflation over the long term.
Floating rate instruments deserve specific mention. Variable Rate PIBs and Variable Rental Rate GIS (the floating rate Government Ijarah Sukuk) have their yields reset periodically based on prevailing benchmark rates. When inflation causes the SBP to raise rates, these instruments’ yields automatically adjust upward, providing better inflation protection than fixed-rate bonds whose real yield deteriorates as inflation rises. For investors with meaningful fixed income allocations, a portion in floating rate government instruments provides dynamic inflation adjustment that fixed rate certificates cannot.
Strategy 6: Investing in Pricing Power Companies
This is a stock-selection dimension of the equity strategy that deserves its own explicit treatment because it is one of the most practically powerful inflation-beating approaches available on PSX.
Companies differ dramatically in their ability to pass through higher input costs to their customers. This ability, called pricing power, determines whether a company’s real earnings are protected during inflationary periods or whether margins are compressed as costs rise faster than prices.
Companies with strong pricing power in the Pakistan market include banks, which benefit directly from rising rates rather than being hurt by them, fertilizer producers who supply an essential product farmers cannot do without regardless of price, consumer staples businesses with strong brand loyalty where customers continue buying despite price increases, and commodity-linked companies whose revenues are indexed to internationally traded commodity prices.
Companies with weak pricing power, who struggle to pass through cost increases, include consumer discretionary businesses where customers delay purchases when prices rise, companies competing in commodity product categories where price is the primary purchase driver, and businesses with high fixed costs and no pricing flexibility who see margins squeezed when input costs rise.
A specific screen that Chase Securities recommends for inflation-resistant PSX stocks is to look for businesses with strong brand loyalty, monopoly-like market positions, or commodity-linked revenues. These characteristics are the practical indicators of pricing power. Identifying PSX companies that score well on these factors and focusing your direct equity allocation on them, rather than on cyclically sensitive businesses, positions your portfolio to maintain real value through Pakistan’s inevitable future inflationary episodes.
Building an Inflation-Beating Portfolio for Different Time Horizons
The right inflation-beating strategy differs significantly based on your investment timeline.
Short-term horizon of one to two years
For money you need within two years, capital preservation is more important than beating inflation. The priority is minimizing the real loss rather than achieving real growth. The best options are high-rate term deposits at 13 to 14 percent and National Savings products at 11 to 12.48 percent, which deliver minimal positive real returns at current inflation. Accepting the small positive or flat real return is the right trade-off when you cannot afford to expose money you will need soon to equity volatility.
Medium-term horizon of three to seven years
For a three to seven year horizon, a balanced approach combining fixed income for stability and equity for real growth makes sense. A portfolio of 40 to 50 percent equity mutual funds or blue-chip PSX stocks, 30 to 40 percent in National Savings or term deposits, 10 to 15 percent gold, and 5 to 10 percent real estate through REITs provides meaningful inflation beating through the equity and gold components while the fixed income provides stability and income during equity market downturns.
Long-term horizon of seven years and beyond
For truly long-term wealth building, the evidence strongly favors maximum equity allocation within what you can maintain emotionally through market downturns. A 60 to 70 percent equity allocation, 10 to 15 percent gold, and the remainder in income-generating fixed instruments, over a ten to twenty year horizon in Pakistan’s market, has historically produced the strongest real returns of any accessible asset combination. Time is the single most powerful variable in favor of equity’s inflation-beating characteristics.
The Investor Mindset Most Pakistanis Need to Change
Many Pakistani investors believe that “playing it safe” through cash, gold, and fixed deposits protects their wealth. In reality, playing it safe in the way most Pakistanis understand it often guarantees a real loss.
The refusal to engage with equity risk does not eliminate risk. It simply shifts it into the silent, compounding danger of inflation. A household that has kept savings in a bank account for ten years at below-inflation rates has not preserved wealth. It has allowed inflation to transfer real value from their savings to everyone in the economy whose prices rose while their returns did not.
Decades of high inflation in Pakistan have quietly and systematically transferred wealth from savers who accepted below-inflation returns to borrowers, real asset owners, and equity investors whose returns tracked or exceeded inflation. This transfer is invisible in nominal terms but devastating in real ones.
The most important mindset shift for Pakistani investors is to measure investment performance in real terms, not nominal terms, and to accept that beating inflation over the long run requires tolerating the short-term volatility that comes with equity investment.
A Sample Inflation-Beating Portfolio for 2026
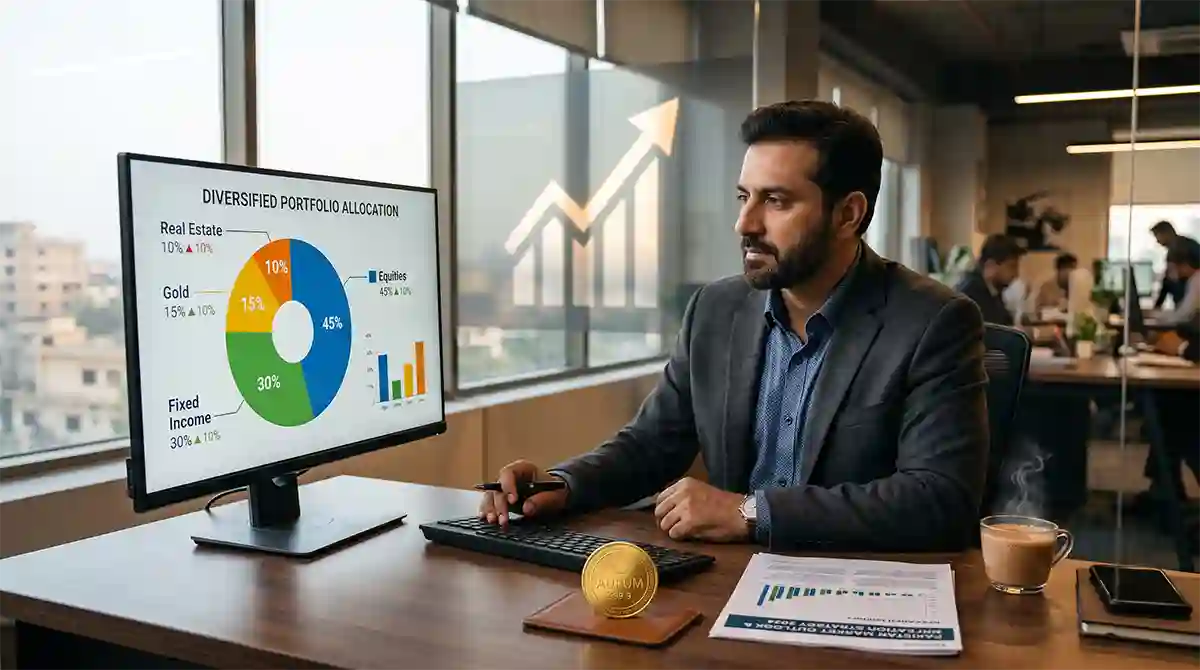
Based on the current macroeconomic environment in Pakistan, a practical moderate-risk inflation-beating portfolio for a working-age investor with a ten-year horizon might look like the following.
30 to 40 percent in equity mutual funds with focus on dividend-growth oriented PSX blue-chips. This is the primary inflation-beating component.
15 to 20 percent in gold through the Meezan Gold Fund or similar regulated instrument. This provides inflation and currency depreciation protection.
20 to 30 percent in fixed income including National Savings products at best available rates and floating rate government instruments where accessible. This provides stability and income.
10 to 15 percent in real estate through REITs listed on PSX. This provides real asset exposure without the illiquidity of direct property.
5 to 10 percent in foreign currency savings or USD Naya Pakistan Certificates for overseas Pakistanis. This provides direct rupee depreciation protection.
This is a framework, not a prescription. Your specific allocation should reflect your actual time horizon, your specific goals, your tax situation, and your realistic emotional tolerance for portfolio volatility during market downturns. The framework’s purpose is to ensure every component of your portfolio is either directly beating inflation or protecting against specific inflation-linked risks, rather than passively accepting erosion through below-inflation returns.
Conclsuion
Inflation is Pakistan’s most persistent financial challenge and arguably its most underappreciated investment risk. The extraordinary volatility of the past few years, from a 60-year inflation low in March 2025 to a renewed acceleration toward 12 percent by mid-2026, demonstrates that inflation in Pakistan is not a stable background rate to be easily planned around. It is a dynamic force that requires an active, diversified, and informed investment response.
The investors who have built genuine real wealth in Pakistan through inflationary periods are not those who found a single inflation-proof product. They are those who combined equity’s pricing-power advantage, gold’s currency and commodity hedge, fixed income’s stability anchor, and real assets’ tangible value protection into portfolios that collectively maintained and grew purchasing power across different economic environments.
Beating inflation over a lifetime in Pakistan requires accepting equity risk, holding real assets, maintaining some foreign currency exposure, and continuously measuring your returns in real rather than nominal terms. None of these is comfortable in the short run. All of them are necessary for the long-run outcome most Pakistani investors genuinely want: to have more real purchasing power tomorrow than they have today.










