In August 2026, the Securities and Exchange Commission of Pakistan referred a genuinely striking case to the FIA: Blink Capital Management, a company that was not some fly-by-night operation running out of a WhatsApp group, but an actual SECP-licensed futures broker and market maker registered with the Pakistan Mercantile Exchange, with a registered office in Gulberg III, Lahore, and branches in Karachi and Islamabad.
SECP’s investigation found that Blink had been offering investors predetermined returns ranging from 3.7 percent per month to 48 percent per annum, backed by post-dated security cheques, while the funds collected, alleged to total over Rs 446.6 million, flowed not into the company’s proper regulated accounts but into a personal account maintained in the name of an employee, registered as his own sole proprietorship. Here I am going to share with you how to spot an investment scam in Pakistan.
This case is genuinely instructive precisely because it complicates the advice most people expect to hear. “Just check if they’re SECP-licensed” is necessary but, as this case shows, not sufficient on its own. SECP itself made this point explicitly in its statement on the matter: registration or licensing of an entity does not authorize it to undertake activities beyond the scope of its license or to solicit deposits from the public without lawful authority.
This article covers the specific, documented patterns Pakistani investment scams have followed, drawn directly from SECP’s own public warnings and enforcement actions, and a practical checklist for verifying legitimacy before a single rupee changes hands.
Table of Contents
The Core Principle SECP Itself Emphasizes
Before I share deep data on how to spot an investment scam in Pakistan, you need to know the core principle SECP itself emphasizes. SECP’s own guidance following the Blink Capital case is worth quoting directly because it reframes the entire verification process correctly: investors are strongly advised to independently verify the regulatory status and permitted activities of an entity before placing funds with it, and to remain particularly cautious of investment schemes promising fixed, unusually high, or guaranteed returns.
The two-part test embedded in that sentence matters. It is not enough to confirm that a company exists and holds some license somewhere. You must also confirm that the specific product being sold to you, a fixed monthly return scheme, a guaranteed-profit trading plan, a leasing or financing arrangement, actually falls within what that license permits. Blink Capital’s PMEX broker license permitted it to execute futures trades on behalf of clients. It did not permit it to take public deposits and promise fixed, guaranteed monthly returns, which is precisely the activity SECP’s investigation flagged as an unauthorized, Ponzi-type scheme.
Documented Scam Patterns in Pakistan: Real, Named Examples
To learn on how to spot an investment scam in Pakistan, you have to understand the documented scam patterns. SECP has repeatedly named specific fraudulent platforms in its public warnings, which is genuinely useful because it lets you see the actual patterns rather than abstract descriptions.
Fake international brokerage clones. In one 2025 warning, SECP explicitly named a set of unlicensed platforms operating under names designed to sound like established international firms, including entities styled to resemble Interactive Brokers Group and other recognizable brands, none of which held any Pakistani license. The pattern: borrowing the credibility of a real, well-known name (or a close variation of one) while operating entirely outside any Pakistani regulatory framework.
Fake forex trading apps using government imagery. Pakistan’s Financial Monitoring Unit identified a cluster of Android applications, marketed under names like P Trade, A Trade, and G Trade, that falsely used an image of the Prime Minister of Pakistan alongside foreign nationals to imply official endorsement. These apps advertised extraordinarily specific and extraordinarily fast returns: an investment of Rs 5 promised to return Rs 200, Rs 50 promised to return Rs 3,000, and Rs 500 promised to return Rs 40,000, all within a period of two to three days.
Illegal deposit-taking disguised as leasing or financing schemes. SECP has separately named companies including one styled as an online jobs platform and others structured as financing companies, which were found to be soliciting public deposits framed as leasing or financing plans for cars, motorcycles, and houses, an activity that falls under illegal banking business without lawful authority, regardless of how the marketing described it.
Social media “advisory” and “training” schemes. SECP’s ongoing warnings describe fraudulent investment advisory services and trading “training courses” promoted heavily on Facebook, Instagram, and WhatsApp, which misuse the names, photos, and logos of real, well-known business professionals and even SECP’s own name and the Pakistan Stock Exchange’s branding to appear credible, before charging membership fees or soliciting investment through the advertised platform.
The Red-Flag Checklist
| Red Flag | Why It Matters |
|---|---|
| Fixed or guaranteed returns, especially expressed as a specific monthly or annual percentage | Legitimate market-linked investments (as covered in the stock market and mutual fund articles in this series) never guarantee a fixed return; only capital-protected instruments like National Savings do, and their rates are publicly set, not individually negotiated |
| Returns that sound implausibly fast or large relative to the amount invested | The P Trade pattern above (Rs 5 to Rs 200 in days) is an extreme but real, documented example of this exact tactic |
| Post-dated cheques offered “as security” for your investment | This was a specific feature of the Blink Capital scheme; a cheque is not equivalent to regulatory protection or genuine collateral |
| Use of a real public figure’s name or image without clear, verifiable association | A documented tactic (the PM’s image on P Trade) exploiting borrowed credibility |
| Pressure to recruit others or a structure where your returns depend on new investors joining | The defining structural feature of a Ponzi scheme |
| A licensed-sounding entity offering a product outside its actual licensed scope | The precise lesson of the Blink Capital case; licensing alone is not proof the specific product is authorized |
| Solicitation exclusively through WhatsApp groups, Instagram DMs, or unsolicited social media ads | SECP has repeatedly flagged this as the primary distribution channel for fraudulent schemes since at least 2024 |
| Funds requested to a personal bank account or an individual’s name rather than the company’s own verified account | Exactly how Blink Capital’s funds were allegedly routed, through an employee’s personal sole-proprietorship account |
How to Actually Verify a Platform: A Two-Step Process
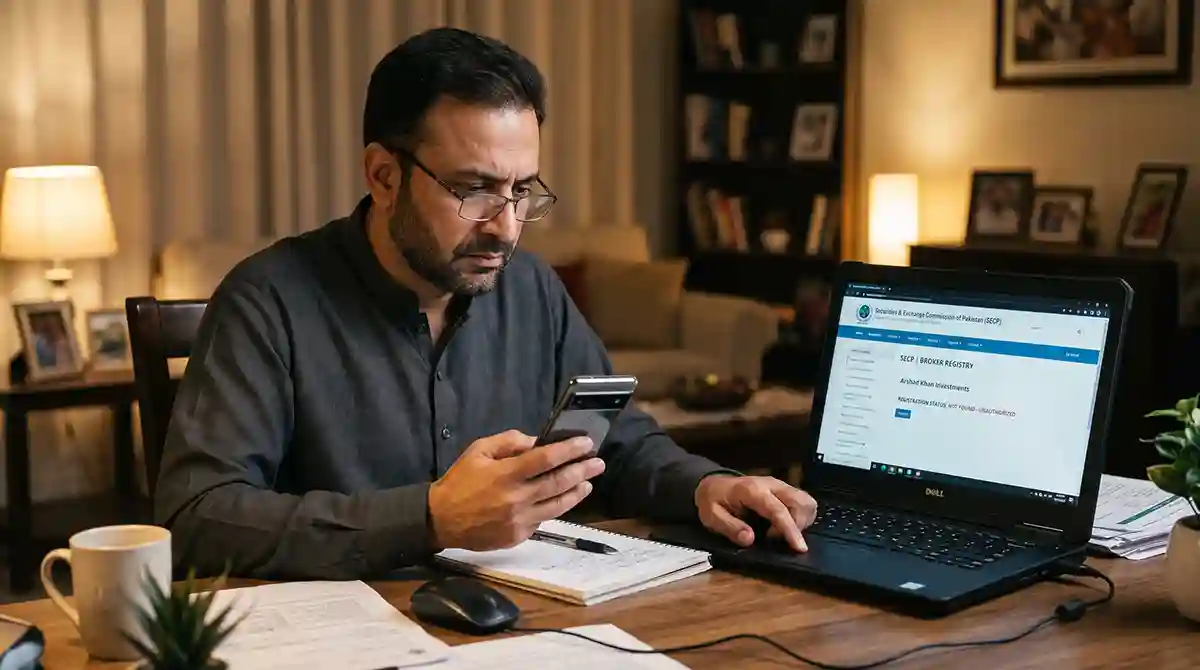
Step 1: Confirm the entity is licensed at all. For stock and futures brokers, cross-check the name against the official broker lists published by the Pakistan Stock Exchange (psx.com.pk) and the Pakistan Mercantile Exchange (pmex.com.pk), as covered in the brokerage account and stock market basics articles in this series. For asset management companies and mutual funds, verify membership through the Mutual Funds Association of Pakistan (mufap.com.pk), as covered in the mutual fund investing article. For any other entity claiming SECP oversight, search SECP’s own official registry directly at secp.gov.pk rather than trusting a screenshot or certificate the platform itself provides.
Step 2: Confirm the specific product is within that license’s actual scope. This is the step the Blink Capital case shows most people skip. A valid PMEX broker license authorizes futures brokerage, not public deposit-taking with guaranteed returns. A valid AMC license authorizes management of SECP-approved fund schemes with published, market-linked NAVs, not a private, off-platform “special plan” offering a fixed monthly percentage. If you cannot find the specific investment product listed among an entity’s officially approved and published offerings, the fact that the entity itself holds some license elsewhere is not protection.
A practical worked example: if someone approaches you offering to place your money with “a SECP-licensed broker” who will generate 4 percent monthly returns, the correct verification sequence is: first, check whether that broker actually appears on PSX’s or PMEX’s published list (Step 1); second, and just as important, ask specifically whether this fixed 4 percent monthly scheme is a product listed on the broker’s own official website or SECP’s approved product list, or whether it is being offered “privately” or “off the books” by an individual associated with the firm (Step 2) A private, off-platform arrangement promising a guaranteed return, even if the person offering it genuinely works at a licensed firm, is precisely the structure that produced the Blink Capital case.
Where to Report a Suspected Scam
If you encounter a platform or scheme matching these patterns, SECP has stated it works directly with the Federal Investigation Agency, the Pakistan Telecommunication Authority, and the State Bank of Pakistan to pursue legal action and, where relevant, request platform blocking. Reporting through SECP’s own complaint channel is the appropriate first step, since SECP has the authority to refer matters to FIA under Section 41B of the SECP Act 1997 for formal investigation, exactly as it did in the Blink Capital case.
If you have already transferred funds, additionally file a report with the FIA’s National Response Centre for Cyber Crimes, as covered in the banking fraud article in this series, and preserve every piece of communication, payment receipt, and screenshot as evidence, since these records are what allowed SECP’s investigators to trace the Blink Capital funds to the specific personal account they were ultimately routed through.
Common Mistakes Pakistanis Make That Scammers Rely On
Trusting a scheme because it came from someone genuinely licensed or genuinely employed at a real firm. As the Blink Capital case demonstrates directly, fraud can originate from within a legitimately licensed institution when a specific product or arrangement operates outside that license’s actual permitted scope.
Treating a post-dated cheque as equivalent to real security. A cheque from an individual or an unverified account is a promise, not a guarantee, and offers none of the regulatory protections that come with investing through the properly disclosed, SECP-approved products covered throughout this series.
Being persuaded by borrowed credibility rather than verified credibility. Whether it is a scheme using SECP’s own logo without authorization, a platform styled to resemble a recognizable international broker’s name, or an app using a public figure’s photo, the presence of a familiar name or logo proves nothing on its own; only direct verification against the official registries listed above does.
Assuming a scheme must be legitimate because it has been running for months without apparent problems. Ponzi-structured schemes, by definition, can pay early participants using later participants’ deposits for a period of time, sometimes a considerable period, before collapsing; a track record of a few months of payouts is not evidence of underlying legitimacy.
Skipping verification because a friend or relative already invested and vouched for it. Word-of-mouth trust is precisely the mechanism through which these schemes spread fastest in Pakistan, and it substitutes social proof for the actual regulatory verification covered in this article.
In Summary
The Blink Capital Management case is a genuinely useful teaching example specifically because it shows that “check if they’re licensed” is real but incomplete advice. The company was licensed. The fraud existed in the gap between what it was authorized to do and what it was actually selling, a gap that SECP’s own statement identifies as the central lesson: verify not just the entity, but the specific product and whether it sits within that entity’s actual permitted activities.
Every legitimate investment vehicle covered throughout this series, PSX stocks and mutual funds, National Savings certificates, Sukuk, VPS pension accounts, has a specific, publicly disclosed, market-linked or officially fixed return structure that you can independently verify against an official source. Any scheme that instead relies on a private arrangement, a guaranteed fixed percentage negotiated individually with you, and a post-dated cheque as its only backing, has already stepped outside that entire framework, regardless of who is offering it.
Further reading and official sources:
- Securities and Exchange Commission of Pakistan: official press releases, licensee verification, and scam warnings: secp.gov.pk
- Pakistan Stock Exchange: official list of licensed brokers: psx.com.pk
- FIA National Response Centre for Cyber Crimes: reporting fraud: complaint.fia.gov.pk