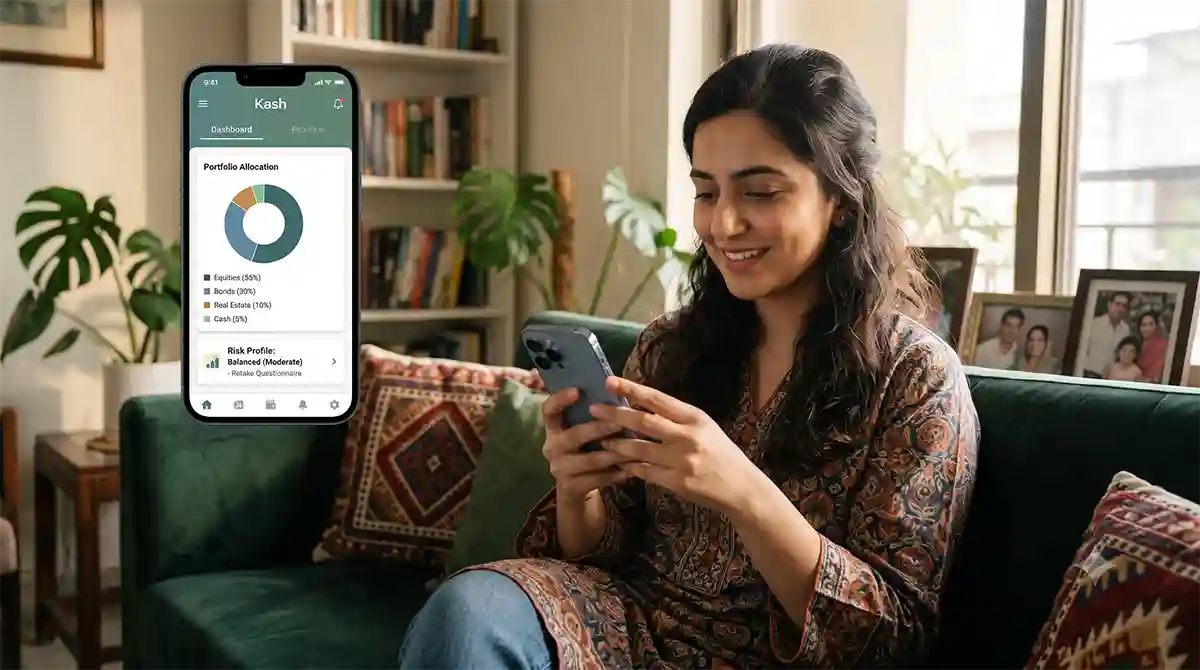
A colleague who had never invested a rupee in her life once told me she avoided mutual funds for years because the idea of walking into an AMC branch, filling out forms, and being asked questions she did not know the answers to felt genuinely intimidating. What eventually got her started was not a bank visit at all. It was an app that asked her a handful of simple questions about her goals and comfort with risk, and within about ten minutes had her money going into a diversified portfolio she could track on her phone. In this article, you will learn about Robo-Advisors and digital investment platforms in Pakistan.
This is the promise of a robo-advisor: automated, algorithm-driven portfolio management that removes the intimidation factor of traditional investing without removing the substance behind it. Globally, this category has grown into a multi-trillion-dollar industry led by platforms like Vanguard’s Digital Advisor. In Pakistan, the category is much younger and much smaller, but it is genuinely no longer theoretical. This article covers what actually exists in Pakistan today, how it compares to the traditional AMC-based investing covered throughout this series, and whether it is worth using.
Table of Contents
What a Robo-Advisor Actually Is (And Isn’t)
Before you learn about Robo-Advisors and digital investment platforms in Pakistan, you need to know what a Robo-Advisor is. A true robo-advisor does three specific things: it assesses your goals and risk tolerance through a short questionnaire, it builds and manages a diversified portfolio on your behalf using algorithms rather than a human advisor making individual calls, and it automatically rebalances that portfolio over time as markets move and as your own circumstances change.
This is meaningfully different from three other categories of app that often get lumped in under the same “digital investing” label in Pakistan, and it is worth being precise about the distinction before evaluating any specific platform.
| Category | What It Actually Does | Example in Pakistan |
|---|---|---|
| True robo-advisor | Builds and manages a diversified portfolio for you automatically | Mahaana |
| Brokerage/trading app | Gives you the tools to buy and sell securities yourself | KTrade |
| Market analysis/tracking app | Shows prices, charts, and research; does not execute trades | Investify |
| AMC digital onboarding | Lets you open and manage a mutual fund SIP account digitally, but you still choose the fund yourself | Most major AMC apps (as covered in the mutual fund investing article in this series) |
None of the last three are robo-advisors in the strict sense, even though they are all genuinely useful digital investment tools. Understanding which category a platform actually falls into before you sign up prevents the common mistake of expecting automated portfolio management from an app that is really just a trading terminal or a research tool.
Mahaana: Pakistan’s First Licensed Digital Wealth Manager
Mahaana is currently the clearest example of a genuine robo-advisor operating in Pakistan. It is SECP-licensed, a member of the Mutual Funds Association of Pakistan (MUFAP), and holds client funds in custody through the Central Depository Company (CDC) rather than on its own balance sheet, meaning your money can only ever be withdrawn to your own registered bank account, not diverted elsewhere.
The platform builds diversified, Shariah-compliant portfolios tailored to a user’s stated goals and risk profile, with onboarding designed to take under ten minutes from a smartphone. Its strategic backers include IGI, whose insurance and securities arms bring an established local fund management track record to the platform. This combination of SECP licensing, CDC custody, and MUFAP membership is genuinely the regulatory checklist any Pakistani investor should be running through before trusting any platform with real money, and Mahaana is a rare example that clears all three at once.
A worked comparison: if you invest PKR 50,000 through a traditional AMC route, you typically select a specific fund yourself (an equity fund, an income fund, or a balanced fund, as covered in the mutual fund investing article in this series), and you are responsible for deciding when and whether to rebalance across fund categories as your goals or risk tolerance change. Through a robo-advisor model like Mahaana’s, that same PKR 50,000 is allocated across a diversified mix based on your stated risk profile, and the platform itself handles the ongoing rebalancing decision rather than leaving it entirely to you.
The Broader Emerging Ecosystem
Beyond Mahaana specifically, Pakistan’s digital investment landscape has grown into several distinct, genuinely useful tools in 2026, even where they do not meet the strict definition of a robo-advisor.
KTrade, operated by KASB Securities, has reportedly surpassed one million users and offers direct access to PSX stocks, commodity futures, money market instruments, and ETFs on a single SECP-regulated platform, backed by a substantial YouTube and podcast education library and a structured financial academy. This is a self-directed brokerage app rather than an automated advisor: it gives you the tools and the research support, but you are the one making the buy and sell decisions, in the same way covered in the stock market basics and company evaluation articles in this series.
Investify functions as a market-tracking and analysis tool used by hundreds of thousands of PSX investors, providing real-time prices for over 500 listed companies, interactive charts with up to five years of historical data, financial fundamentals, and a filter specifically for Shariah-compliant stocks using the KMI-30 and KMI All Shares indices. It also offers a free demo trading account, making it a genuinely useful research companion to have open alongside whichever platform you actually execute trades through, but it is not itself a place where money changes hands.
CDC’s own iInvest platform, mentioned in the mutual fund investing article in this series as an aggregator, gives investors access to funds from multiple AMCs through a single account with multi-device portfolio sync and historical price data, sitting somewhere between a pure AMC app and a full robo-advisor, since you still select your own fund allocation.
The Asaan Connect App, a SECP-backed initiative led by CDC, is scheduled to launch in July 2026 with the specific goal of centralizing KYC across stocks, mutual funds, and insurance products into a single verified profile, so an investor completes identity verification once and can use that same profile across different regulated financial institutions rather than repeating documentation for every new platform. SECP Chairman Dr. Kabir Ahmed Sidhu has described the initiative as part of a broader push to make Pakistan’s capital markets more inclusive through financial technology. This is not itself a robo-advisor, but it directly addresses one of the biggest practical frictions that has historically discouraged first-time Pakistani investors from getting started at all.
How Digital Platforms Compare to Traditional AMC Investing
| Factor | Traditional AMC (branch or app) | Robo-Advisor (e.g., Mahaana) | Self-Directed Brokerage (e.g., KTrade) |
|---|---|---|---|
| Who chooses the specific fund/stocks | You do, from the AMC’s available funds | The platform’s algorithm, based on your risk profile | You do, entirely |
| Ongoing rebalancing | Manual, your responsibility | Automated by the platform | Manual, your responsibility |
| Minimum effort required | Low to moderate | Very low | Higher; requires ongoing research |
| Best suited for | Investors who know what fund category they want | Complete beginners wanting a hands-off start | Investors who want to actively research and pick their own positions |
| Underlying regulation | SECP + MUFAP | SECP + MUFAP + CDC custody | SECP (brokerage licensing) + CDC |
The honest answer to “which is better” is that they are not really competing products; they suit different types of investors at different stages. A reader who has already worked through the mutual fund, PSX stock-picking, and company evaluation articles elsewhere in this series and enjoys the research process is likely better served by a self-directed brokerage app like KTrade combined with a research tool like Investify. A reader who wants professional-style portfolio construction without doing that research themselves, closer to the “core” portion of the core-satellite approach discussed in the portfolio-building article in this series, is the more natural fit for a genuine robo-advisor like Mahaana.
The Verification Habit That Matters More Than Any Feature Comparison
This is worth stating plainly, because it is the single most important practical takeaway in this entire topic: not everything marketed as an “investment app” in Pakistan is a regulated financial product. As covered in the investment scam guidance elsewhere in this series, social media “investment experts” with no verifiable credentials and multi-level marketing schemes disguised as investment platforms have specifically targeted the exact demographic that digital investment apps are trying to reach, first-time, digitally comfortable investors who may not yet know what a genuine SECP license actually looks like.
Before trusting any platform with money, verify three things directly rather than taking the app’s own marketing at its word: that it is licensed by SECP (checkable on SECP’s own website), that client funds are held in custody through CDC rather than on the platform’s own balance sheet, and, if the platform positions itself as a MUFAP member for fund-related products, that this membership is genuine and current. If a platform cannot clearly answer where your money is actually held, or if recruiting other users is part of how returns are generated, that is not an investment platform regardless of how it is marketed.
Common Mistakes Pakistani Investors Make With Digital Platforms
Assuming a slick app interface is proof of regulatory legitimacy. A well-designed app is a design achievement, not a licensing credential. Check SECP’s own registry directly.
Treating a market analysis app like Investify as if it manages money on your behalf. These tools are genuinely valuable for research, exactly as covered in the company evaluation article in this series, but they do not hold custody of your funds or make investment decisions for you.
Confusing a brokerage app’s convenience with a robo-advisor’s automation. KTrade and similar platforms make it easy to place a trade in seconds; they do not decide what to buy for you or rebalance your portfolio automatically the way a genuine robo-advisor does.
Ignoring the risk-profile questionnaire’s actual purpose when signing up for a robo-advisor. These questions exist to genuinely calibrate your portfolio to your real risk tolerance, not as a formality to click through quickly. Answering them honestly, rather than optimistically, produces a portfolio you are far more likely to actually stay invested in through a downturn, as covered in the behavioral finance article in this series.
Conclusion
Pakistan’s robo-advisor and digital investment platform ecosystem in 2026 is real but still young, anchored by Mahaana as a genuinely licensed, CDC-custodied example of true automated portfolio management, supported by a growing set of adjacent tools including KTrade for self-directed brokerage, Investify for research, and the upcoming SECP-backed Asaan Connect App aiming to remove onboarding friction across the entire market.
For a beginner specifically intimidated by the traditional process of choosing a fund category, opening an AMC account, and manually rebalancing over time, a genuine robo-advisor is a legitimate, lower-friction entry point into exactly the kind of diversified investing covered throughout this series, provided you verify its regulatory credentials directly before depositing any money. For an investor who already enjoys the research process covered in the stock-picking and company evaluation articles in this series, a self-directed brokerage app paired with a research tool remains the more natural and often lower-cost fit.
Further reading and official sources:
- Securities and Exchange Commission of Pakistan: registered advisor and licensee verification: secp.gov.pk
- Central Depository Company of Pakistan: investor custody and iInvest platform information: cdcpakistan.com
- Mutual Funds Association of Pakistan: member verification: mufap.com.pk