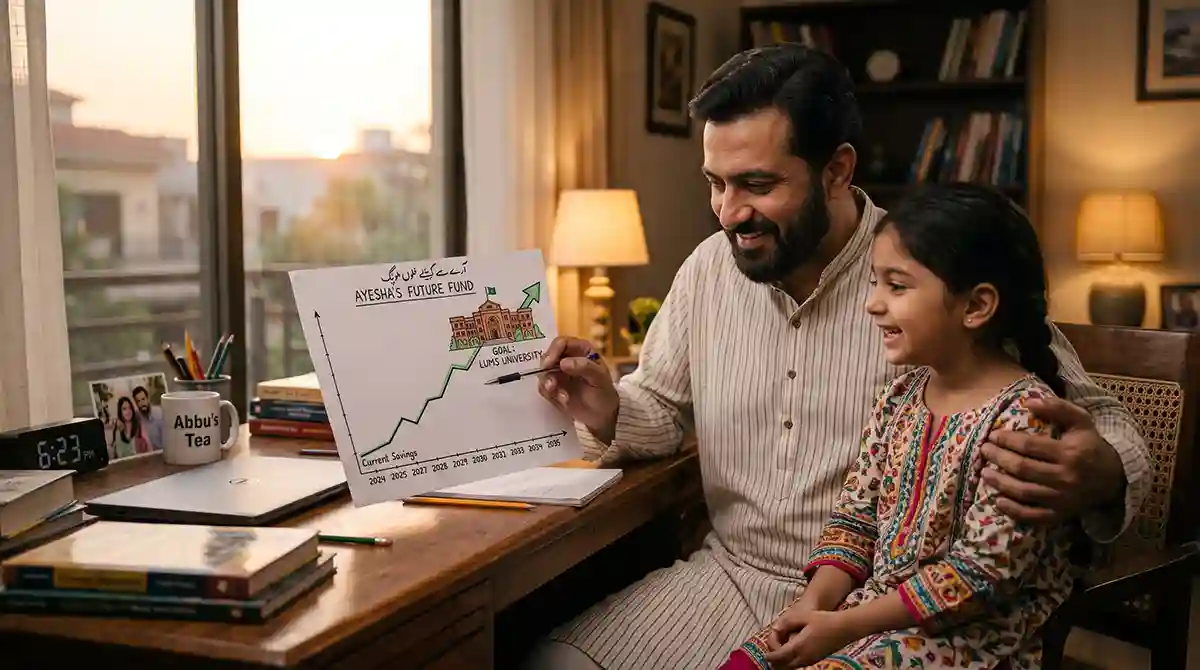
A father I know did the maths on his daughter’s future education the year she turned five, using what a four-year engineering degree at NUST cost that specific year as his planning number. By the time she actually reached university age thirteen years later, the same degree cost more than three times what he had originally budgeted for, not because he had underestimated the fees, but because he had never adjusted his original number for inflation across those thirteen years. He had saved diligently toward a target that was quietly moving further away from him every single year. This article guide you on how to invest for your child’s education or marriage in Pakistan.
This is the single most common and most costly mistake in goal-based investing for Pakistani parents: treating today’s cost of education or marriage as tomorrow’s cost, rather than genuinely accounting for what inflation does to a target that sits fifteen or twenty years in the future. This guide brings together the mutual fund SIP discipline, the dollar cost averaging habit, and the National Savings and inflation-planning concepts covered throughout this series into a single, practical framework for two of the most significant financial goals most Pakistani families ever plan for.
Table of Contents
Why Education and Marriage Goals Require a Different Approach
Before you know how to invest for your child’s education or marriage in Pakistan, you must understand why education and marriage goals require a different approach. Unlike a retirement goal, discussed in detail in the retirement planning article in this series, which is inherently flexible in timing, both education and marriage goals in Pakistan typically arrive on a fixed, non-negotiable schedule. Your child turns eighteen and needs university fees whether or not your investments have performed as hoped that particular year. This fixed-deadline characteristic is precisely why goal-based investing for these two purposes needs a more deliberate structure than simply “saving whatever is left over each month.”
Step 1: Calculate What the Goal Will Actually Cost, Inflation-Adjusted
This is the step the father in the opening story skipped, and it is the foundation everything else in this guide depends on.
Real education costs in Pakistan today (2026) vary enormously by institution type, and understanding this range is the starting point for any realistic projection.
| Institution Type | Approximate Total Cost for a 4-Year Degree (2026) |
|---|---|
| Public university (Punjab University, UET on merit seat) | PKR 200,000 – 400,000 |
| Mid-tier institution (NUST, FAST, COMSATS) | PKR 1.6 million – 2.4 million |
| Top private university (LUMS) | PKR 2.8 million – 5 million |
| Private medical college (MBBS) | PKR 10 million – 18 million |
| Public medical college (MBBS) | PKR 250,000 – 500,000 |
With education inflation running alongside Pakistan’s broader consumer inflation, which has hovered around 10 to 15 percent through 2026, and households now shouldering 56 percent of the country’s total education financing burden according to recent economic survey data, a goal set today without inflation adjustment will be significantly underfunded by the time it actually arrives.
A worked projection: if a mid-tier engineering degree costs PKR 2 million today and you are planning for a child currently five years old who will need this money in thirteen years, applying a conservative 10 percent annual education inflation rate compounds that PKR 2 million target to approximately PKR 6.8 million by the time your child actually enrolls. This is the number you should actually be planning around, not the PKR 2 million figure that feels real and tangible today.
Marriage costs in Pakistan are genuinely harder to project with precision, since they vary enormously by family, city, and the scale of celebration chosen, and no single reliable published benchmark exists the way HEC-adjacent fee data does for education. What is worth planning around is the honest recognition that wedding costs in Pakistan have risen substantially in recent years driven by venue, catering, and décor inflation specifically, often outpacing general consumer inflation in this particular category. Rather than anchoring to a specific rupee figure that may not reflect your own family’s actual plans or expectations, the more useful exercise is having an honest conversation within your own family about the realistic scale of celebration you are planning for, and then applying the same inflation-adjustment discipline used for education to whatever figure that conversation produces.
Step 2: Match Your Time Horizon to the Right Asset Allocation
As covered in the investment portfolio building article in this series, the appropriate mix between growth-oriented and capital-preserving assets depends heavily on how much time remains before you need the money. This principle applies with particular force to education and marriage goals precisely because their fixed deadlines leave no room for waiting out a badly timed market downturn.
| Years Until Goal | Suggested Approach |
|---|---|
| 12+ years away (goal set for a young child) | Primarily equity mutual fund SIPs for maximum inflation-beating growth, as covered in the mutual fund investing and long-term stock investing articles in this series |
| 5–12 years away | Gradually shifting mix of equity funds and balanced/income funds; begin introducing Sukuk and National Savings certificates |
| 1–5 years away | Predominantly National Savings certificates, Sukuk, and fixed deposits, prioritizing capital preservation over growth |
| Under 1 year away | Fully in liquid, capital-protected instruments; no market exposure at all |
This is essentially the same glide-path logic covered in the retirement planning article’s life-stage allocation framework, compressed into whatever specific number of years actually separates you from your child’s eighteenth birthday or your own planned wedding timeline.
Step 3: Reverse-Engineer Your Required Monthly SIP
Once you have an inflation-adjusted target figure and a realistic time horizon, the dollar cost averaging article in this series covered exactly the calculation method needed here, applied in reverse: rather than projecting what a fixed monthly SIP will grow to, you work backward from your target to determine what monthly contribution is actually required.
A worked example using the education projection above: targeting PKR 6.8 million in thirteen years, and assuming a realistic long-term equity mutual fund return of 15 percent annually for the growth-oriented early years of this goal, a monthly SIP of approximately PKR 18,000 to 20,000, maintained consistently and shifted toward more conservative instruments in the final few years before the goal, would realistically reach this target. A parent unable to commit that amount from month one can apply the step-up SIP approach covered in the dollar cost averaging article, starting with a smaller, sustainable amount and increasing it by a fixed percentage annually alongside income growth, which substantially closes the gap over the full thirteen-year period without requiring the full commitment immediately.
Step 4: Choose the Right Account Structure
As covered in the teaching children about money article in this series, a dedicated mutual fund account or National Savings certificate held specifically in your child’s name, with you as the parent or guardian managing it, serves two purposes simultaneously: it keeps this specific goal’s savings genuinely separate from your general household investments, reducing the temptation to redirect the money toward an unrelated expense, and it builds the foundation of genuine financial literacy for your child as they grow old enough to understand what the account represents.
For a marriage-focused goal specifically, whether for yourself, a spouse, or a child, the same dedicated-account principle applies, though the account would typically remain in the contributing parent’s own name given the more variable and family-specific nature of when and how this particular goal is actually realized.
Step 5: Build in an Annual Review, Not Just an Annual Contribution Increase
Beyond simply increasing your SIP amount each year through the step-up approach, a genuine annual review of the goal itself matters. Check whether your original inflation assumption still holds given the actual education or wedding cost trends of that specific year, whether your child’s academic direction has become clearer in a way that changes your target institution and therefore your target cost, and whether your portfolio’s actual performance is tracking ahead of, in line with, or behind your original projection, adjusting your monthly contribution accordingly rather than discovering a significant shortfall only when the goal actually arrives.
Common Mistakes Pakistani Parents Make With These Goals
Anchoring the entire savings target to today’s cost without any inflation adjustment, exactly the mistake the father in the opening story made, and by a wide margin the single most consequential error in this entire planning exercise.
Keeping the entire goal in a savings account or fixed deposit regardless of how many years remain, missing the substantial inflation-beating growth that equity exposure provides during the early, long-horizon years of a goal that will not be needed for over a decade.
Not shifting the portfolio toward safety as the goal approaches, leaving a goal that is now only two or three years away still heavily exposed to equity market volatility right when a poorly timed downturn would do the most damage to a fixed, non-negotiable deadline.
Treating this goal’s savings as accessible for other family needs. Without a genuinely dedicated account structure, education or marriage savings frequently get quietly redirected toward other, more immediate family expenses, undermining years of disciplined contribution.
Setting the target once at the start and never revisiting it. Education and, in particular, wedding costs in Pakistan have shown a tendency to rise faster than general inflation in recent years; an annual check-in keeps your target honest rather than allowing it to drift further from reality with each passing year, as it did for thirteen years in the opening story before the gap finally became impossible to ignore.
Conclusion
Investing for a child’s education or a family wedding in Pakistan is not fundamentally different from the goal-based investing principles covered throughout this series; it simply demands a more deliberate accounting for inflation given how far into the future, and how fixed in timing, these two goals typically are. The father who planned around a static number thirteen years in advance was not undisciplined in his saving; he was simply solving for the wrong target from the very beginning.
Calculate your goal in inflation-adjusted terms, not today’s terms. Match your time horizon to the right mix of growth and safety. Reverse-engineer the monthly contribution that number actually requires. Keep the savings in a dedicated account. And revisit the whole plan honestly, at least once a year, rather than assuming the target you set on day one will still be accurate by the time the goal finally arrives.
Further reading and official sources:
- Higher Education Commission of Pakistan: recognized university listings and fee transparency: hec.gov.pk
- Pakistan Bureau of Statistics: Consumer Price Index and education inflation data: pbs.gov.pk