A freelance web developer I know in Karachi ran his entire business through his personal savings account for over two years. He sent invoices with his personal account IBAN, received international payments into his personal account, paid his subcontractors from the same account, and kept a rough mental note of what was business money and what was personal. It worked, sort of, until two things happened in the same month: a corporate client asked for a business bank account statement before paying a significant invoice, and his accountant told him that preparing his income tax return without clean business transaction records would be genuinely painful. This article explain you well about how to open a business bank account in Pakistan.
He opened a business bank account the following week. Within a month, his bookkeeping was cleaner, his tax situation was clearer, and the corporate client released the payment that had been held up.
In Pakistan in 2026, a business bank account is not a bureaucratic formality for companies with large offices and formal corporate structures. It is a practical necessity for anyone who wants to separate their personal and business finances, access business-specific banking services, receive payments from corporate clients and international platforms, apply for financing, and manage their tax situation intelligently. And despite a reputation for complexity, the process is more accessible than most business owners expect once they know exactly what is needed.
This guide covers every business structure separately, because the requirements genuinely differ, along with the honest nuances that trip up most first-time business account applicants in Pakistan.
Table of Contents
Why You Need a Business Bank Account Separate From Your Personal Account
If you are still running your business through your personal account, here is exactly what you are risking and missing.
Your bank can classify unusual transaction patterns on a personal account as potentially suspicious activity, particularly for accounts receiving frequent international transfers or large irregular deposits. Business accounts are specifically designed for commercial activity and therefore avoid this friction.
Corporate clients, particularly government departments and large registered companies, typically require a business account number on your invoices and may refuse to release payments to a personal account. Some international payment platforms and marketplaces also require a registered business banking relationship for higher payment limits.
Without clean business transaction records, your tax filing situation becomes genuinely messy. Your accountant cannot easily separate business revenue from personal income, legitimate business expenses from personal spending, or track your GST-applicable transactions. A dedicated business account creates an automatic audit trail that makes tax compliance significantly simpler and reduces your professional accounting fees.
Business financing and credit products, from bank loans to overdraft facilities and trade finance, are available only to businesses with an active business banking relationship. A business current account with consistent transaction history is the foundation of any banking relationship that can eventually support your business’s growth with credit facilities.
Which Type of Business Account Do You Actually Need?
Before getting into the opening process, understanding the difference between the main business account types prevents a common mistake that sends applicants back to the bank for a second visit.
Business Current Account
This is the standard account for most businesses in Pakistan and the right choice for any business that needs to conduct frequent transactions. Current accounts allow unlimited deposits and withdrawals with no transaction count limits. They do not earn profit or interest on the balance. They are designed for operational cash flow rather than for growing savings.
For any business that issues cheques, receives supplier or client payments regularly, needs to make frequent transfers, or operates with regular cash inflows and outflows, a business current account is the correct product. This is what most business owners mean when they say they need a business bank account.
Business Savings Account
Business savings accounts earn a modest profit rate on the balance and are subject to some transaction restrictions compared to current accounts. They are appropriate for holding business reserve funds or business emergency funds that the business is not actively transacting through daily.
For most businesses in Pakistan, the main operational account should be a current account with a separate savings account for holding reserves, if at all. Operating your entire business through a savings account to earn profit on the balance creates transaction restrictions that become frustrating as business activity increases.
Business Foreign Currency Account
For businesses that receive or make payments in foreign currency, whether USD for freelance income, exports, or international supplier payments, a foreign currency account holds balances in the original currency without automatic conversion to PKR. This protects the business from exchange rate movement between when the payment is received and when it is actually needed.
Most major Pakistani banks offer foreign currency business current accounts for eligible businesses. The SBP regulates which businesses can hold foreign currency accounts and under what conditions.
Opening a Business Account by Business Structure
The documentation requirements genuinely differ by how your business is structured, and arriving at the bank with the wrong set of documents is the most common reason the process takes multiple visits instead of one. Here is exactly what each structure needs.
Sole Proprietorship
A sole proprietorship is the simplest structure and has the most streamlined business account opening process. You are the business and the business is you. There is no formal SECP registration required for a sole proprietorship, which means the documentation requirement is lighter.
Documents you will need:
Your valid CNIC. Your National Tax Number from FBR, registered under your CNIC. Proof of business such as a business letterhead, business registration with the local chamber of commerce if applicable, a tax registration certificate, or any other documentation establishing your business identity and address. Proof of your business address, typically a utility bill or rent agreement for your business premises, though some banks accept a residential address if the sole proprietor operates from home with a utility bill in their name. Two passport-sized photographs.
Some banks are more flexible for sole proprietors than others. For freelancers specifically, some banks including Meezan Bank and HBL now accept proof of freelancing income such as platform invoices or payment history from Payoneer or Upwork in lieu of more formal business documentation. If you are a freelancer without a physical business address, it is worth calling ahead to your chosen bank to understand their specific requirements for freelancers before visiting.
Partnership
A partnership account requires documentation from all active partners. Documents you will need:
CNICs of all partners. The registered partnership deed, which should be formally registered with the local Registrar of Firms for legal validity though some banks accept an unregistered deed for smaller partnerships. NTN of the partnership firm from FBR. A partnership account opening letter signed by all partners authorizing the account opening and specifying which partners are authorized to operate the account. The business address proof through a utility bill or rent agreement. Two passport-sized photographs of each authorized signatory.
Banks typically require that all partners be present at the branch for biometric verification, or that those who cannot attend provide notarized authorization. Confirm this requirement with your specific bank before the branch visit.
Private Limited Company
A private limited company account has the most comprehensive documentation requirement because the account belongs to the company as a legal entity rather than to any individual. This is where many first-time corporate account openers face delays by arriving with incomplete documentation.
Documents you will need:
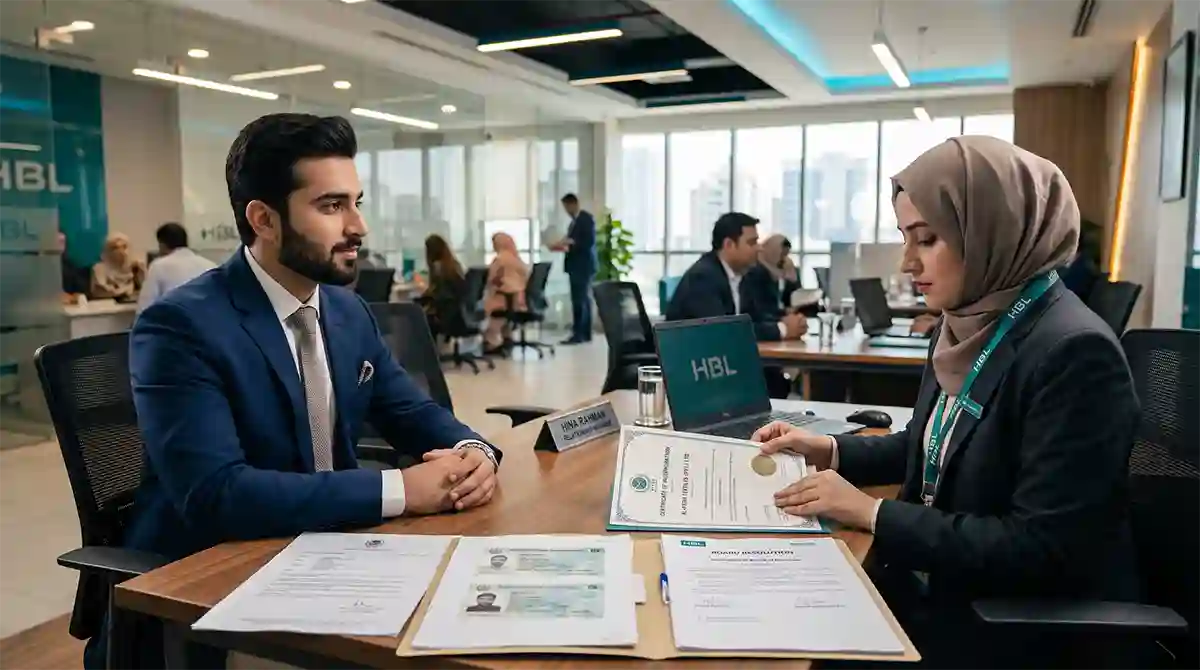
Certificate of Incorporation from SECP. This must be the Manual Certified True Copy issued by SECP rather than the digital or online certificate. This is one of the most commonly missed details that causes otherwise prepared applicants to return for a second visit. Banks require the SECP-stamped physical copy specifically.
Memorandum and Articles of Association, also in Manual CTC format from SECP. A Board of Directors Resolution specifically authorizing the opening of the bank account at the specific bank, specifying the authorized signatories and their signing authority, and signed by the majority of directors as required under the company’s articles. A company application letter requesting the account opening, on company letterhead, signed by the authorized director or directors. CNICs of all directors of the company. NTN of the company from FBR. Business address proof for the registered company address, typically a utility bill or rent agreement. Two passport-sized photographs of authorized signatories.
The distinction between Manual CTC and digital certificates from SECP is worth specifically addressing. When you complete your company registration through SECP’s online portal, you receive digital certificates. Banks in Pakistan require the manually certified physical copies, not the digital ones. You can obtain Manual CTCs by visiting the relevant SECP registration office and requesting them specifically. This typically takes one to two additional days after your digital registration is complete. Get these from the start to avoid delays at the bank.
Banks will also verify your company address physically in most cases. A bank representative will visit the stated business address before the account is approved. A residential address can work if you operate a home-based business and have a utility bill or rent agreement in either the director’s name or the company’s name at that address. A virtual address or PO box is not sufficient.
Single Member Company
Documentation requirements for a Single Member Company follow the same format as a private limited company. The key difference in the Board Resolution is that a single director can authorize the account opening without requiring multiple signatures, since by definition only one director exists in an SMC structure.
Choosing the Right Bank for Your Business: What to Compare
Not all Pakistani banks offer the same business banking experience, and the right choice depends heavily on what your business actually needs.
HBL
HBL is one of Pakistan’s largest banks with the widest ATM and branch network in the country, which is a meaningful practical advantage for businesses that make cash deposits and withdrawals frequently. HBL’s business current accounts come with internet banking, a dedicated relationship manager at larger branches, and access to a wide range of business financing products. It is a strong choice for businesses that need nationwide banking coverage.
Meezan Bank
For businesses seeking Shariah-compliant banking, Meezan Bank offers comprehensive Islamic business banking products including current accounts structured on Qard principles with no profit, business financing through Murabaha and Diminishing Musharakah, and strong digital banking through its app. Meezan has won consecutive Best Bank in Pakistan awards and is particularly well regarded for its SME customer service.
Bank Alfalah
Bank Alfalah is noted for its digital-first approach and has made strong investments in its business banking infrastructure. Its Alfa business platform provides digital account management, payroll services, and merchant solutions. It is a strong choice for businesses that want integrated digital banking tools alongside their account.
UBL
UBL is well known for its support for international transfers and is a common choice for businesses dealing with overseas clients and suppliers. Its online banking infrastructure for business is mature and its branch network is extensive.
MCB
MCB is one of Pakistan’s most established banks with a particularly strong presence in SME banking in Punjab and has historically offered competitive terms on business financing products for established businesses.
Standard Chartered Pakistan
Standard Chartered is particularly strong for businesses with international banking needs, businesses seeking multi-currency accounts, and businesses whose owners or shareholders have international banking relationships. Its business banking service is more premium and the minimum requirements for business accounts are correspondingly higher.
Faysal Bank
Faysal Bank is increasingly digital-first and has invested in its business banking infrastructure, offering Islamic business banking products and growing SME financing capabilities. It is worth considering for businesses seeking a digitally capable Islamic banking relationship.
JS Bank
JS Bank has positioned itself as a more entrepreneur-friendly option, offering business accounts with less friction than some traditional institutions and with digital-first features including online account management and business payment tools.
The Account Opening Process: Step by Step
Step 1: Prepare all your documents before visiting
Use the checklist above for your specific business structure and gather every document before your first branch visit. For private limited companies, specifically confirm you have the Manual CTC versions of your SECP certificates rather than digital prints. Missing even one document typically means a return visit, which delays your account activation by several days.
Step 2: Call the branch ahead of your visit
Call your chosen bank branch directly and confirm the specific documents they require for your business structure. Requirements vary slightly between banks and occasionally between branches. A five-minute phone call prevents the frustration of arriving with the wrong documents. Ask specifically whether all directors need to be present or whether notarized authorization works for absent directors.
Step 3: Visit the branch and meet the business banking officer
At the branch, ask specifically for the business banking desk or the SME banking officer rather than the general service counter. Some larger branches have dedicated business banking teams that handle commercial account openings more efficiently than the general banking staff.
Explain your business, the nature of your transactions, the expected monthly volume, and what services you need from the account. This context helps the officer direct you to the most appropriate account product and flags any additional documentation requirements for your specific business type.
Step 4: Complete the account opening form
The bank will provide its own account opening form. Complete it carefully and accurately, particularly sections covering your business’s nature of operations, expected monthly transaction volume, sources of income, and authorized signatories. The information you provide here forms part of your KYC record and inaccuracies can create compliance issues later.
Step 5: Submit documents and await verification
Your documents are typically sent to the bank’s head office or main branch for review. The bank’s field officer may visit your business address within a few days to verify it is real and operational. Account activation typically takes 7 to 15 working days for a private limited company and shorter for sole proprietors at banks with more streamlined SME onboarding.
Step 6: Set up digital banking immediately
Once your account is active, register for internet banking and the bank’s business mobile app before doing anything else. Setting up digital banking from the start means your first transactions go through cleanly and you can manage your account without branch visits for routine operations from day one.
Digital Business Accounts: A Growing Alternative in 2026
The traditional branch-based business account opening process has been complemented by a growing range of digital business account options in Pakistan in 2026.
Most major banks now offer to initiate the business account opening process online, though an in-person visit for biometric verification is still required in most cases even when the initial application is submitted digitally. This hybrid model reduces the number of branch visits required from potentially three or four in previous years to typically one, but fully remote account opening for private limited companies remains uncommon due to the physical document verification requirement.
For freelancers, solopreneurs, and very small businesses without formal company registration, several fintech platforms and digital wallet providers in Pakistan now offer business account functionality with simpler KYC requirements. These are not traditional bank accounts in the full regulatory sense but offer payment receiving, outgoing transfer, and basic financial management features suitable for the earliest stages of business operation. As your business grows and you need access to credit facilities, formal payment terms with corporate clients, and full banking services, transitioning to a formal business bank account at a regulated commercial bank becomes necessary.
After Opening Your Business Account: Establishing a Banking Relationship
Opening the account is the beginning, not the end. The decisions you make in the first six to twelve months of operating your business account significantly affect your ability to access business financing later.
Conduct all business transactions through the account. Revenue in, expenses out. Never blend personal and business transactions. This creates the clean, consistent transaction history that banks evaluate when you eventually want a business loan or overdraft facility.
Build a relationship with your branch manager or business relationship manager. Introducing yourself, explaining your business, and keeping them updated on your business’s progress over time creates the human relationship that still matters in Pakistan’s banking culture, even in an era of digital banking.
Maintain a healthy average balance. Many business current accounts have minimum average balance requirements. Understanding your specific requirement and maintaining it consistently avoids penalty charges and signals financial stability to your bank.
File your income tax returns on time and maintain your status on the FBR Active Taxpayers List. Many banking services, including preferred rates on financing products, are reserved for compliant taxpayers. Keeping your FBR compliance clean strengthens every aspect of your banking relationship.
Common Mistakes Pakistani Business Owners Make When Opening a Business Account
Arriving with the wrong type of SECP certificate. Digital certificates from SECP’s online portal are not accepted by banks. Manual CTC certificates from SECP are required. This single mistake is responsible for a significant proportion of repeat branch visits by private limited company owners.
Not having a verified business address. Banks send a field officer to verify your business address before approving a corporate account. A virtual address, a PO box, or an address that does not match any utility bills or agreements in your or your company’s name will fail this verification.
Not having the Board Resolution correctly drafted. The Board Resolution must specifically name the bank and branch where the account is being opened, specify the authorized signatories and their signing authority level, and be signed by the required number of directors as specified in the company’s Articles of Association. A generic resolution that does not name the specific bank is typically not accepted.
Opening a savings account instead of a current account for an operationally active business. The transaction limitations on savings accounts become a practical problem quickly for any business with regular payment inflows and outflows. Start with a current account.
Not setting up internet banking immediately. Business owners who delay internet banking setup lose weeks of digital access to their account and end up making unnecessarily inconvenient branch visits for routine transactions in the early weeks.
Summing Up
Opening a business bank account in Pakistan in 2026 is a more accessible process than its reputation suggests, particularly for sole proprietors and partnerships where documentation requirements are manageable. For private limited companies, the process is more involved but entirely navigable once you understand the specific documents required, particularly the Manual CTC requirement that trips up so many first-time corporate banking applicants.
The business bank account is not just an administrative box to tick. It is the financial infrastructure of your business: the record of what your business earns and spends, the foundation of your tax compliance, the gateway to business financing, and the professional signal to clients and suppliers that you operate formally and seriously.
Every day you run your business through a personal account is a day of mixed transaction records that will need to be untangled later. Open the business account now, set up digital banking on day one, and run all your business transactions through it consistently from the start. Everything that follows, from tax filing to loan applications to corporate client relationships, becomes significantly simpler as a result.