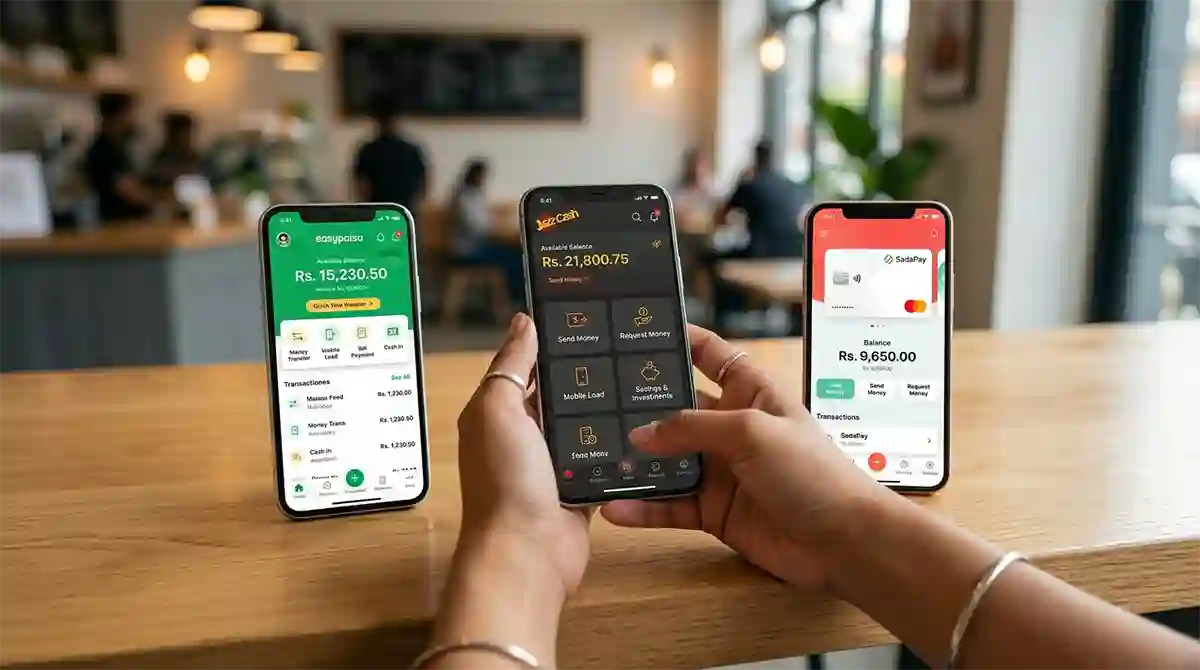
Mobile wallets in Pakistan have gone from a novelty to a necessity in a remarkably short period. A decade ago, sending money to a relative in another city meant either finding someone traveling that direction or standing in a bank queue. Today, the same transfer takes thirty seconds from your phone. Paying electricity bills, topping up mobile credit, receiving salary, paying a rickshaw driver, and collecting freelance payments from international clients have all moved to mobile wallets for a growing portion of Pakistani society.
With JazzCash and Easypaisa together accounting for over 110 million registered users across Pakistan, and newer entrants like NayaPay carving out a significant slice of the digitally savvy urban market, the mobile wallet space in 2026 is more competitive, more feature-rich, and more practically useful than at any previous point. But the differences between platforms matter, and choosing the wrong one for your specific needs costs you either money in unnecessary fees or convenience in missing features that would have made your financial life simpler.
This article compares JazzCash, Easypaisa, and NayaPay directly across the dimensions that actually matter for different types of users in 2026, so you can make an informed choice rather than simply defaulting to whichever platform came pre-installed on your phone.
Table of Contents
A Quick Overview of Each Platform
JazzCash
JazzCash is operated by Mobilink Microfinance Bank, a subsidiary of Jazz (formerly Mobilink), Pakistan’s largest telecom operator. Launched in 2012, it has grown to over 40 million users and is Pakistan’s largest mobile wallet by registered accounts. JazzCash is regulated by the State Bank of Pakistan and operates as a branchless banking service. Beyond personal money transfers, JazzCash has the most extensive merchant and QR payment network of any mobile wallet in Pakistan, making it particularly strong for retail and business use cases. It also has deep integration with Payoneer, making it one of the primary platforms for freelancer payment withdrawals.
Easypaisa
Easypaisa was Pakistan’s first mobile wallet, launched in 2009 by Telenor Pakistan in partnership with Tameer Microfinance Bank, now operating as Telenor Microfinance Bank. It has more than 35 million active users and carries strong brand recognition built over more than 15 years of operation. In 2026, Easypaisa has made a significant strategic move, transitioning into a fully fledged digital bank with upgraded account limits up to PKR 1,000,000 for verified users. It recently partnered with Ant International WorldFirst, enabling seamless global remittances from over 100 countries, which strengthens its already solid international transfer functionality. Easypaisa is compatible with any mobile network SIM, which is a genuine accessibility advantage.
NayaPay
NayaPay is Pakistan’s first SBP-licensed Electronic Money Institution, founded in 2019 and backed by international investors. It targets the digitally native, urban middle class and has built a reputation for a premium user experience, strong security features, and functionality particularly well suited to online shoppers and young professionals. NayaPay offers instant virtual card generation for online purchases, which allows users to create a unique card number for each transaction, significantly reducing fraud exposure on international platforms. It enables direct Payoneer withdrawals alongside JazzCash, making it increasingly relevant for freelancers seeking alternatives.
Feature Comparison: What Each Platform Offers in 2026
Money Transfers
All three platforms support instant person-to-person transfers. The critical 2026 development is that all transfers processed through Raast, Pakistan’s instant payment system, are completely free on every platform, and Raast now connects all banks and wallets seamlessly. This means you can send money from JazzCash to an HBL bank account, or from NayaPay to an Easypaisa wallet, for zero cost through the Raast infrastructure.
For non-Raast transfers, particularly interbank fund transfers processed outside the Raast network, JazzCash and Easypaisa charge PKR 50 to PKR 200 depending on the amount and destination. JazzCash allows free bank transfers up to PKR 50,000 monthly, after which a minimal percentage fee applies. NayaPay charges nothing for local transfers regardless of method, which has been a significant differentiator driving adoption among frequent-transfer users, particularly younger urban professionals who do multiple transfers per week.
Savings and Profit on Balance
JazzCash offers 14% annual profit on balances maintained in the account, which is genuinely competitive with most bank savings accounts. Easypaisa offers 12% annually. NayaPay does not currently offer a savings profit rate on balances but compensates with other features. For users who park meaningful amounts in their mobile wallet rather than just using it for transactional purposes, JazzCash’s higher profit rate is a meaningful advantage.
Debit Cards
JazzCash offers a physical debit card that works at ATMs and retail stores across Pakistan and online for digital purchases. Easypaisa also offers a physical debit card. NayaPay’s key differentiator in this category is the instant virtual card generation feature, allowing users to create virtual card numbers on demand for specific online transactions, which is particularly valuable for international online shopping on platforms like Amazon, Alibaba, and subscription services, as the virtual card limits fraud exposure to that single transaction amount.
Bill Payments and Utility Services
All three platforms support electricity, gas, water, internet, and telephone bill payments, as well as mobile top-ups, educational fee payments, and government service payments. This functionality is largely equivalent across all three platforms and differences are minimal in this category.
QR Payments
QR code payments are now supported across all three platforms, reflecting the 2026 reality that merchant QR payment infrastructure has expanded significantly across Pakistan. JazzCash has the most extensive merchant QR network, built over more than a decade of merchant relationships and integration with retail point-of-sale systems. Easypaisa has a strong QR presence particularly in areas with high Telenor network penetration. NayaPay’s QR network is smaller in absolute terms but growing rapidly among urban merchants.
NFC Contactless Payments
JazzCash and Easypaisa both support NFC contactless payments at equipped POS terminals, allowing tap-to-pay at retail outlets that have NFC-capable terminals. NayaPay is developing this capability. In 2026, the penetration of NFC-capable terminals across Pakistan has expanded significantly, making this a more practically useful feature than it was even two years ago.
International Remittances
Easypaisa’s 2026 partnership with Ant International WorldFirst is a significant development that enables incoming remittances from over 100 countries, making it one of the strongest platforms for families receiving money from overseas relatives. JazzCash also supports incoming international transfers through partner services. NayaPay has more limited international remittance capability compared to the two established players in this specific use case.
Freelancer Payment Integration
JazzCash and NayaPay both enable direct Payoneer withdrawals, which is essential infrastructure for Pakistan’s growing freelancer community. Easypaisa has also supported Payoneer withdrawals. In practice, JazzCash has historically had the most mature and reliable Payoneer integration, while NayaPay’s clean digital experience makes it an appealing alternative for newer freelancers. Many freelancers in 2026 maintain both a JazzCash account for Payoneer withdrawals and a NayaPay account for virtual card-based online spending.
Fees Comparison: What You Actually Pay
Understanding the fee structure of each platform prevents unexpected costs.
Transfers within the same platform
All three platforms charge zero fees for transfers between users of the same wallet. JazzCash to JazzCash is free. Easypaisa to Easypaisa is free. NayaPay to NayaPay is free.
Transfers via Raast (cross-platform and to banks)
Raast transfers are permanently free on all three platforms with no exceptions. Use Raast whenever you are sending to a bank account or a different wallet for zero cost.
Transfers outside Raast
JazzCash charges PKR 50 to PKR 200 for non-Raast interbank transfers above the free monthly threshold. Easypaisa has similar charges in this range. NayaPay charges zero for all local transfers.
Cash withdrawals from agents and ATMs
JazzCash is generally more competitive on higher-tier cash withdrawal fees. Easypaisa can be slightly more expensive in higher withdrawal slabs but maintains an extensive agent network that makes physical cash access easier in smaller cities and towns. NayaPay does not operate an agent network and cash withdrawals are through ATMs using its debit card.
Inactive account fees
Easypaisa charges PKR 50 after 12 months of inactivity. JazzCash deducts PKR 100 after six months of inactivity. NayaPay should be checked directly for current dormancy policies.
Savings profit taxation
The profit earned on your wallet balance is subject to withholding tax. For FBR filers, the tax rate is 15%. For non-filers, it is 30%. This is identical to the withholding tax on bank savings accounts and is deducted automatically before profit is credited.
Account Limits: How Much Can You Hold and Transfer?
Account limits in Pakistan’s mobile wallet ecosystem are determined by the SBP’s tiered Know Your Customer framework. Higher verification levels unlock higher transaction and balance limits.
JazzCash account limits depend on verification level. Basic CNIC-verified accounts have lower monthly transaction limits. Biometric verification unlocks higher limits appropriate for more active use.
Easypaisa in 2026 has upgraded account limits up to PKR 1,000,000 for fully verified users, which is one of the highest in the market and reflects its transition toward full digital banking status.
NayaPay as an EMI operates under specific SBP guidelines for electronic money institutions and maintains competitive limits for its target user segment. Check the NayaPay app directly for current account and transaction limits, as these have been updated as the platform has matured.
All three platforms implemented biometric verification requirements following SBP directives, which added a layer of friction to account operations but significantly strengthened security and reduced fraud.
Security: How Safe Are These Platforms?
All three platforms are regulated by the State Bank of Pakistan, which mandates minimum security standards, consumer protection requirements, and dispute resolution frameworks.
In early 2026, a notable incident occurred where multiple SadaPay users reported unauthorized deductions from their accounts. SadaPay, while not one of the three platforms covered in this article, acknowledged the issue within 48 hours and refunded all affected users within 7 days. The incident highlighted a broader principle applicable to all mobile wallets: do not store amounts you cannot afford to lose in any digital wallet. Keeping balances in mobile wallets to what you actively need for transactions, and maintaining your primary savings in a regulated bank account, is the sensible approach regardless of which platform you use.
JazzCash, Easypaisa, and NayaPay all use biometric login, PIN protection, and transaction monitoring for fraud detection. NayaPay’s virtual card feature adds an additional security layer specifically for online purchases, since exposing a virtual card rather than your main card number limits any potential breach to the specific transaction amount.
A practical security rule for all mobile wallets in Pakistan: never share your MPIN, OTP, or account details with anyone. No mobile wallet company representative will ever ask for these over a phone call or SMS. If someone claiming to represent any of these platforms asks for your credentials, it is a scam.
Learn more: Dividend Investing in Pakistan: How to Earn Regular Income from Stocks (2026)
Who Should Use Which Platform?
This is ultimately the most useful question, and the honest answer is that most Pakistanis benefit from having more than one mobile wallet given how different the strengths are.
JazzCash is best for: Users who need the widest merchant QR payment network for in-store purchases. Freelancers withdrawing from Payoneer who want the most established and mature integration. Businesses that process retail payments and need the strongest merchant ecosystem. People who want the highest savings profit rate at 14% annually on their wallet balance. Jazz mobile network subscribers who benefit from telecom-ecosystem integration.
Easypaisa is best for: Users on any network other than Jazz who want a widely accessible platform with strong nationwide agent network coverage. Families receiving international remittances, particularly from countries covered by the Ant International WorldFirst partnership. People in smaller cities and rural areas where Easypaisa’s agent network is particularly dense. Users who want a clean, simple interface that is easy to navigate even for less tech-savvy users.
NayaPay is best for: Frequent online shoppers who want virtual card protection for international platforms, subscriptions, and e-commerce purchases. Young urban professionals who value a premium digital experience and zero-fee local transfers. Freelancers who want a secondary platform for online spending after receiving Payoneer payments. Users who make multiple weekly transfers and want to avoid any inter-wallet or interbank fees entirely.
The practical recommendation for most Pakistani users in 2026 is to maintain a JazzCash or Easypaisa account as your primary mobile wallet for everyday bill payments, cash transactions, and the widest network coverage, while adding NayaPay as a secondary account specifically for online and digital spending. This combination captures the broadest range of use cases without any significant trade-offs.
The Raast Effect: Why It Changes Everything
Any discussion of mobile wallets in Pakistan in 2026 would be incomplete without acknowledging how Raast, the SBP’s instant payment system, has fundamentally changed the competitive landscape.
Before Raast, the friction of transferring money between different wallets or from a wallet to a bank account created a meaningful practical incentive to stick within one ecosystem. If you and your family were all on Easypaisa, moving to JazzCash had a real cost in terms of inter-platform transfer fees and processing delays.
Raast removes this friction entirely. Instant, free transfers between any bank account or mobile wallet on the Raast network mean you can send money from NayaPay to an HBL account or from JazzCash to an Easypaisa wallet in seconds, at zero cost. The platform ecosystem is no longer a cage that locks you in.
The practical implication is that you can choose your primary mobile wallet based purely on which features suit you best, without worrying that you will be unable to transact with people on different platforms. Raast has made the Pakistani digital payment ecosystem genuinely interoperable in a way that benefits all users.
How to Open Each Account
JazzCash: Download the JazzCash app from the Play Store or App Store. Register with your CNIC and mobile number. Basic account setup takes under 10 minutes. Biometric verification can be completed at a Jazz franchise or partner agent location to unlock higher account limits.
Easypaisa: Download the Easypaisa app. Register with your CNIC and any mobile number, since Easypaisa works with all networks. The registration and basic verification process is similarly straightforward. For higher limits, biometric verification is required at a Telenor franchise or partner agent.
NayaPay: Download the NayaPay app. Account setup is entirely digital, including CNIC scanning, a live selfie, and video KYC verification. No branch visit is required at any stage. A physical debit card can be requested through the app and delivered to your address.
Common Mistakes to Avoid With Mobile Wallets in Pakistan
Storing large balances in a mobile wallet. Mobile wallets are transactional tools, not savings vehicles. Keep only what you need for active transactions. Transfer excess funds to your bank account where deposit protection under the DPC applies.
Not using Raast for cross-platform transfers. Every time you pay a fee for an interbank or inter-wallet transfer that could have been processed through Raast for free, you are paying unnecessarily. Check whether the Raast option is available before selecting any paid transfer method.
Sharing credentials due to social engineering. Scammers posing as JazzCash, Easypaisa, or NayaPay support representatives are active and increasingly sophisticated. No genuine platform will ask for your MPIN, OTP, or password over any channel.
Not checking for dormancy fees on unused accounts. If you open a wallet and stop using it, remember the dormancy deduction that applies after a defined period. Either use the account occasionally or formally close it to avoid being quietly charged.
Assuming one platform is always best. The strengths of each platform are genuinely different. Using a single wallet exclusively because it is familiar means you are missing out on features that would make specific use cases significantly more convenient and cheaper.
Key Takeaways
Pakistan’s mobile wallet ecosystem in 2026 is one of the most practically useful and rapidly evolving financial tools available to ordinary Pakistanis across every income level and every city size. JazzCash and Easypaisa have built the scale and agent networks that make them indispensable for the broadest range of users. NayaPay has built the digital-first experience and security features that make it the preferred secondary tool for online-first users.
The right choice is not JazzCash or Easypaisa or NayaPay. It is understanding what each does best and using them accordingly. Raast infrastructure now makes running two or three accounts simultaneously a genuinely low-friction strategy that costs nothing and provides access to the best features of each platform.
Mobile wallets are no longer a substitute for banking. They are a complement to it, and in many daily use cases, they are faster, cheaper, and more convenient than traditional bank channels. Getting set up on the right platforms for your specific needs is one of the simplest and most immediately impactful financial decisions you can make in 2026.