Understanding mutual funds in Pakistan is one thing. Actually investing in them is another. Most Pakistanis who are curious about mutual funds get stuck somewhere between reading about them and placing their first investment, usually because nobody has clearly explained the practical mechanics of how to actually open an account, which platform to use, what documents you need, how a SIP works in practice, and what to check when comparing funds.
This article is the practical companion to the “What is a Mutual Fund” explainer published earlier on this site. Where that article explains what mutual funds are and how they work conceptually, this one tells you exactly how to invest in mutual funds in Pakistan in 2026, step by step, with updated information on recent SECP reforms that have made the process significantly more accessible for small investors.
Table of Contents
What Has Changed for Mutual Fund Investors in 2026
If you want to know how to invest in mutual funds in Pakistan you need to learn a few things. Before getting into the step-by-step process, two significant regulatory changes in 2026 deserve specific mention because they directly affect how you invest.
In May 2026, the Securities and Exchange Commission of Pakistan introduced major reforms to make mutual fund investing easier for small investors. The SECP said the reforms were introduced to promote financial inclusion, attract low-ticket investments, and eliminate duplication in customer verification.
The first change concerns Sehl Sarmayakari accounts, which are simplified low-risk mutual fund accounts designed specifically for small retail investors. The cumulative investment limit for these accounts has been increased from PKR 200,000 to PKR 1,000,000. Similarly, Sahulat Accounts can now facilitate investments up to PKR 3,000,000, compared to the previous limit of PKR 1,000,000. The previous annual investment caps have been removed entirely, giving investors much greater flexibility to invest and redeem without yearly restrictions.
The second major change eliminates repeated KYC documentation. Investors who already maintain accounts with regulated financial institutions including banks, microfinance banks, and electronic money institutions no longer need to complete separate Know Your Customer verification when opening Sehl and Sahulat accounts with AMCs. Your existing bank KYC data can now be reused, and identity verification already conducted through NADRA’s multi-biometric regime including facial recognition is now accepted, removing a significant friction point that previously deterred small investors.
SECP Chairman Dr. Kabir Ahmed Sidhu has set a target to increase the number of investors in Pakistan’s capital market to 2.5 million. These reforms are a direct effort to move Pakistan’s savings culture from bank deposits, real estate, and gold toward regulated investment products.
Step 1: Get Your Financial Foundation Right First
Before you invest a single rupee in any mutual fund, make sure two things are in order.
Your emergency fund should be complete. Three to six months of essential expenses should be sitting in a liquid, accessible account before you tie up any money in an investment that you might need to redeem at an inconvenient time. Mutual funds are not instant-access vehicles, particularly equity funds, and being forced to redeem during a market downturn to cover an emergency is the worst possible combination.
Your high-interest debt should be cleared. If you are carrying credit card balances or personal loans at 30% to 40% annual markup, paying those down before investing generates a guaranteed return equivalent to that markup rate. No mutual fund can consistently match that return on a risk-adjusted basis.
Once these two foundations are in place, whatever you invest in mutual funds is genuinely long-term money that you will not be forced to redeem prematurely.
Step 2: Define Your Investment Goal and Timeline
This step determines everything else. Different goals require different fund types, and investing without a clear goal leads to poor fund selection.
If you are saving for a specific goal in less than one year, a mutual fund may not be the right vehicle at all. Money market funds are appropriate for very short-term parking, but equity funds in particular can be volatile over short periods and are inappropriate for money you need within twelve months.
If your goal is two to five years away, such as a house down payment or a child’s near-term education fees, a balanced or income fund provides a reasonable combination of growth potential and stability.
If your goal is five or more years away, such as retirement, long-term wealth building, or a child’s university education that is a decade away, equity funds give you the time needed to ride out market volatility and benefit from the higher long-term returns that equity markets have historically delivered.
Write your goal down specifically. Not “I want to save some money” but “I want to accumulate PKR 3,000,000 for my child’s university fees in 10 years, starting with PKR 5,000 per month.” This specificity is what allows you to evaluate whether your chosen fund is tracking toward your goal.
Step 3: Understand Your Risk Tolerance Honestly
Your investment goal determines the time horizon. Your risk tolerance determines how much volatility you can genuinely accept during that period.
Equity funds can and do fall in value. During Pakistan’s economic stress periods, equity fund NAVs have declined significantly in short periods. If you would panic and redeem your investment during such a period, you would lock in your loss and eliminate the recovery gains that patient investors received. Honest self-assessment of how you would actually behave, not how you think you should behave, is the most valuable input to fund selection.
Conservative investors who would be uncomfortable seeing their balance fluctuate significantly should start with money market or income funds, which offer much lower volatility and more predictable returns. Growth-oriented investors with genuine long-term horizons and strong emotional tolerance for short-term swings are appropriate candidates for equity funds.
Most people sit somewhere in the middle, making balanced funds or a combination of fund types the most practical starting point.
Step 4: Choose the Right Fund Category
Pakistan’s mutual fund market, regulated by SECP and categorized in alignment with MUFAP guidelines, offers several distinct fund categories. Choosing the right category matters more than choosing the specific fund within that category.
Money Market Funds
These invest in very short-term, low-risk instruments including treasury bills and short-term government securities. They are the most stable category, offering returns broadly comparable to or slightly above bank savings account rates. They are appropriate for your short-term parking, your emergency fund top-up strategy, or as the conservative anchor in a diversified portfolio.
Income Funds
Income funds invest primarily in longer-duration fixed income instruments including government bonds, Pakistan Investment Bonds, and corporate debt instruments. They carry slightly more volatility than money market funds but offer better long-term return potential within the fixed income universe. Appropriate for conservative to moderate investors with a one to three year horizon.
Equity Funds
Equity funds invest at least 70% of their net assets in PSX-listed stocks. They carry the highest volatility of any fund category but have historically delivered the strongest long-term returns. Required minimum equity content of 70% means these funds are genuinely exposed to market movements. Appropriate for investors with a five-year or longer horizon who can tolerate NAV fluctuations without panic-redeeming.
Balanced Funds
Balanced funds split their portfolio between equities and fixed income instruments, offering a middle path. They provide meaningful growth potential from the equity portion alongside some stability from the fixed income portion. Suitable for investors who want equity exposure but are uncomfortable with a pure equity fund’s volatility.
Islamic or Shariah-Compliant Funds
Available in all of the above categories. Islamic equity funds, Islamic income funds, and Islamic money market funds all operate within Shariah guidelines, investing only in permissible assets and avoiding interest-based instruments. For investors who require Shariah compliance, Pakistan has an extensive range of Islamic fund options from most major AMCs including Al Meezan, Meezan Bank’s asset management arm, which is Pakistan’s largest Islamic AMC with over USD 262 million in assets under management and over 200,000 investors nationwide.
Index Tracker Funds
As covered in a dedicated article in this series, index tracker funds passively replicate a benchmark index like the KSE-100 or KMI-30. They typically carry lower expense ratios than actively managed equity funds and are appropriate for investors who prefer passive market exposure.
Step 5: Choose an Asset Management Company
All AMCs operating in Pakistan must be licensed by SECP. Verifying an AMC’s license before investing is a non-negotiable first step. You can verify any AMC’s license status by sending an SMS: LV followed by a space followed by the AMC’s incorporation ID to 8181. You can also verify through SECP’s JamaPunji portal at www.jamapunji.pk.
Beyond the basic license check, evaluate AMCs on the following factors.
Assets Under Management and Track Record
Larger, more established AMCs with longer track records have demonstrated their ability to manage investor funds through different market cycles. Pakistan’s oldest private sector AMC is JS Investments, established in 1995, with PKR 154.8 billion in assets under management. Al Meezan Investment Management is Pakistan’s largest Islamic AMC. HBL Asset Management, NBP Funds, UBL Fund Managers, Alfalah GHP, and Faysal Funds are among the other well-established SECP-licensed AMCs with diversified fund ranges.
Range of Fund Types
An AMC that offers equity, income, money market, balanced, and Islamic variants across multiple risk categories gives you flexibility to adjust your allocation over time without needing to move to a different company. Some investors prefer to consolidate all their mutual fund investments with one AMC for simplicity.
Expense Ratio and Total Expense Ratio
The management fee and total expense ratio of each fund directly reduce your net return. A fund charging a 2.5% annual management fee requires meaningfully higher gross performance than a fund charging 1.5% to deliver the same net return to you. Compare expense ratios among similar fund types. Even a 0.5% difference compounds to a large sum over 20 to 30 years.
Sales Load Structure
Many actively managed mutual funds in Pakistan charge a front-end load of up to 2.5% when you buy units, and some charge a back-end load when you redeem. This upfront cost reduces your starting investment immediately. Some AMCs offer zero-load options, particularly for direct online investments through their own platforms rather than through third-party distributors. Always confirm the load structure before investing.
Digital Accessibility and App Quality
In 2026, the quality of an AMC’s mobile app and online platform significantly affects your day-to-day investing experience. The ability to invest, check NAV, set up a SIP, and redeem from your phone without branch visits is a practical criterion that matters.
Step 6: Choose Your Access Route
There are three main routes through which Pakistani investors can access mutual funds.
Direct Through the AMC
Investing directly with the AMC, either through their branch, website, or mobile app, typically gives you the lowest cost access because there is no distributor commission layer added on top. Most major AMCs now offer fully digital onboarding through their apps. You complete your KYC, link your bank account, and start investing entirely from your phone.
Through a Distributor or Partner Bank
Many banks in Pakistan act as authorized distributors for multiple AMCs. If you already bank with a particular bank and that bank distributes mutual fund products, you may be able to access funds directly through your bank’s app or at a branch. This adds convenience but may include a distributor fee that increases your effective total expense ratio.
Through Aggregator Platforms
Platforms like Behtari Capital and CDC iInvest offer access to funds from multiple AMCs through a single account and interface. These platforms are useful for investors who want to compare and invest across several AMCs without maintaining separate accounts with each one. The CDC iInvest platform in particular is backed by the Central Depository Company of Pakistan and provides a credible, regulated aggregator option.
Step 7: Open Your Investor Account
The account opening process has been significantly streamlined in 2026 following SECP’s reforms. For most investors, the process is now fully digital.
Documents you will need
Your valid CNIC is the primary identity document. A clear photograph of your CNIC, front and back. A recent passport-sized photograph or a live selfie captured during digital verification. Your bank account details including your IBAN for linking the account for investments and redemptions. A Zakat exemption declaration if applicable.
The digital process for most AMCs in 2026
Download the AMC’s official mobile app or visit their website. Create an account using your mobile number. Complete the KYC process by uploading your CNIC images and completing a live selfie or facial recognition step through NADRA’s biometric verification system. If you already have a verified account with a bank or regulated financial institution, under the new SECP framework your existing KYC data can now be reused, eliminating the need to submit separate documentation. Link your bank account by entering your IBAN. Set your investment preferences and choose your fund.
The account is typically activated within one to two business days for digital applications.
Step 8: Make Your First Investment
Once your account is active, you can invest in one of two ways.
Lump Sum Investment
You transfer a one-time amount from your bank account into the fund of your choice. Most AMCs have minimum lump sum investment amounts of PKR 5,000 to PKR 10,000 for standard accounts. For Sehl Sarmayakari accounts under the new SECP framework, minimum investment requirements are as low as PKR 500 to PKR 5,000.
Systematic Investment Plan (SIP)
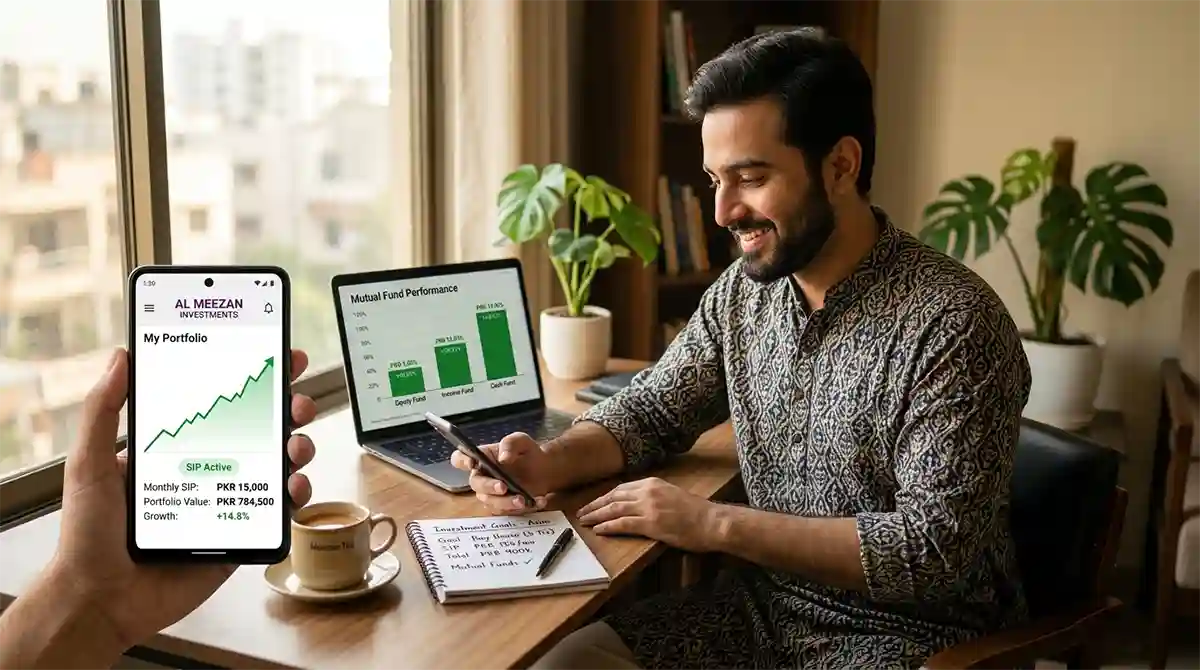
A SIP is an instruction to automatically invest a fixed amount from your bank account into your chosen fund on a specified date each month. You specify the amount, the fund, and the date. The AMC then automatically processes the investment on that date every month until you change or cancel the instruction.
SIPs are strongly recommended for most investors because they remove the decision of whether to invest each month, they apply rupee-cost averaging automatically, and they build the disciplined saving habit that is the actual foundation of long-term wealth accumulation. Most AMCs accept SIP amounts starting from PKR 1,000 to PKR 5,000 per month.
When your SIP investment is processed, units are allocated at the NAV of that day’s fund price. Your total unit holding grows every month as new units are allocated. The value of your total holding reflects the current NAV multiplied by your total units at any given time. You can also track your investment journey using this SIP calculator.
Step 9: How to Track Your Investment
After investing, tracking your fund requires understanding two core numbers.
NAV (Net Asset Value)
NAV is the price of one unit of your fund on any given day. It is calculated by dividing the total value of the fund’s portfolio by the total number of units outstanding. MUFAP publishes daily NAVs for all registered mutual funds in Pakistan on its website. Your AMC also displays your fund’s current NAV within their app.
Your current portfolio value is your total unit holdings multiplied by the current NAV. If you hold 1,000 units in a fund whose NAV today is PKR 180, your current portfolio value is PKR 180,000.
Performance vs Benchmark
Your fund’s performance should be compared against its benchmark index rather than in absolute terms alone. An equity fund that returned 15% in a year where the KSE-100 returned 25% has technically made you money but has significantly underperformed the market. A fund that returned 10% in a year where its benchmark fell 5% has delivered genuine value. Benchmark comparison data is available on MUFAP’s website and on platforms like Sarmaaya.pk.
Review your fund’s performance against its benchmark every six to twelve months. Consistent underperformance relative to benchmark over two to three years is a legitimate reason to consider switching to a different fund within the same category.
Step 10: How Redemption Works
When you want to take money out of your mutual fund, you submit a redemption request through the AMC’s app or website specifying the amount or number of units you want to redeem.
For open-end mutual funds in Pakistan, which represent the vast majority of funds available to retail investors, redemption is processed at the NAV of the redemption day. Most AMCs process same-day redemptions for requests submitted before a specified cut-off time, typically between 3:00 PM and 4:00 PM on business days. The funds are credited to your linked bank account within one to two business days following the redemption date.
Some fund types, particularly equity funds, may have a redemption period of up to two to three business days. Confirm the specific redemption timeline for your chosen fund before investing if liquidity is a priority consideration.
Back-end loads, if applicable to your specific fund, are deducted at the time of redemption. Always confirm whether your fund carries any redemption charge and under what conditions before submitting a redemption.
Comparing Mutual Funds: Key Resources
Pakistan has several reliable platforms for comparing mutual funds and tracking performance.
MUFAP (Mutual Funds Association of Pakistan) at mufap.com.pk publishes daily NAVs, fund fact sheets, and performance data for all registered mutual funds. It is the primary official source for fund comparison data.
Sarmaaya.pk is a financial research and portfolio tracker that covers PSX stocks, mutual funds, and other financial instruments. It provides performance comparisons, fund analytics, and portfolio tracking tools for Pakistani investors.
JamaPunji.pk is SECP’s official investor education portal that includes fund verification, investor guides, and complaint registration facilities.
PakFinance.pk is a more recently established platform providing fund comparison tools including a mutual fund return calculator and SIP planning tool.
Individual AMC websites and apps all publish their own fund performance data and fact sheets, which should be read alongside third-party platform data for a complete picture.
Tax Treatment of Mutual Fund Income in Pakistan
Tax implications of mutual fund investing deserve clear explanation because they vary by fund type and investor status.
Capital Gains Tax
Gains realized from redeeming mutual fund units are subject to Capital Gains Tax in Pakistan. The rate varies based on the holding period. Units held for less than one year are taxed at higher rates than units held for longer periods. Equity fund capital gains have a different tax treatment than income fund gains. SECP and FBR update these rates periodically, so always verify the current CGT structure applicable to your specific fund type before redeeming, particularly for large redemptions where the tax impact is material.
Dividend Income
Dividends distributed by mutual funds are subject to withholding tax. For FBR-registered filers, the rate is 15%. For non-filers, it is 25%. This tax is deducted at source before distribution. Maintaining your FBR filer status is important for minimizing the tax burden on mutual fund income.
Tax Credit on Investment
Investment in mutual fund schemes in Pakistan entitles investors to avail a tax credit that enhances the overall effective return on their savings. The applicable provisions under the Income Tax Ordinance allow a tax credit on investments in certain eligible mutual funds. This is a meaningful benefit that effectively reduces your income tax liability based on your mutual fund investments, and it is worth confirming the current eligibility and quantum of this credit with a tax advisor when planning your annual investments.
Common Mistakes to Avoid
Choosing a fund based on last year’s top return. The fund that delivered the highest return last year is not necessarily the best choice going forward. Evaluate performance consistency over three to five years, not just the most recent period.
Redeeming during a market dip. The most damaging mistake mutual fund investors make is redeeming an equity fund when the NAV has fallen. A falling NAV is not a reason to exit. For long-term investors, it is an opportunity to accumulate more units at lower prices through continued SIP investment.
Not comparing total expense ratios. The management fee and expense ratio differences between similar funds compound significantly over time. A fund charging 0.5% more per year than an equivalent alternative costs you tens of thousands of rupees over a decade on a meaningful investment.
Treating a money market fund as equivalent to an equity fund. Both are mutual funds but they are fundamentally different products with entirely different risk and return profiles. Understand which category you are investing in and what that means for expected volatility and return.
Ignoring the Zakat deduction. If you are Zakat-eligible and have not submitted a Zakat exemption affidavit to your AMC, Zakat will be deducted automatically from your fund balance on the designated Zakat date each year. Submit the exemption affidavit during account opening if you are exempt.
Key Takeaways
Investing in mutual funds in Pakistan in 2026 is genuinely more accessible than at any previous point in the country’s investment history. SECP’s May 2026 reforms, which eliminated redundant KYC requirements and raised Sehl account limits to PKR 1,000,000, reflect a deliberate regulatory push to bring more Pakistanis into the formal investment ecosystem.
The process from decision to first investment can now be completed entirely on your phone in under an hour for most fund types and AMCs. What used to require branch visits, paper forms, and weeks of processing has been reduced to a digital form, a live selfie, a bank account link, and a SIP setup.
The hardest part is not the process. The hardest part is the discipline to keep your SIP running when markets feel uncertain, to resist redeeming when NAVs fall, and to stay focused on your original goal rather than reacting to whatever the market is doing in any given month.
The mechanics are now simple. The discipline is yours to build.