
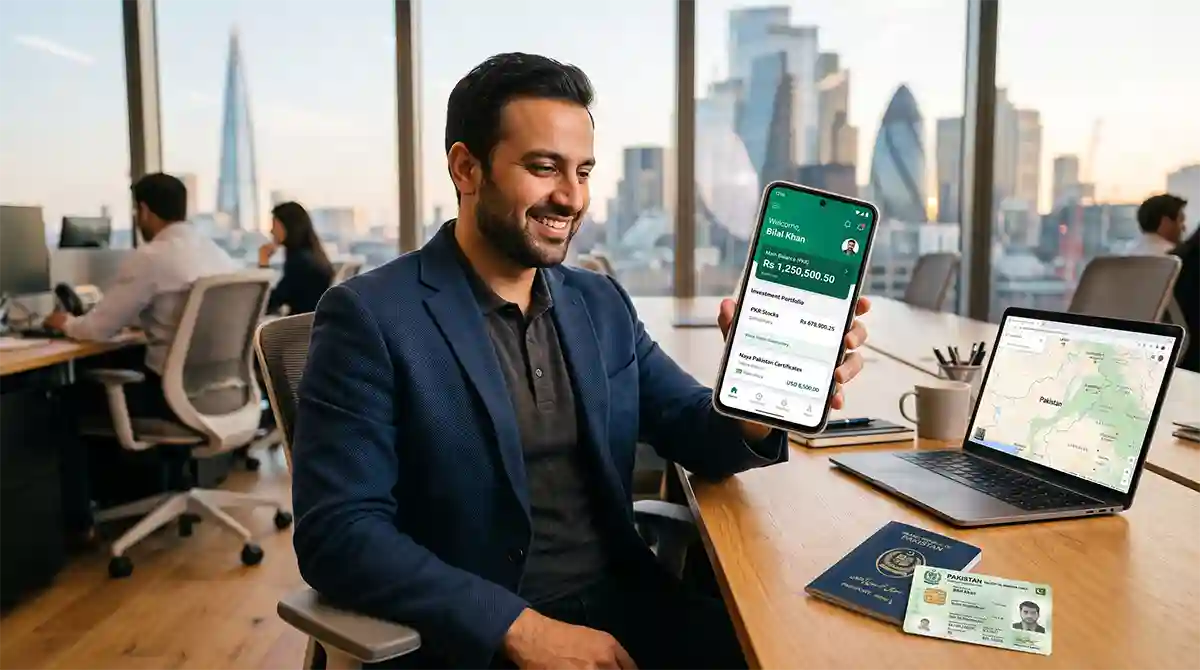
Approximately 9 million Pakistanis live abroad, and almost every one of them maintains some form of financial connection to Pakistan. They send remittances to support families, dream of owning property back home, and want to keep part of their savings invested in the country they grew up in. For a long time, doing any of this properly was genuinely difficult. Moving money in required navigating complex foreign exchange regulations. Moving money out required prior SBP approval for significant amounts. Opening a bank account meant a branch visit in Pakistan. Investing in stocks or government securities from abroad was practically impossible for most ordinary individuals. So I’ll share with you how to invest in Pakistan as an overseas Pakistani.
The Roshan Digital Account changed all of this. Launched by the State Bank of Pakistan, it is the single most important development for overseas Pakistani investors in the country’s recent financial history, and understanding how it works, what you can invest in through it, and how to get started is the foundation of every overseas Pakistani’s investment strategy for Pakistan in 2026.
This guide covers the complete picture: the RDA itself, the investment options it unlocks, how to access the Pakistan Stock Exchange from abroad, how to invest in National Savings and mutual funds, real estate access, and the tax and repatriation considerations every overseas Pakistani investor needs to understand before committing funds.
Table of Contents
Who This Guide Is For
Before I discuss How to Invest in Pakistan as an Overseas Pakistani you must know that this guide is relevant for three categories of people.
Non-Resident Pakistanis (NRPs) who are Pakistani nationals living abroad, whether in the UAE, Saudi Arabia, UK, USA, Canada, Australia, or elsewhere, and who want to invest their savings back in Pakistan.
Pakistan Origin Card (POC) holders, who may be former Pakistani nationals who have taken foreign citizenship, or people of Pakistani origin, and who want to maintain financial participation in Pakistan’s economy.
Resident Pakistanis with assets declared abroad, who are technically resident in Pakistan but have legitimately declared foreign-held assets in their FBR wealth statements and want to manage those assets through a formal framework.
Step 1: Get Your Identity Documentation Right
Before any investment account, banking relationship, or financial product in Pakistan, the foundation is your identity documentation. For overseas Pakistanis, this means getting the right identity document sorted first.
NICOP (National Identity Card for Overseas Pakistanis)
NICOP is the primary identity document for Pakistani nationals living abroad. It functions like a CNIC for domestic use but is specifically issued for overseas Pakistanis by NADRA. Most Pakistani banks, including all Roshan Digital Account partner banks, accept NICOP as the primary identity document for account opening from abroad.
NICOP can be applied for online through NADRA’s overseas application portal, through Pakistani embassies and consulates, or through NADRA’s authorized centers in countries with significant Pakistani diaspora populations. Processing typically takes several weeks. If you do not currently have a NICOP and want to begin investing in Pakistan, obtaining one is the single most important first step.
POC (Pakistan Origin Card)
POC is designed for people of Pakistani origin who are not Pakistani nationals, including former Pakistani citizens who have taken foreign citizenship, and certain dual nationals. POC holders can access RDA and most Pakistan investment products, though some products have specific eligibility rules that distinguish between NRPs and POC holders. Verify the specific eligibility of any product you are interested in against your documentation type.
CNIC for Pakistanis Who Have Not Changed to NICOP
Some overseas Pakistanis still hold a valid CNIC rather than a NICOP. Depending on the bank and product, a valid CNIC may be accepted, though most RDA partner banks strongly prefer or require NICOP for overseas applicants. Check with your chosen bank.
Step 2: Open a Roshan Digital Account
The Roshan Digital Account is your gateway to virtually every regulated investment channel in Pakistan as an overseas investor. Think of it not as just a bank account but as an investment access platform that unlocks stocks, government securities, National Savings, mutual funds, and real estate financing from wherever you are in the world.
What is the RDA exactly?
The RDA is a State Bank of Pakistan initiative launched to enable non-resident Pakistanis and eligible individuals to open and operate Pakistani bank accounts remotely, without any branch visit in Pakistan. It is available in both PKR and foreign currency denominations including USD, GBP, and EUR depending on the specific bank. Both conventional and Islamic banking variants are available.
The account can only be funded by foreign remittances originating from your own overseas bank account through formal banking channels. Local deposits within Pakistan are not permitted except for investment proceeds and returns from investments made through the account. This structure ensures that money flowing into Pakistan through the RDA system is genuinely new foreign exchange rather than domestic funds using the framework as a tax or regulatory workaround.
Which banks offer RDA in 2026?
The RDA is available at a wide range of Pakistani banks. Major participating banks include HBL, Meezan Bank, UBL, MCB, Bank Alfalah, Bank AL Habib, Standard Chartered Pakistan, Faysal Bank, Allied Bank, and Bank of Punjab among others. Each bank has its own application portal and slightly different features, account currency options, and investment product access.
Meezan Bank offers Roshan Digital Account in both Current and Savings account variants under Islamic concepts of Qard and Mudarabah, with account options in PKR, USD, GBP, and EUR. Standard Chartered Pakistan offers RDA with a live conversion facility and an SCB credit card option linked to the RDA for cardholders who maintain a lien. Bank AL Habib is noted as a leading RDA service provider with insurance coverage for account holders equivalent to the last 90 days average balance up to a maximum PKR 2,000,000 equivalent.
How to open an RDA
The process is entirely digital. You do not visit a branch in Pakistan or a Pakistani embassy anywhere. You go to your chosen bank’s website or app, complete the digital application form, upload scanned copies of your NICOP or POC, your passport, and supporting documents including proof of profession and source of funds such as salary slips, rental agreements, or business income proof. The bank reviews your application and responds typically within 24 to 48 hours. Once approved, you fund the account by remitting from your overseas bank account to the RDA.
Documents typically required across most banks include: scanned copy of NICOP or POC, scanned copy of passport first two pages, proof of overseas address, proof of profession or source of income, and a signature on a white paper or digital signature depending on the bank’s process.
Investment Option 1: Naya Pakistan Certificates
Once your RDA is funded, the most straightforward and widely used investment option for overseas Pakistanis is the Naya Pakistan Certificate (NPC), Pakistan’s government-issued investment certificate specifically designed for non-resident investors.
NPCs are issued by the State Bank of Pakistan on behalf of the Government of Pakistan, which means they carry the same sovereign guarantee as domestic National Savings instruments. They are available in both conventional and Islamic variants. The Islamic NPC, known as the Islamic Naya Pakistan Certificate (INPC), is structured on Shariah-compliant principles.
NPCs are available in multiple currencies, which is a significant advantage over domestic National Savings instruments that are PKR-denominated only.
PKR-denominated NPCs offer returns linked to Pakistan’s interest rate environment. The PKR NPC return is competitive with domestic fixed deposits and National Savings rates, giving overseas Pakistanis access to Pakistan’s relatively high PKR interest rates.
USD-denominated NPCs currently offer approximately 8.25% annual return in USD. For overseas Pakistanis who want exposure to Pakistan’s government returns while holding in a stable foreign currency, the USD NPC is genuinely attractive, delivering a dollar return well above what most developed market savings accounts offer while benefiting from the Government of Pakistan guarantee.
NPCs are accessible through your RDA internet banking portal. After opening your RDA and setting up your investment portal password, you navigate to the NPC section and submit your investment instruction. The investment is deducted from your RDA balance and your NPC holding is confirmed digitally.
Investment Option 2: Pakistan Stock Exchange (PSX) Through Roshan Equity Investment Account
Overseas Pakistanis can now invest directly in PSX-listed stocks, ETFs, bonds, and government securities through the Roshan Equity Investment Account (REIA), a dedicated facility integrated with the RDA system.
The REIA is the first and only investment account through which overseas Pakistanis can open a stock market investment account through their Roshan Digital Account. It provides access to a wide array of conventional and Shariah-compliant stocks, bonds, ETFs, and government securities traded on PSX.
How to open a Roshan Equity Investment Account
Log in to your Roshan Digital Account internet banking at your RDA bank. Navigate to NRP Services and select Pakistan Stock Exchange. Select your preferred brokerage house from the list of designated brokers. Accept the disclaimer and terms and conditions. The broker selected will set up your CDC sub-account linked to your RDA.
Designated brokerage houses for RDA clients include AKD Securities Limited, Arif Habib Limited, JS Global Capital Limited, KTrade Securities Limited, BMA Capital Management Limited, Abbasi and Company, Alfalah CLSA Securities, Darson Securities, MRA Securities, Munir Khanani Securities, Topline Securities, and Zahid Latif Securities.
How trading works for RDA account holders
After your REIA is set up, you transfer funds from your RDA bank account to your CDC cash account. The broker’s commission is paid by CDC from the transferred amount. There are no additional CDC setup fees for overseas Pakistani RDA clients. After funding your CDC account, you can buy and sell through your broker’s trading app, just as domestic PSX investors do.
When you sell, proceeds are credited to your CDC account. You can then instruct CDC to transfer these proceeds back to your RDA, and from there you can either reinvest or repatriate the funds to your overseas account without requiring any prior approval from the bank or SBP, which is a significant liberalization from the pre-RDA environment.
For Meezan Bank RDA holders who want Shariah-compliant stock market exposure, the account specifically facilitates investment in Shariah-compliant shares and Sukuk listed on PSX, with the Islamic brokerage process handled through the Meezan portal.
Investment Option 3: Mutual Funds
Overseas Pakistanis can invest in SECP-registered mutual funds in Pakistan through two primary routes.
Through their RDA bank’s mutual fund access: Several RDA partner banks provide direct access to mutual fund products within their own app or internet banking portal. HBL and Bank Alfalah both offer mutual fund investment access through their RDA portals, allowing overseas Pakistanis to invest in their associated AMC’s funds directly within the same banking relationship.
Through the CDC iInvest platform: The Central Depository Company of Pakistan’s iInvest platform provides access to multiple AMCs through a single account, accessible to overseas Pakistani investors who have linked their CDC account through the RDA framework.
Through AMC platforms directly: Overseas Pakistanis with a Pakistani bank account, including an RDA, can in many cases access AMC mobile apps and websites directly to invest in mutual funds, using their bank account as the funding source.
Mutual fund investments for overseas Pakistanis are particularly well suited for equity fund SIPs, where a fixed monthly amount is invested automatically, building a growing portfolio over time through rupee-cost averaging. Al Meezan’s Shariah-compliant fund range, accessible through its app, is particularly popular among overseas Pakistani investors who want Islamic equity exposure.
Investment Option 4: Government Bonds and Securities
Beyond NPCs, overseas Pakistani RDA holders can access Pakistan’s broader debt securities market through their RDA investment portal, including T-bills (Treasury Bills), PIBs (Pakistan Investment Bonds), Sukuk, and other government-registered debt instruments.
These instruments offer varying tenors and yields across the government yield curve, allowing more sophisticated investors to position their fixed income allocation based on their view of Pakistan’s interest rate trajectory. For most overseas Pakistani investors beginning their investment journey, the NPC is a simpler and equally government-backed starting point, but the broader debt securities access is available for those who want it.
Investment Option 5: Real Estate
Real estate investment through RDA is available but comes with important structural rules that overseas Pakistani investors must understand clearly before committing funds.
Overseas Pakistanis can purchase residential and commercial property in Pakistan using RDA funds. The purchase transaction requires that funds be released directly from the RDA to the seller or the property developer through formal banking channels. You cannot withdraw RDA funds to use in an informal property purchase arrangement.
After purchasing property through RDA, rental income, sale proceeds, and appreciation gains can be repatriated back to your overseas account through the same formal channels. However, repatriation of capital above the amount originally invested is generally restricted for the first three years from the initial investment.
Car financing for overseas Pakistanis through the RDA is also available. Bank Alfalah’s Roshan Apni Car facility and HBL’s equivalent product allow overseas Pakistani RDA holders to finance a vehicle in Pakistan for family use, with down payment requirements as low as 15% or 0% equity for lien-based financing structures where the loan is secured against the RDA balance.
Standard Chartered Pakistan offers home financing through its Saadiq facility for RDA holders in UAE, Bahrain, Saudi Arabia, Qatar, Oman, Singapore, and Malaysia, with entirely digital processing without requiring the applicant to visit Pakistan.
Repatriation: Getting Your Money Back Out
This is the question every overseas Pakistani investor thinks about before committing funds. The RDA framework provides the most liberal repatriation terms Pakistan has ever offered to overseas investors.
Funds that were brought into Pakistan through formal channels via your RDA can generally be repatriated without any prior approval from the bank or SBP. You give instructions to your bank to transfer funds from your RDA to your overseas account and the transaction is processed. This represents a fundamental change from the pre-RDA era when significant outward transfers required formal SBP approval.
Investment returns, dividends from PSX holdings, mutual fund redemption proceeds, NPC maturity payments, and sale proceeds from assets acquired through the RDA can all be channeled back through the RDA and repatriated. The key principle is that the money must flow through formal banking channels and be traceable to legitimate investment activity.
Restrictions apply specifically to real estate, where the investment must be held for a minimum period before full capital repatriation, and to certain large transfers that may still require documentation of the source of funds.
Tax Considerations for Overseas Pakistani Investors
Tax treatment for overseas Pakistani investors involves both Pakistani tax obligations and potential obligations in your country of residence, and getting clarity on both sides before investing significantly is genuinely important.
Pakistani tax obligations
Capital gains from PSX investments are taxable in Pakistan at rates depending on the holding period. Dividend income from PSX investments is subject to withholding tax at 15% for filers and 25% for non-filers. Profit from NPCs and term deposits is subject to withholding tax, with filer rates lower than non-filer rates.
A key question for overseas Pakistanis is whether they are considered tax residents of Pakistan for a given year. Under Pakistani tax law, residency is generally determined by the number of days spent in Pakistan in a tax year. Non-residents and those who meet specific criteria as overseas Pakistanis may receive preferential treatment on certain income types.
Double taxation treaties
Pakistan has double taxation agreements with a number of countries where significant Pakistani diaspora communities live, including the UK. Under such treaties, taxes paid in Pakistan on Pakistani-source income can often be offset against tax obligations in your country of residence, preventing the same income from being fully taxed twice. The specific terms vary by country and by income type. Consulting a qualified tax advisor familiar with both Pakistani and your residence country’s tax law is strongly recommended before making significant investment commitments through an RDA.
FBR registration as a filer
Overseas Pakistanis who have Pakistani-source income are generally required to file annual income tax returns in Pakistan. Being a registered FBR filer also reduces withholding tax rates on investment income, as covered throughout this series. FBR’s IRIS portal allows online tax return filing from abroad.
Practical Tips for Getting Started
Start with the NICOP if you do not have one. Everything else flows from having the right identity documentation.
Choose your RDA bank based on the investment products you actually want access to. If your primary goal is Shariah-compliant stock market investment, Meezan Bank’s RDA infrastructure for Islamic PSX access may suit you best. If you want the broadest range of investment options including property financing, car financing, and multiple currency accounts, Bank AL Habib, HBL, and Bank Alfalah all offer comprehensive RDA ecosystems.
Start with NPCs for your initial funds while you take time to understand the other investment options. NPCs are the simplest, government-guaranteed starting point that gives you an immediate return on your deposited funds while you complete the setup of a brokerage account or mutual fund access.
Use the official channels for every transaction. The entire value of the RDA framework for overseas Pakistani investors is its legal clarity and repatriation freedom. Operating outside formal channels, even for apparently small amounts, compromises your compliance standing and can create complications when you want to repatriate funds later.
Consult a tax advisor in both Pakistan and your country of residence before making your first significant investment. This investment pays for itself many times over through avoided tax mistakes that are difficult and expensive to unwind after the fact.
Summing Up
Investing in Pakistan as an overseas Pakistani has genuinely never been more accessible than it is in 2026. The Roshan Digital Account framework has solved the core problem that historically prevented overseas Pakistanis from participating in their home country’s investment market: the inability to open a bank account, move money in and out through formal channels, and access regulated investment products remotely.
Pakistan’s stock market, government securities, National Savings instruments, mutual funds, and real estate are all now accessible from London, Dubai, Toronto, or Sydney with nothing more than a smartphone, your NICOP, and a remittance from your overseas bank account.
The infrastructure is there. The investment options are competitive. The repatriation rules are more liberal than they have ever been. The remaining decision is yours: which products align with your goals, your timeline, and your risk tolerance, and how to structure an investment plan in Pakistan that complements your financial life wherever you currently live.
That decision is easier to make well when you understand the full range of what is available. Now you do.

amazing to know all these. I’m going to Australia and the. I’ll use these options.
Thanks for the feedback.
what a great advice sir. thanks for the whole information.
Thanks for considering it valuable.