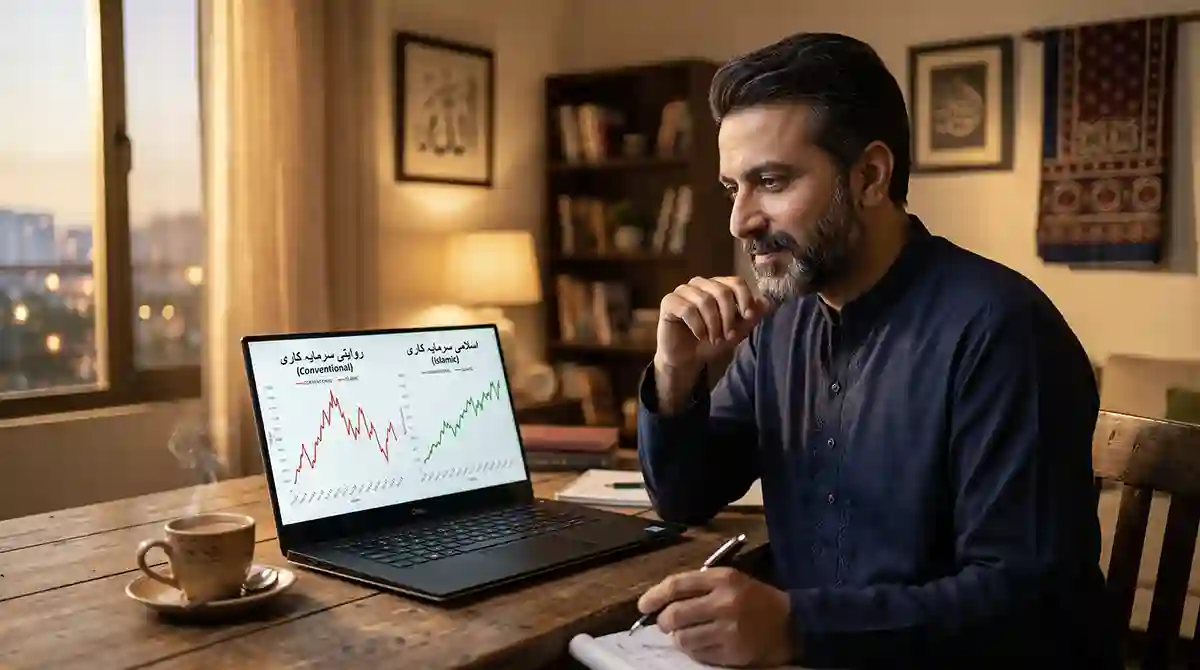
A relative of mine checks the KSE-100 every evening the way most Pakistanis check the weather, and for years he genuinely believed that number represented the entire Pakistan Stock Exchange. When his own equity mutual fund, which happened to be Islamic and therefore benchmarked against a completely different index, underperformed the KSE-100 headline during a quarter when conventional banking stocks surged, he was convinced his fund manager had done something wrong.
Nothing had gone wrong at all. He was simply comparing two fundamentally different baskets of companies, selected by two different sets of rules, and assuming they should move identically. Here you will deeply understand the PSX Indices like KSE-100, KSE-30, KMI-30.
This confusion is genuinely common, and it matters because the index you compare your own investments against should actually match what you own. This guide explains exactly how PSX’s major indices are built, what distinguishes them from each other, and which one is actually relevant to your specific investment goals.
Table of Contents
The Concept Every PSX Index Shares: Free-Float Methodology
Before covering the individual indices, understanding this one shared technical concept resolves most of the confusion around how they work. PSX shifted all of its major indices to free-float market capitalization methodology, a construction approach that counts only the shares of a company genuinely available for public trading, excluding shares locked in by promoters, the government, or other strategic holders who are not actively trading them.
This matters because a company’s total market capitalization and its free-float market capitalization can differ substantially. A company where the founding family retains 60 percent ownership contributes to an index only through the remaining 40 percent that is genuinely available for the public to buy and sell, since that is the portion whose price movements actually reflect real market trading activity.
PSX’s indices also use an adjustable Divisor, a technical mechanism that absorbs the effect of corporate actions, bonus shares, rights issues, and similar events, so that the index level reflects genuine price movement rather than an artificial jump or drop caused purely by a change in the number of shares outstanding.
KSE-100: The Headline Number Everyone Knows
The KSE-100 Index was launched in November 1991 with a base value of 1,000 points, and it remains PSX’s most recognized and widely referenced benchmark. It comprises 100 companies selected specifically on the basis of sector representation and highest free-float capitalization, meaning the selection process deliberately ensures the index reflects PSX’s major industry sectors proportionally, not simply the 100 largest companies regardless of sector. The index captures roughly 80 to 85 percent of PSX’s total free-float market capitalization, making it a genuinely representative proxy for the exchange’s overall direction.
PSX recomposes the KSE-100’s constituents twice yearly, effective the first working day of April and October, dropping and adding companies as their relative size and free-float characteristics change. The index exists in two variants: the standard KSE-100, which is a total return index incorporating the effect of dividends, and the KSE-100 PR, which measures price movement alone without dividend reinvestment, a distinction worth knowing if you are comparing your own portfolio’s total return, dividends included, against the headline index figure.
The KSE-100’s real historical volatility is worth seeing in actual numbers, not just description. The index reached an all-time high of 14,814 points on December 26, 2007, the day before a major political event shook the market. It lost a third of its value by mid-2008 amid political pressure. It fell roughly 62 percent from a January 2020 high of 43,218 to 27,200 by March 25, 2020, during the COVID-19 shock.
It reached a record 83,531.96 points on October 4, 2024. And in early 2026, following the historic highs discussed in the long-term stock investing article in this series, the index recorded its single largest-ever one-day decline, losing 16,089 points, or 9.57 percent, in a single session before closing at 151,973 points, part of the broader Q1 2026 correction driven by the global oil shock covered in that same article.
This history is precisely why the long-term investing discipline covered throughout this series matters more than reacting to any single day’s headline number.
KSE-30: The Liquidity-Focused Index
Launched in September 2006, the KSE-30 Index also uses free-float methodology but applies a genuinely different selection criterion from the KSE-100: rather than selecting companies by sector representation and size, KSE-30 specifically tracks the top 30 most liquid companies listed on PSX, liquidity meaning how actively and easily a stock’s shares actually trade on any given day. Like the KSE-100, it is recomposed twice yearly.
This distinction matters practically for anyone considering an ETF or index fund tracking this benchmark, as covered in the index funds and ETFs article in this series, where UBLPETF specifically tracks the KSE-30. Because the KSE-30 prioritizes trading liquidity rather than sheer size or sector balance, it tends to concentrate more heavily in PSX’s most actively traded large-cap names, which can produce a somewhat different, often more bank-and-energy-heavy, composition than the more sector-diversified KSE-100.
KMI-30: Pakistan’s Shariah-Compliant Benchmark
The KMI-30 Index, also known as the KSE-Meezan Index, was launched on September 2, 2008, with a base period of June 30, 2008, developed jointly by PSX and Al-Meezan Investment Management specifically to track the 30 most liquid Shariah-compliant companies listed on the exchange. As covered in the mutual fund investing and Sukuk articles in this series, this index serves as the primary benchmark for Islamic equity funds and the Shariah-compliant PSX-listed ETFs, including MZNPETF and MIIETF discussed in the index funds article.
The KMI-30 carries one genuinely distinctive structural feature worth knowing: it applies a 12 percent cap on the weight of any individual company within the index. This is a deliberate diversification safeguard, preventing any single Shariah-compliant company, however large, from dominating the index’s overall movement the way an uncapped free-float index might allow. This cap is precisely why the relative’s confusion at the start of this article could genuinely occur: if conventional banking stocks, which are not Shariah-compliant and therefore excluded from KMI-30 entirely, drove a particular quarter’s KSE-100 gains, an Islamic fund benchmarked against KMI-30 would show no exposure to that specific move at all, through no fault of the fund manager.
ALLSHR: The Broadest Benchmark
The KSE All Share Index, commonly abbreviated ALLSHR, captures essentially the full universe of PSX-listed companies rather than a curated subset of 30 or 100. Where the KSE-100, KSE-30, and KMI-30 are all deliberately narrowed selections designed to be trackable, liquid benchmarks, ALLSHR exists specifically to represent the market in its entirety, making it the most comprehensive single gauge of overall PSX performance, even though its breadth makes it less commonly used as a direct investment product benchmark compared to the more concentrated indices above.
The PSX Dividend 20: A Fifth Index Worth Remembering
As covered in detail in the dividend investing article earlier in this series, PSX also maintains the PSX Dividend 20 Index, launched in 2022, which tracks the top 20 dividend-paying companies at PSX based on trailing 12-month dividend yield rather than size, liquidity, or Shariah compliance. For an income-focused investor specifically, as discussed in that article, this is the most directly relevant benchmark to measure a dividend-focused portfolio against, rather than the broader growth-oriented KSE-100.
Which Index Actually Matters for You
| Your Situation | The Relevant Index |
|---|---|
| You hold a diversified conventional equity mutual fund or a broad PSX stock portfolio | KSE-100 |
| You hold shares in UBLPETF or want the most liquid, actively traded large-cap exposure | KSE-30 |
| You hold an Islamic equity fund, Sukuk-adjacent products, or Shariah-compliant ETFs like MZNPETF | KMI-30 |
| You want to measure overall market breadth beyond a curated subset | ALLSHR |
| You specifically built a dividend-focused income portfolio, as covered in the dividend investing article in this series | PSX Dividend 20 |
Common Mistakes Pakistani Investors Make
Comparing an Islamic fund’s performance against the KSE-100 headline figure. As the opening story illustrates directly, this is an apples-to-oranges comparison whenever conventional financial sector stocks, excluded entirely from KMI-30, are driving the broader market’s movement; the correct benchmark for a Shariah-compliant portfolio is KMI-30, not KSE-100.
Assuming the KSE-100’s 100 constituents are simply “the 100 biggest companies.” As explained above, the actual selection criterion combines sector representation with free-float capitalization, meaning the specific companies included reflect a deliberate sector-balancing methodology, not a pure size ranking.
Not understanding that free-float methodology means a company’s index weight does not necessarily match its total market value. A company with significant promoter or government lock-in can have a much smaller index weight than its total market capitalization alone would suggest, since only the genuinely tradeable portion counts.
Treating a single day’s dramatic index move, like the historic March 2026 single-day decline described above, as a signal to abandon a long-term investment plan, rather than the kind of short-term volatility the long-term stock investing article in this series specifically addresses as part of equity investing’s normal character.
Conclusion
The KSE-100 is genuinely the right number to check if you want a quick read on PSX’s overall direction, but it is only one of several distinct, rules-based indices, each constructed with a different selection criterion and serving a different investor’s specific needs.
Understanding whether your own portfolio should be measured against KSE-100, KSE-30, KMI-30, ALLSHR, or the PSX Dividend 20 is not a technical formality; it is the difference between accurately judging your own investment performance and drawing the wrong conclusion entirely, exactly the confusion that led my relative to doubt a fund manager who had, in fact, done nothing wrong at all.
Further reading and official sources:
- Pakistan Stock Exchange: official index methodology brochures for KSE-100, KSE-30, and KMI-30: psx.com.pk