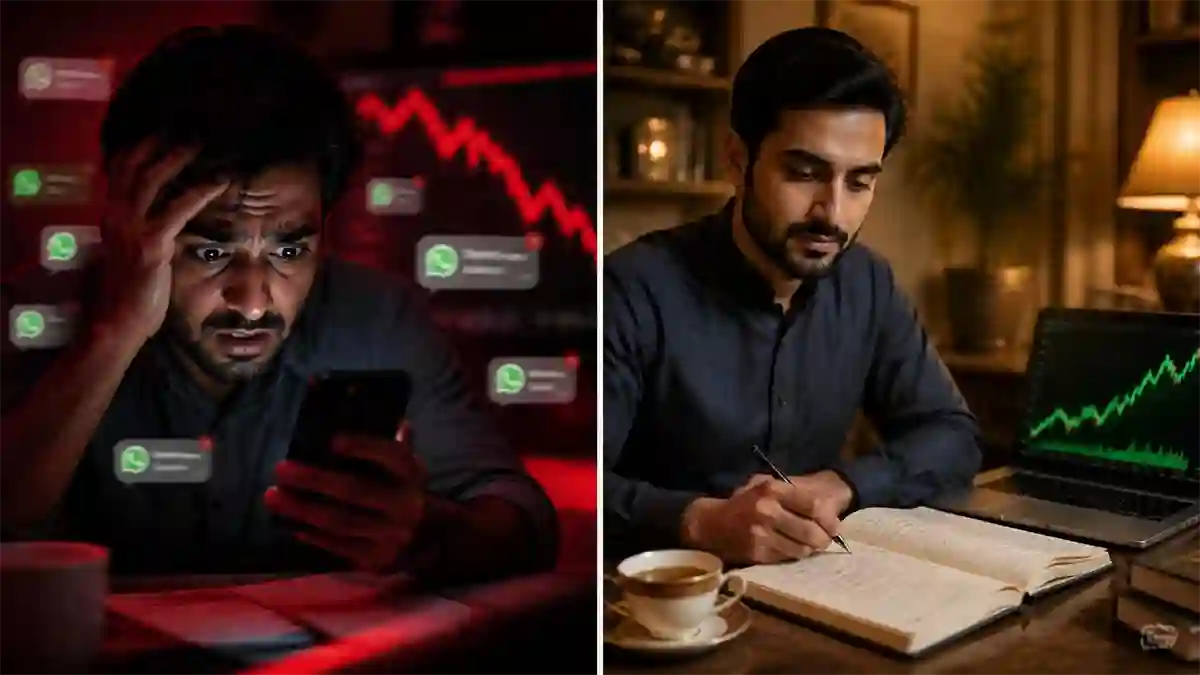
There is a question I have asked many Pakistani investors over the years: why did you buy that stock? The answers are almost never “because I analyzed the company’s earnings and found it undervalued.” They are more often something like “my cousin told me it was about to go up,” or “everyone in the WhatsApp group was buying it,” or “I saw it had already gone up 40% and I didn’t want to miss out.” So, here you will learn why Pakistani investors make bad decisions and how to stop.
These are not the decisions of unintelligent people. They are the decisions of intelligent people who are being influenced by psychological forces they do not recognize. That gap between how investors think they make decisions and how they actually make them is what the field of behavioral finance studies, and for Pakistani investors operating in the PSX environment, it is one of the most practically important areas of knowledge available.
A 2026 study published in the Advance Journal of Econometrics and Finance examined irrational investor behavior at the Pakistan Stock Exchange and concluded that psychological and emotional factors play a significant role in increasing PSX volatility, and that behavioral factors are essential in explaining market dynamics in emerging economies where financial literacy is relatively low and market inefficiencies are prevalent. In plain terms, Pakistani investors are consistently making predictable psychological mistakes that cost them money, and the research confirms it.
This article names those mistakes, explains the psychology behind each one, and gives you the specific habit changes that protect you from them.
Table of Contents
What is Behavioral Finance?
Before learning why Pakistani investors make bad decisions you need understand Behavioral Finance. Traditional finance theory assumes that investors are rational. They gather information, assess it objectively, calculate expected returns and risks, and make decisions that maximize their financial outcomes. The market, in this view, is efficient because all available information is already reflected in prices.
Behavioral finance challenges this assumption. It studies the systematic ways in which real human investors deviate from rational decision-making due to cognitive biases, emotional reactions, and social influences. The central insight is that these deviations are not random. They are predictable, recurring, and consistent enough to be named, studied, and anticipated.
For Pakistani investors, this matters enormously. PSX is a retail investor-driven market with social media-driven volatility. WhatsApp groups and closed social networks transmit investment tips, fear, and enthusiasm in real time, creating the exact environment where behavioral biases cause the most damage.
Learn more: Small Business Ideas in Pakistan with Low Investment (2026 Updated)
Bias 1: Herd Mentality
Of all the behavioral biases that affect Pakistani investors, herd mentality may be the most visible and the most costly.
Herd mentality is the tendency to follow what the crowd is doing rather than making independent judgments. When everyone around you is buying a stock, it feels rational to buy it too. When everyone is selling, it feels dangerous to hold. The psychological drivers are well documented: Fear of Missing Out when everyone else appears to be profiting, a sense of safety in numbers during uncertain times, and the social proof effect where large-scale group behavior appears to validate a decision.
Herd mentality was identified as the most significant behavioral bias affecting investment decision-making in a CFA Institute survey, affecting 34% of investment decisions among respondents globally. In Pakistan’s context, where investment decisions are heavily influenced by social networks, family conversations, and WhatsApp groups, the effect is likely even more pronounced.
The practical damage herd mentality causes is straightforward: it drives investors to buy after significant price rises, when stocks are expensive, and to sell after significant falls, when stocks are cheap. It is the mechanical engine behind the buy high, sell low pattern that destroys so many retail investors’ returns across cycles.
PSX’s own investor education materials specifically warn against herd mentality, noting that the stock market is driven by two emotions: greed and fear. People are usually caught up in boom hype and pay beyond the worth of shares. In bear markets, fear dominates and people sell at the worst possible moments.
How to protect yourself: Make every investment decision based on your own research and your own investment plan before consulting what others are doing. If your primary reason for buying a stock is that people in your network are excited about it, that is not a research-based reason. Write down the specific reason you are buying any investment before you buy it. If you cannot articulate a logical reason beyond “everyone is buying it,” do not buy it.
Bias 2: Overconfidence
Overconfidence is the tendency to overestimate the accuracy of your own judgments and the quality of your own information. Research consistently shows that most investors believe they are above-average stock pickers, which is mathematically impossible for the majority.
In the Pakistani context, overconfidence manifests in specific ways. An investor who made money on two or three trades in a rising market concludes they have developed a skill for picking stocks. They increase position sizes, take more concentrated bets, and reduce the research and caution they applied when they were newer to investing. When the market turns, the same decisions that looked like skill in a bull market are revealed as luck, and the consequences are more severe because position sizes have grown.
A 2024 study on behavioral biases at PSX found that overconfidence shows a statistically significant impact on investment decisions among Pakistani retail investors. Overconfident investors trade more frequently, which generates higher transaction costs and taxes, and they take on higher concentration risk than their actual edge justifies.
The psychology is well understood. A few successful trades create a narrative of personal skill. This narrative is reinforced every time a trade works out and discounted every time it does not, because losses are mentally attributed to bad luck while gains are attributed to ability. This asymmetric attribution is one of the most reliably documented cognitive distortions in investment decision-making.
How to protect yourself: Track your investment decisions systematically, including your reasoning at the time of purchase and the actual outcome. Honest tracking over twelve to twenty-four months gives you a realistic picture of whether your stock picking is adding value or whether market conditions were doing the work. Reduce concentration in any single position to a level where being wrong about it does not damage your overall portfolio significantly.
Bias 3: Loss Aversion
Loss aversion is the tendency to feel the pain of a loss more intensely than the pleasure of an equivalent gain. Research in behavioral finance has documented this asymmetry extensively. The emotional impact of losing PKR 10,000 is roughly twice as powerful as the satisfaction of gaining the same amount.
For Pakistani investors, loss aversion creates two specific patterns that are financially damaging.
The first is holding losing positions too long. When a stock has fallen in value, selling it feels like confirming the loss. As long as you hold it, there is still hope of recovery and the loss remains theoretical rather than realized. This mental accounting leads investors to hold fundamentally deteriorating businesses for years, hoping for a recovery that may never come, while the capital could be deployed more productively elsewhere.
The second is selling winning positions too quickly. Because a gain in hand feels more certain and comfortable than a potential future gain, there is a strong pull to take profits early. The result is that winning positions are cut short while losing positions are extended, which is the exact opposite of the investment approach that generates strong long-term returns.
A 2026 research study specifically confirmed that irrational investor behavior driven by emotional factors including loss aversion plays a crucial role in increasing volatility in the PSX. The combined effect of many investors simultaneously refusing to sell losers and rushing to sell winners creates market price distortions that rational investors can exploit but behavioral investors create at their own expense.
How to protect yourself: Before buying any investment, decide in advance under what conditions you would sell it. If the stock falls X percent, or if the underlying business deteriorates in specific ways, you sell. Having this rule in place before you are emotionally attached to a position makes it far easier to follow through. Separate your investment decision from your ego. A stock does not know you own it. It cannot vindicate or humiliate you. It is simply performing based on the business behind it.
Bias 4: Anchoring
Anchoring is the tendency to rely too heavily on the first piece of information encountered when making decisions. In investing, anchoring typically involves fixating on a stock’s previous high price as a reference point for its “correct” value.
A Pakistani investor who bought a stock at PKR 150 and watches it fall to PKR 90 may hold it not because they have carefully assessed the business at PKR 90 but because PKR 150 is anchored in their mind as the reference point. They are waiting to “get back to even” rather than asking whether PKR 90 represents good value for the business right now.
Similarly, an investor who sees a stock that previously traded at PKR 300 now trading at PKR 120 may perceive it as cheap purely because of the historical price anchor, without assessing whether the business fundamentals have changed in ways that justify the lower price.
Research published in 2024 specifically identified anchoring and adjustment as having a statistically significant impact on investment decisions in PSX, confirming that Pakistani investors are particularly susceptible to this bias in their local market context.
How to protect yourself: When evaluating any investment, ask whether you would be comfortable buying it fresh today at the current price, with no knowledge of what it cost you previously or what its historical high was. If the answer is no, the historical price anchor is distorting your judgment. Evaluate every position on its current merits, not its history.
Bias 5: Recency Bias and Availability Heuristic
Recency bias is the tendency to give excessive weight to recent events when making predictions about the future. Whatever happened most recently feels most representative of what will always happen. After a sustained bull market on PSX, investors assume the market will keep rising indefinitely. After a significant crash, they assume it will keep falling.
The availability heuristic is related. It describes the tendency to judge the likelihood of events based on how easily examples come to mind. If you personally know three people who made significant money on a specific stock, your mind overweights the probability of that outcome, even if dozens of people lost money on the same stock and simply did not broadcast it.
Both of these biases are amplified significantly in Pakistan’s social media-heavy investment culture. WhatsApp groups and investment communities naturally surface success stories more than failure stories. The vivid, easily recalled examples of friends or relatives who got rich on a specific stock or sector systematically distort your assessment of the probability of similar outcomes.
How to protect yourself: Actively seek out the base rate for investment outcomes, not just the memorable examples. For every person you know who made significant money on a speculative investment in Pakistan, ask how many others in the same situation did not. Maintain a long-term perspective by reviewing historical market data rather than relying on the most recent period as your primary frame of reference.
Bias 6: Confirmation Bias
Confirmation bias is the tendency to seek out, favour, and remember information that confirms beliefs you already hold, while ignoring or discounting information that challenges them.
An investor who has decided to buy a particular stock will typically spend their research time finding reasons that support the purchase and unconsciously dismissing or minimizing the concerns they encounter. The research feels thorough because significant time is spent on it, but it is systematically skewed toward the conclusion already reached.
In Pakistan’s investment community, where investment ideas often circulate through social networks with strong group conviction attached to them, confirmation bias is amplified by social dynamics. Questioning the consensus view of a WhatsApp group investment tip can feel socially uncomfortable, which further reinforces the tendency to seek confirming evidence rather than balanced assessment.
How to protect yourself: For every investment you are considering, spend deliberate time specifically looking for the strongest possible argument against making it. What would have to be true for this investment to fail? What are the bears saying about this stock or sector? Is their argument weaker than your bullish case, or are you unconsciously discounting it? Actively steelmanning the opposing view before committing to any significant position is one of the most effective antidotes to confirmation bias.
Bias 7: The Disposition Effect
The disposition effect is a specific and well-documented behavioral pattern that describes the combined impact of loss aversion and anchoring on selling behavior. It is the tendency to sell winners too early to lock in gains, while holding losers too long to avoid realizing losses.
Research in Pakistan specifically confirms this pattern at PSX. The result is a systematic erosion of returns. The investor ends up with a portfolio increasingly concentrated in underperforming stocks while the winning positions that drove gains are sold prematurely.
Warren Buffett famously described the disposition effect’s ideal antidote: “Cut your losses and let your winners run.” Most retail investors in Pakistan, and globally, do the exact opposite.
How to protect yourself: Review your portfolio periodically and honestly ask whether each holding is still the best use of that capital going forward, not whether it has risen or fallen since you bought it. A winning stock that continues to be fundamentally excellent deserves to stay in the portfolio. A losing stock that no longer has a compelling investment case deserves to be sold regardless of the loss.
Bias 8: FOMO-Driven Investing in Pakistan’s Digital Age
Fear of Missing Out deserves its own section in the Pakistani context because the country’s social media-driven investment environment amplifies FOMO to an unusual degree.
WhatsApp groups sharing hot tips, YouTube channels promoting specific stocks, and social media posts celebrating short-term gains create a constant stream of apparent opportunities that others are acting on and that you are missing. The psychological pressure to participate can be intense, particularly during bull market phases when the stories of quick gains are most prevalent.
FOMO-driven investing has several predictable and costly patterns. It drives entry into positions at extended valuations after significant price rises have already occurred. It creates urgency that bypasses careful research. And it generates excessive portfolio turnover as investors chase the latest opportunity rather than staying with a well-considered strategy.
Social media sentiment in Pakistan’s closed-group dynamics, particularly on WhatsApp and Facebook, has been specifically identified in research as generating anxiety and herd mentality that affects PSX trading behavior, with retail investors particularly susceptible.
How to protect yourself: Create and follow an investment policy for yourself that specifies what types of investments you will consider, at what valuations, and through what research process. When a hot tip arrives through social media or a WhatsApp group, measure it against your policy before acting. Most tips will not meet the criteria. Those that pass deserve proper research, not impulsive action. Missing a few opportunities is a far smaller cost than the losses generated by consistently acting on FOMO without adequate analysis.
Building Psychological Resilience as a Pakistani Investor
Understanding these biases is only valuable if it translates into different behaviors. Here are the practical habits that protect you from the most costly psychological mistakes.
Write down every investment decision before making it. The act of writing forces clarity and slows the emotional reaction enough for rational analysis to engage. Write the specific reason you are buying, the price at which you would sell if the thesis proves wrong, and what would need to be true for the investment to succeed. This creates accountability to your rational self rather than your emotional impulses.
Create an investment policy and stick to it. A simple written statement of what you invest in, how much research you require before buying, what allocation limits you maintain per stock and sector, and under what conditions you sell removes many in-the-moment decisions from emotional influence.
Review your decisions honestly. Keep a record of what you bought, why, what happened, and why. The discipline of honest self-review over time builds genuine self-knowledge about your actual tendencies and weaknesses as an investor.
Limit your consumption of market noise. The more financial news, social media investment content, and WhatsApp group tips you consume, the more cognitive fuel you are providing for every bias described above. Serious long-term investors in Pakistan consistently report that reducing their exposure to short-term market noise improved both their decision-making quality and their emotional experience of investing.
Talk to a trusted, knowledgeable person before major decisions. Having someone you trust who can challenge your reasoning before you commit to a significant investment provides an external check on confirmation bias and overconfidence that internal reflection alone cannot fully achieve.
Conclusion
Behavioral finance is ultimately not about pointing out that investors are irrational. It is about recognizing that specific, predictable psychological patterns consistently lead to poor investment outcomes, and that awareness of these patterns gives you a genuine advantage over investors who remain unaware of them.
Pakistani investors operate in an environment that is particularly rich in behavioral bias triggers: a social media-driven information ecosystem, strong cultural networks that amplify group thinking, a market with significant retail participation, and an economic history that creates deep emotional associations with money and its loss.
The investors who build lasting wealth on PSX are not necessarily the most analytically sophisticated. They are the ones who have learned to recognize when their own psychology is working against their investment goals, and who have built the habits and the structures to make better decisions in spite of it.
You now know what those patterns are. The next step is simply watching for them in yourself.