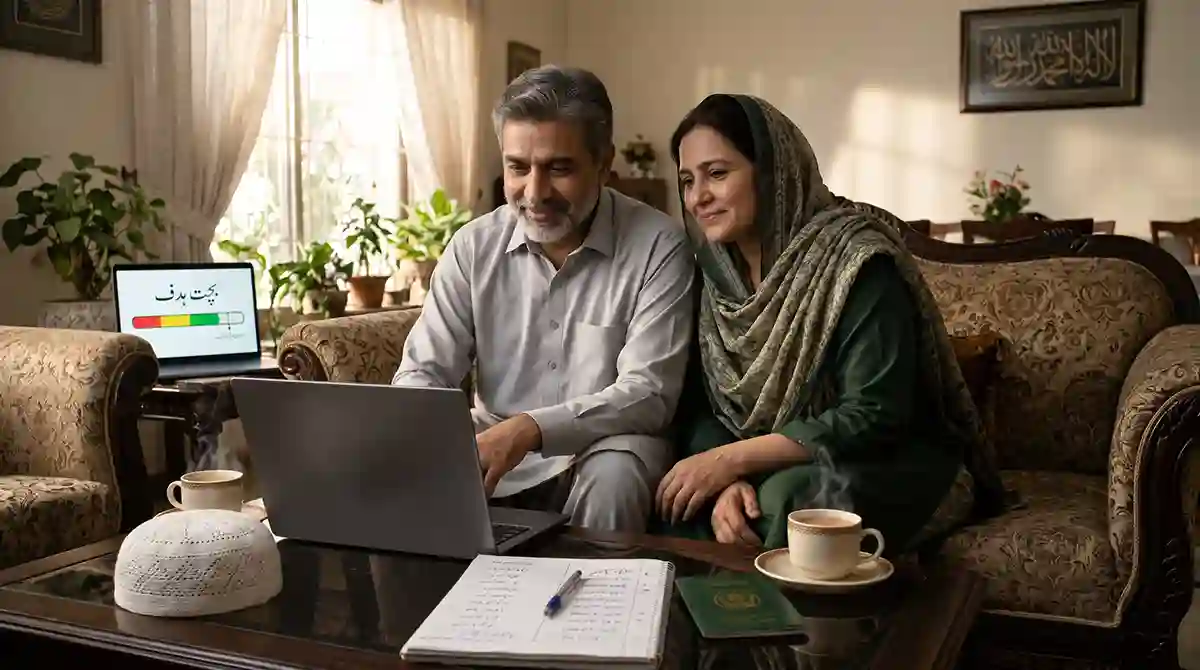
For Hajj 2027, the government scheme has been announced at PKR 1.2 million for the long package and PKR 1.3 million for the short one. The religious affairs minister has said the cost has risen by more than PKR 300,000 over the past five years, according to media reports. Anyone who sets out to save for Hajj or Umrah in Pakistan is chasing a target that moves every year, which makes the plan matter as much as the intention. Here you will know how to save for hajj or umrah in Pakistan.
This guide is about the money side only: what the trip costs in October 2026, how to adjust that number for the years you will spend saving, how much to put away each month, and where to keep it. Questions about eligibility, obligation, or whether a particular way of paying is permissible belong with a qualified scholar, not with a finance article.
Table of Contents
What It Costs Right Now
Before you know how to save for hajj or umrah in Pakistan you need to know what it costs right now. Official Hajj figures below come from the Ministry of Religious Affairs announcement as reported by media. Umrah and private Hajj prices are set by operators, so treat them as estimates and get written quotes.
| Item | Cost | Source Type |
|---|---|---|
| Hajj 2027, government scheme, long package (38 to 42 days) | PKR 1,200,000 | Ministry announcement, as reported |
| Hajj 2027, government scheme, short package (20 to 25 days) | PKR 1,300,000 | Ministry announcement, as reported |
| Optional Makkah room upgrade, triple or double (per person) | Plus PKR 70,000 or plus PKR 210,000 | As reported |
| Hajj, private operators | Roughly PKR 1.4 million to over PKR 2.5 million, depending on hotel, distance, and services | Operator-priced; sources differ |
| Umrah, economy, off-peak, 7 to 10 nights | About PKR 220,000 to 300,000 | Operator estimates |
| Umrah, economy, 14 days | About PKR 320,000 to 480,000 | Operator estimates |
| Umrah, last ten nights of Ramadan | About PKR 500,000 to 800,000 or more | Operator estimates |
| Umrah visa fee | About SAR 300, cited by several guides from Saudi ministry guidance | Verify with your operator |
Compared with the 2026 reference figures of PKR 1.15 million and PKR 1.2 million, the 2027 packages are about 4.3 percent and 8.3 percent higher, according to the same reports. The 2027 policy, reported as a first four-year framework running to 2030, also changed how applications work. One report described the 2027 scheme as first come, first served, while older guides describe a ballot, so confirm the current process with the Ministry. Applications for 2027 opened in August 2026. If you missed that window, you are planning for a later year, at a later price.
Why the Target Moves, and How Much
Hajj costs depend on airfare, accommodation, exchange rates, and the Ministry’s own pricing decisions, all of which have drifted upward. If the PKR 300,000 five-year rise the minister described took the cost from roughly PKR 1.0 million to PKR 1.3 million, that is about 5.4 percent a year, though I do not have the exact base year, so treat it as a rough reading. Pakistan’s general inflation was near 11 percent in mid-2026.
Rather than guess one rate, plan with a range. Here is what PKR 1.3 million per person today becomes:
| Years Away | At 5% a Year | At 8% a Year | At 11% a Year |
|---|---|---|---|
| 3 | PKR 1,504,913 | PKR 1,637,626 | PKR 1,777,920 |
| 5 | PKR 1,659,166 | PKR 1,910,126 | PKR 2,190,576 |
| 10 | PKR 2,117,563 | PKR 2,806,602 | PKR 3,691,247 |
I use 8 percent as the planning figure, between the rough historical reading and general inflation. Revisit it each year against the actual announced cost.
A Worked Plan: A Couple Saving for Five Years
Suppose a couple wants to go in five years. At 8 percent growth, the cost per person becomes about PKR 1,910,000, so the couple needs about PKR 3,820,000. The monthly amount depends on what the savings earn.
| Average Return on Savings (Before Tax) | Monthly Saving Needed (Couple) | Monthly Saving Needed (One Person) |
|---|---|---|
| 0 percent (cash at home) | PKR 63,671 | PKR 31,835 |
| 8 percent | PKR 51,993 | PKR 25,996 |
| 10 percent | PKR 49,334 | PKR 24,667 |
| 12 percent | PKR 46,777 | PKR 23,388 |
Returns are illustrative and before tax. Even so, the table shows the point: keeping cash idle costs a couple about PKR 14,000 more every month than an investment earning 10 percent.
The cost of waiting. Starting two years later and saving for only three years toward the same date raises the couple’s monthly amount at 10 percent from PKR 49,334 to PKR 91,433, about 1.85 times as much. Starting early with a smaller number beats starting late with a bigger one.
Where to Keep the Money, by Time Horizon
The right vehicle depends on how long you have, using the same glide-path logic as the child education guide in this series.
| Time to Departure | Suitable Home | Reason |
|---|---|---|
| 7 or more years | A Shariah-compliant balanced or equity fund for part of the money, plus Islamic income funds | Time to ride out market swings and outpace the rising cost |
| 3 to 7 years | Islamic income funds, Government Ijarah Sukuk through a fund, and National Savings Sarwa Islamic products | Lower volatility, profit-based returns |
| Final 2 years | Capital-protected options, for example a National Savings Sarwa Islamic term account, which paid 9.96 to 10.44 percent in mid-2026 depending on tenure, or an Islamic money market fund | A fixed deadline cannot afford a market drop |
| Final year | Liquid, low-risk holdings | You will need the money on a schedule set by the scheme |
Rates move, so check current figures. If you are Shariah-conscious, the Islamic fund and National Savings Sarwa options, covered in the Sukuk and National Savings articles in this series, keep the whole plan inside Islamic structures.
Have the First Instalment Ready
The government scheme asks successful applicants to pay in stages, with the first instalment reported at 50 percent of the package. That means you need PKR 600,000 for the long package or PKR 650,000 for the short one available soon after selection, plus any room upgrade.
Whatever you choose to invest in the final year, make sure that amount sits in something liquid and capital-protected. Other items to line up include a passport valid for the period the Ministry specifies, which was reported as until 16 November 2027 for the 2027 season, and a separate budget for spending money and any costs the package does not include. Check what your specific package covers.
A Simple Umrah Plan
Umrah is more flexible and costs less, but prices swing with the season. For a target of PKR 300,000, 450,000, or 600,000:
| Target | Monthly Saving Over 12 Months (No Return) | Over 12 Months at 10% | Over 24 Months at 10% |
|---|---|---|---|
| PKR 300,000 | PKR 25,000 | PKR 23,875 | PKR 11,343 |
| PKR 450,000 | PKR 37,500 | PKR 35,812 | PKR 17,015 |
| PKR 600,000 | PKR 50,000 | PKR 47,750 | PKR 22,687 |
Traveling outside the peak Ramadan period typically lowers the cost, so the same savings can go further. Build your target from a written operator quote, and add a buffer.
Protect the Money You Have Saved
Hajj and Umrah savings are exactly the kind of money that scammers target, because the amounts are large and the goal is emotionally important. Use only operators licensed by the Ministry of Religious Affairs, confirm the license directly with the Ministry, and ask for a written package listing flights, hotels, dates, and what is included.
Pay by bank transfer to a company account, not cash to an individual, and keep the receipts. Be wary of prices far below the market, pressure to pay everything immediately, or an agent who cannot show a license. The investment scam checklist in this series applies here with extra force.
If the trip is likely to need borrowing, remember that personal loan markup in Pakistan has run around 26 to 36 percent, so a loan multiplies the cost, and whether borrowing is appropriate at all is a question for a scholar.
Common Mistakes People Make
Anchoring to today’s price. The number you see now is not the number you will pay in five years.
Keeping the fund in cash or the home safe. Idle money gives up a large part of the monthly saving shown in the table.
Putting the fund in equities near the departure date. A drop in the final year can wreck a fixed deadline.
Mixing the fund with your emergency money. One unexpected expense should not eat the Hajj fund, so keep an emergency fund separately.
Forgetting the extras. Spending money, upgrades, and items outside the package can add up.
Trusting an unlicensed agent because the price is low. The loss is financial and emotional.
Waiting for a lump sum. A modest monthly habit started now costs far less than a large catch-up payment later.
Summing Up
Saving for Hajj or Umrah rewards the same habits as any long-term goal: calculate the target in inflation-adjusted terms, automate a monthly amount, match the vehicle to the time horizon, and shift toward capital protection as the date approaches. The government Hajj cost has been rising, and the worked example shows that starting now rather than two years later almost halves the monthly commitment.
Set up a dedicated account or fund this week, pick a planning rate, write down your first-instalment figure, and revisit the target every time the Ministry announces a new price. That is a plan you can keep, and a trip you can actually fund.
Further reading and official sources:
- Ministry of Religious Affairs, Government of Pakistan, Hajj policy, scheme announcements, and licensed operators: mora.gov.pk
- Saudi Ministry of Hajj and Umrah, visa and pilgrim information: haj.gov.sa
This is holy task for every Muslim in the world.
Yes, it is.